Home Blog Page 69

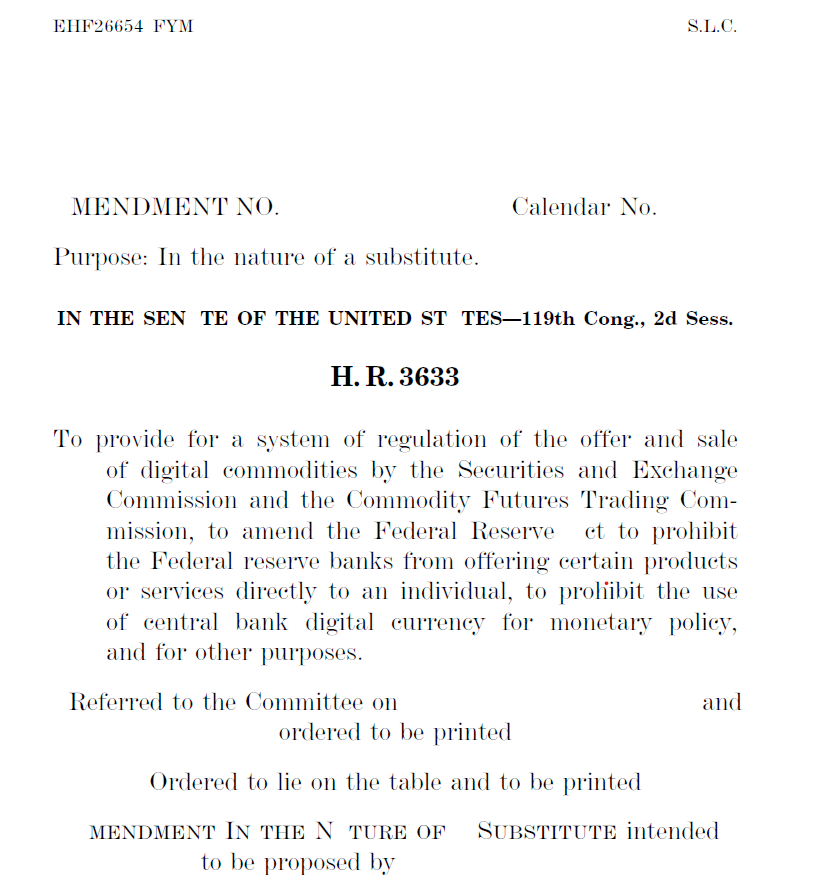
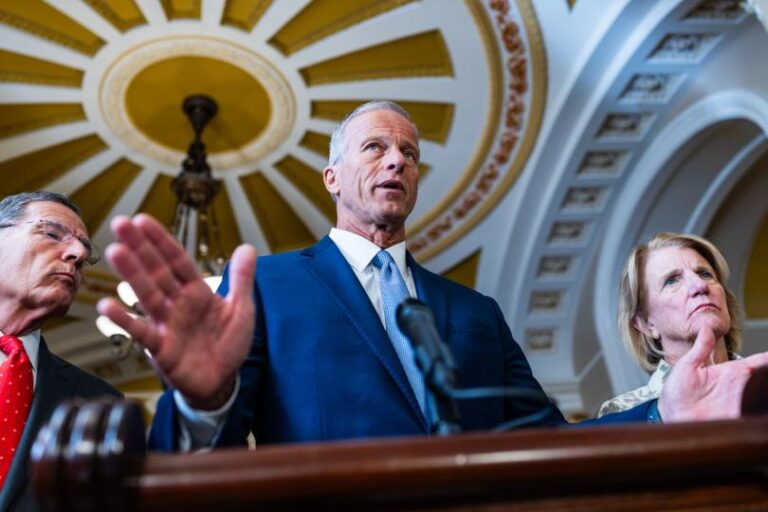
Clarity Act expected to miss its window before Congress’ summer break, leadership says

0

The crypto industry had held out optimism that the Senate could finish the wide-ranging Clarity Act in the next couple of weeks. Dragging it into the later months of the year sharply reduces its odds for passage in 2026.

Clarity — even more than last year’s Guiding and Establishing National Innovation for U.S. Stablecoins (GENIUS) Act — is the crypto industry first priority in crypto policy, with the hope it finally secures a permanent legal foundation for U.S. crypto activity.

The Senate’s floor process is a multi-stage affair that can take a few days or even longer to advance legislation past the 60-vote threshold needed in that chamber. At this stage, the crypto bill is hardly guaranteed to muster even a majority, as some Republican senators have also raised concerns with its treatment of stablecoin yield and the language of the government-ethics provision.

Senator Cynthia Lummis, a Wyoming Republican who has been a lead Clarity Act negotiator, told CoinDesk in a Wednesday interview that the most contentious sections are still open for revision that she said could bring Democrats to support it.

Republicans and industry insiders had hoped that getting the bill to the Senate floor might sharpen its urgency and help drive deals among the lawmakers to iron out the final disagreements. That could still happen if Thune can find some floor time before recess.

It’s time for tokenization to get to work

0

Q. Not all tokenized equity products are the same. What is the most important distinction to understand?

The central question is what the token actually represents. In the strongest model, the token is the share itself, meaning ownership, voting rights and dividends travel with it. In a synthetic wrapper, the investor owns a contractual claim against another entity, not the underlying share, introducing counterparty risk, tracking risk and the possibility that corporate actions do not pass through correctly.

Two tokens with the same ticker can represent very different instruments. The SEC’s January 2026 staff statement drew this distinction explicitly. For advisors evaluating these products, the structure is not a technical detail. It determines what rights the holder actually has.

Q. How developed is the regulatory framework at this point?

More developed than most people realize, but with gaps remaining. In the past eight months, the SEC issued a no-action letter for DTC tokenization services, published a staff statement establishing ownership taxonomy and approved Nasdaq’s proposal to trade tokenized securities alongside conventional shares. DTCC completed its first live production transactions this month.

Despite the progress, uncertainty still exists. Tokenized equities remain largely restricted to non-U.S. or accredited investors, the CLARITY Act has not been enacted, and third-party synthetic models carry more legal uncertainty than issuer-sponsored structures. The framework is building in a clear direction, but there is still much to accomplish to drive confidence and adoption.

Tassat wants to help smaller banks tap the stablecoin boom before big banks lock them out

0

The announcement comes as stablecoins move further into mainstream finance following the passage of the GENIUS Act. Wall Street firms and banks are expanding stablecoin initiatives, while Citi projects the market could reach roughly $4 trillion by 2030.

At that scale, Sussman said, concentrating reserves among a few institutions could create liquidity and deposit risks.

“If you assume stablecoins scale to $5 trillion or $10 trillion, then there has to be something that helps the market reach equilibrium,” Sussman said. “It can’t just live in a really small circle because that will compound the risk on both sides.”

The platform itself will not run on a blockchain, though Tassat plans to connect it with tokenized asset and deposit networks. Sussman said that approach lowers the technical burden for smaller banks.

“There is a real risk that vast swaths of the U.S. banking ecosystem get left out in the cold,” he said. “I don’t think that’s healthy politically for the United States. I don’t think it’s healthy economically.”

Banxa Integrates LI.FI to Give Fiat Buyers Broader Access to Onchain Assets

0

  • Banxa has integrated LI.FI to give users broader access to tokens, DeFi products and tokenized assets across more than 60 blockchains.
  • The integration allows Banxa to use decentralized liquidity and cross-chain routing behind the scenes, reducing the steps between a fiat payment and the user’s preferred onchain asset.

Banxa has integrated LI.FI’s liquidity-routing technology, expanding the range of tokens and blockchain networks available through its fiat-to-crypto infrastructure.

The agreement is designed to shorten the path between a fiat payment and the asset a user ultimately wants to hold. Instead of requiring users to separately buy an intermediary token, select a blockchain, use a bridge and complete a swap, Banxa can route those steps through a single onboarding flow.

LI.FI aggregates liquidity from decentralized exchanges, bridge protocols and intent-based systems. Its infrastructure currently covers more than 60 blockchain networks and is used by more than 1,000 enterprise integrations.

The integration provides Banxa access to decentralized exchange-sourced liquidity alongside its existing fulfillment partners.

That could help the company support assets that are not readily available through a single centralized exchange or liquidity provider. LI.FI’s routing engine evaluates factors including liquidity, fees, gas costs and slippage before selecting an execution path.

“Crypto users shouldn’t have to think about bridges, liquidity routes, or which blockchain an asset lives on. They should simply be able to access what they want,” LI.FI co-founder and CEO Philipp Zentner said in a statement shared with AlexaBlockchain.

“The next phase of crypto adoption will be defined by experiences that are intuitive, not technical,” he added. “By working with Banxa, we’re helping make that possible for millions of users while giving platforms a scalable way to connect users with the growing universe of onchain assets.”

From Crypto On-Ramp to Onchain Routing

Traditional fiat on-ramps have typically focused on the first stage of a transaction: converting dollars, euros or another national currency into a limited selection of cryptocurrencies.

That model works well when a user only wants Bitcoin, Ether or a major stablecoin.

It becomes less efficient when the intended destination is a token on another blockchain, a decentralized finance vault or a tokenized real-world asset. Users may need to complete additional swaps and bridge transactions after the initial purchase.

The LI.FI integration allows Banxa to treat those steps as part of a broader fulfillment process.

“Liquidity shouldn’t be a bottleneck to crypto adoption,” Banxa Chief Growth and Product Officer Shaun Heng said.

“By integrating LI.FI, we’re diversifying our fulfillment sources beyond traditional exchange partners and unlocking DEX-sourced liquidity for more assets — all while maintaining the compliance rigor our partners and millions of users expect,” Heng added. “It’s a direct investment in faster, more efficient delivery for every Banxa-powered transaction.”

Banxa provides payment, identity-verification, compliance and settlement infrastructure that businesses can embed into wallets, exchanges and financial applications.

The company began operating in 2014 and later shifted its focus toward business-to-business payment and compliance infrastructure for fiat-to-crypto transactions.

Its developer documentation says the service is available across more than 150 countries and holds 45 regulatory licences. Banxa also offers hosted checkout products and a Native API for companies seeking an embedded user experience.

Banxa said in the announcement that it has processed more than $10 billion in cumulative transactions. Its current developer website separately describes $10 billion as “annual transaction volume,” meaning the precise measurement period for the figure is unclear.

More From AlexaBlockchain

Why the Integration Matters

The agreement reflects a change in what users expect from crypto onboarding.

Early on-ramps were primarily designed to help first-time buyers acquire a major cryptocurrency. Newer applications increasingly need to deliver stablecoins, DeFi positions and tokenized investments across different networks.

That makes asset routing almost as important as payment processing.

A user purchasing an onchain asset does not necessarily care which exchange, bridge or decentralized liquidity pool completes the transaction. The user is more likely to care about the final price, completion time and whether the correct asset appears on the correct network.

Combining Banxa’s regulated fiat-payment infrastructure with LI.FI’s onchain routing layer could abstract more of that complexity.

However, the integration does not eliminate execution risk. Cross-chain transactions can still be affected by changing liquidity, slippage, blockchain congestion, smart-contract vulnerabilities and bridge security.

The commercial outcome will therefore depend on whether the companies can improve transaction completion and asset availability without adding excessive fees or execution risk.

A Broader Infrastructure Race

Banxa and LI.FI are not alone in attempting to consolidate the crypto onboarding journey.

Onramper connects applications to more than 30 fiat on-ramps and 175 payment methods through a single integration. Its routing system ranks providers using factors such as pricing, expected transaction success and user friction.

Onramper says its recommended-provider routing can increase conversion rates by an average of 240% compared with the conversion rate of an average individual on-ramp. That is a company-reported figure and may vary significantly by geography, payment method and transaction type.

MoonPay has taken a different approach by offering headless fiat on-ramps that allow businesses to embed card, Apple Pay and Google Pay purchases directly into their interfaces. The company says its ramp products operate across 160 countries.

Transak also offers white-label on- and off-ramp infrastructure. Its API supports more than 136 cryptocurrencies across over 45 blockchains, while handling identity checks, transaction monitoring and compliance for partner applications.

Stripe has similarly integrated crypto purchasing into its broader payments stack, allowing customers to buy digital assets inside third-party products. Stripe is also combining its on-ramp services with Bridge’s stablecoin infrastructure and Privy’s wallet technology.

The distinction in the Banxa-LI.FI agreement is its emphasis on connecting the fiat entry point directly with decentralized and cross-chain liquidity.

Tokenized Assets Raise the Stakes

The need for broader routing is likely to grow as wallets and fintech applications add tokenized securities and real-world assets.

LI.FI has already integrated tokenized assets issued through platforms including Ondo Global Markets. It says existing enterprise partners can make supported tokenized stocks available without building a separate integration for each issuer.

The protocol was also a launch partner for Robinhood Chain, providing swaps, stock-token routing and one-click deposit flows. Robinhood launched its chain and stock-token products on July 1, with eligible users in more than 120 countries able to access tokenized assets through Robinhood Wallet.

LI.FI’s role in those ecosystems illustrates the longer-term strategy behind the Banxa agreement.

Fiat on-ramps are evolving from simple cryptocurrency checkout tools into distribution gateways for a wider range of blockchain-based financial products.

Banxa is adding an orchestration layer between the user’s payment and the final asset.

The intended benefit for users is fewer manual transactions.

And, the potential advantage for Banxa and its business partners is the ability to support more assets and networks without integrating every decentralized exchange, bridge and blockchain separately.

The above article “Banxa Integrates LI.FI to Give Fiat Buyers Broader Access to Onchain Assets” was first published on AlexaBlockchain. Read the complete article here: https://alexablockchain.com/banxa-integrates-li-fi-to-give-fiat-buyers-broader-access-to-onchain-assets/

Read Also: This is the First U.S.-Chartered Depository Bank to Offer Stablecoin Invoicing

Disclaimer: The information provided on AlexaBlockchain is for informational purposes only and does not constitute financial advice. Read complete disclaimer here.
Swiss Bank BancaStato Brings Bitcoin and Ether Trading Into Its Banking App

0

Swiss Bank BancaStato has started offering regulated cryptocurrency trading to clients through a partnership with Sygnum and banking software provider Avaloq. This brings another Swiss lender to the group of banks embedding digital assets inside existing online banking systems.

The Ticino cantonal bank has connected Sygnum’s business-to-business API with Avaloq’s core banking and digital banking channels.

The integration allows BancaStato clients to buy, hold and sell Bitcoin, Ether, Litecoin and Solana directly through the bank’s web and mobile banking applications, without using a separate crypto exchange or external wallet.

The rollout is notable because BancaStato is using Sygnum’s API directly inside Avaloq’s software-as-a-service environment.

According to Sygnum, BancaStato is the first bank on Avaloq’s SaaS environment to let clients buy, hold and sell crypto through Sygnum’s API from within its e-banking platforms.

That matters because much of bank crypto adoption has so far been blocked not by client demand, but by plumbing.

Banks need regulated custody, trading execution, compliance controls, risk management and integration with legacy core banking systems. A direct API model can reduce the need for a separate order management system, lowering operational complexity and shortening the path to launch.

“We are proud to welcome BancaStato to our fast-growing B2B network, which illustrates the growing demand for Sygnum’s regulated, API-driven digital asset services that integrate directly into existing core banking systems,” Fritz Jost, Sygnum’s Chief B2B Officer, said in a statement shared with AlexaBlockchain.

“BancaStato, becoming the first bank on Avaloq’s SaaS environment to enable clients to buy, hold and sell crypto via API with Sygnum directly from within its e-banking platforms, marks a significant step in the maturity and scalability of regulated digital asset infrastructure,” Fritz added.

BancaStato, formally Banca dello Stato del Cantone Ticino, is the cantonal bank serving Ticino in southern Switzerland.

The bank and its private banking affiliate Axion SWISS Bank renewed their Avaloq Core Platform agreement in 2023, with Avaloq saying at the time that both institutions used Avaloq’s platform in a SaaS model and its banking operations offering.

For clients, the immediate change is access.

They can place market orders by quantity or dollar value inside existing e-banking and mobile banking channels. Sygnum will provide the execution and custody layer, while BancaStato keeps the front-end relationship with clients.

Client assets will be held through Sygnum’s custody infrastructure and kept off-balance sheet, according to the announcement.

That structure is important in Switzerland because it is intended to give clients legal and regulatory protection if a custodian becomes insolvent, although crypto assets remain volatile and can lose value sharply.

The launch also extends Sygnum’s bank-to-bank strategy.

Sygnum said in 2024 that its B2B partners included PostFinance, Zuger Kantonalbank, Luzerner Kantonalbank, VZ Depotbank, PKB, SocGen Forge, Bordier and Bison Digital Assets, and that those partners collectively gave more than a third of Switzerland’s population access to digital assets through partner banks.

PostFinance is one of the more visible examples.

The Swiss financial institution launched a crypto offering with Sygnum in 2024 for its 2.5 million customers, allowing users to access crypto through PostFinance’s own e-finance and app channels.

In May 2026, PostFinance expanded the service to corporate clients, allowing them to trade 22 cryptocurrencies and stake Ethereum directly through e-finance or the PostFinance app.

Those launches show how Swiss bank crypto adoption is shifting from standalone experiments to embedded banking services.

Instead of asking clients to move funds to a crypto-native venue, banks are trying to keep the account, trading interface and custody relationship inside their existing regulated perimeter.

BancaStato’s launch comes shortly after Sygnum Europe received a Crypto-Asset Service Provider licence in Liechtenstein under the EU’s Markets in Crypto-Assets Regulation.

Sygnum said the licence, announced on June 30, allows it to expand its regulated platform and bank-to-bank infrastructure into the European market as MiCAR’s transition period ends.

The timing is significant.

MiCAR gives crypto-asset service providers a harmonized licensing framework across the European Union, making it easier for banks to evaluate regulated partners rather than build digital-asset infrastructure from scratch in each market.

Sygnum has been building around that model for years.

The company received a banking and securities dealer licence from Switzerland’s financial regulator FINMA in 2019, one of the first such licences granted to blockchain-focused financial institutions in the country.

It has also grown financially.

Sygnum reached a $1 billion valuation in 2025 after raising $58 million, with Reuters reporting that the company planned to use the funds to expand in Europe and Hong Kong and invest in infrastructure and products.

The BancaStato deal fits into a broader Swiss push to connect traditional banking infrastructure with digital assets.

In April 2026, UBS, PostFinance, Sygnum, Raiffeisen, Zürcher Kantonalbank and BCV joined a sandbox project to test a Swiss-franc stablecoin, with the goal of exploring how blockchain applications could connect to the Swiss franc.

Swiss banks have also tested blockchain-based payment infrastructure.

In 2025, PostFinance, Sygnum and UBS completed a feasibility study for a binding payment using bank deposits on a public blockchain, according to the Swiss Bankers Association.

Market infrastructure is moving in the same direction.

FINMA approved BX Digital, a Swiss subsidiary of Boerse Stuttgart, to operate a blockchain-based trading system in 2025, with the platform designed to support tokenized assets and direct settlement using blockchain infrastructure.

The result is a more institutional phase of crypto adoption in Switzerland.

Earlier cycles were dominated by crypto exchanges, wallets and retail trading apps. The newer phase is being led by banks, software providers and regulated infrastructure firms trying to make crypto access look like another banking function.

With this launch, BancaStato adds a digital-asset product line without operating as a crypto exchange.

Christian Haux, Avaloq’s Managing Director for Switzerland and Liechtenstein, said the project shows how integration can help banks respond faster to investor expectations while keeping services on a unified platform.

For BancaStato clients, he said, the service allows them to view and manage digital and traditional portfolios in one place.

Swiss banks have shown that regulated crypto access can be embedded into mainstream banking apps. The harder question is whether clients use those services beyond Bitcoin and Ether exposure, and whether banks can turn digital assets into a durable revenue line rather than a defensive product extension.

The above article “Swiss Bank BancaStato Brings Bitcoin and Ether Trading Into Its Banking App” was first published on AlexaBlockchain. Read the complete article here: https://alexablockchain.com/swiss-bank-bancastato-brings-bitcoin-and-ether-trading-into-its-banking-app/

Read Also: This is the First U.S.-Chartered Depository Bank to Offer Stablecoin Invoicing

Disclaimer: The information provided on AlexaBlockchain is for informational purposes only and does not constitute financial advice. Read complete disclaimer here.
The SEC settles with Coinbase over its missing Gary Gensler texts

0

The U.S. Securities and Exchange Commission (SEC) agreed to pay $150,000 to settle a federal Freedom of Information Act (FOIA) lawsuit over its investigations into Ethereum, according to a joint status report filed July 22.

History Associates Inc. and the SEC asked the U.S. District Court for the District of Columbia to dismiss the case after reaching a settlement deal. Under the agreement, the agency will produce the remaining responsive documents and pay the flat fee to cover the plaintiff’s legal fees.

History Associates, which provides professional historical research, writing and archival services to government agencies, filed the lawsuit in June 2024. Working on behalf of Coinbase, the firm had submitted three public records requests the year before. Those filings sought documents on SEC investigations into Zachary Coburn and Enigma MPC, along with records on how Ethereum shifted to a proof-of-stake system.

The lawsuit compelled the SEC to hand over thousands of documents, with the court explicitly ordering the agency to prioritize all records and communications sent, received or evaluated by then SEC Chair Gary Gensler concerning Ethereum’s migration from a proof-of-work blockchain to a proof-of-stake network.

Coinbase’s corporate customers can now accept payments from AI agents

0

“We are delivering that experience for the new online agentic economy,” Coelho-Prabhu said in an interview. “Agents, on one side of the transaction, will go and read the Coinbase developer docs, create a wallet for themselves, and are ready to shop. Then we empower businesses so that everything in their inventory is now available on the internet through this agent-friendly checkout flow.”

For users of the exchange, they can get an easier command of crypto markets with a live order list that streams an agent’s open and active orders in real time, showing status, price, and size so the user can supervise every move, Coinbase said in a press release.

This will put agentic trading at the user’s fingertips, with the agent getting real-time market data and the ability to act on conditions autonomously. “Tell it what you want in plain English – ‘buy ETH if it dips 5%,’ ‘sell when my order fills’ – and it watches the market and executes for you. The same WebSocket data that powers institutional desks is now accessible through natural language,” Coinbase said.

In addition, for developers there’s a new x402 SDK from Coinbase Developer Platform, builders can now add x402 payment acceptance to any API, MCP server, or web service in 3 lines of code.

Why the CLARITY Act’s Ethics Fight Could Derail the Market Structure Bill

0

The long-awaited US Digital Asset Market Clarity Act (CLARITY) has hit another snag.

This time, it’s not software developers or the turf war between federal regulators at stake, but the thornier question of ethics — ironic, given many politicians’ demonstrable disdain for them.

After months of negotiations and what Coinbase’s chief executive Brian Armstrong called “thousands of hours of work on both sides,” disagreement over a code of conduct could make or break CLARITY once and for all.

Pretty much everyone agrees the United States needs clearer rules around digital assets. But negotiators are divided over whether the bill’s ethics provisions are strong enough, and, more importantly, who should enforce them.

Democrats worry the current proposal relies too heavily on the Department of Justice, arguing state attorneys general should be able to step in if the DOJ fails to enforce the law.

In a joint statement Wednesday, seven Democratic senators said the Republican proposal “falls short.”

“Key provisions including those addressing ethics for elected officials, consumer protection, illicit finance, conflicts of interest and market integrity must be strengthened,” the senators said.

For their part, Republicans are pushing to keep enforcement of the ethics provisions with the DOJ, arguing that federal rules should be enforced through a single national framework. Attorney and former Republican Senate candidate John Deaton said Wednesday:

“The CLARITY Act is federal legislation… The Department of Justice – not fifty different state AGs with fifty different political incentives and fifty different interpretations – is the appropriate body to enforce federal law.”

Can lawmakers find a middle path before the bill reaches the Senate floor, or has the ethics debate become CLARITY’s biggest obstacle yet?

What the latest ethics proposal actually does

The latest Senate draft made public Wednesday would prohibit the president, vice president, members of Congress and other senior federal officials and their spouses from issuing or sponsoring digital assets while in office.

Democrats oppose current CLARITY text. Source: Senator Ruben Gallego

That means future presidential meme coins would be off the table, at least temporarily, with no Trump 2.0 or Melania 2.0-style token launches while the restrictions are in play.

Related: CLARITY Act could help CFTC deal with prediction markets: Lawyer

The proposal would also prevent crypto platforms from listing assets issued or sponsored by covered officials.

Restrictions would expire in 2029, after President Donald Trump’s current term ends, though covered officials would still be permitted to own cryptocurrencies.

Democrats say current proposal falls short

Democrats have made it clear the text needs additional work before gaining their support, but getting CLARITY over the line isn’t doomed; they’ve also signaled a willingness to see the bill through to the end.

“We have been working in good faith with our Republican colleagues for the past year and will continue doing so to get this over the finish line,” the senators said.

Senator Angela Alsobrooks said negotiators were “fairly close” to reaching an agreement during a Semafor event on Wednesday, despite warning the ethics provisions remained a dealbreaker. The Maryland Democrat said:

“Although I have been supportive to this point, I absolutely will not support on the floor any legislation that does not include provisions around ethics.”

Her main concern is not only the substance of the rules, but who would enforce them.

“It’s an absolute that we cannot completely rely on the DOJ, given what we’ve seen of their inability and their unwillingness to enforce the law,” Alsobrooks said.

The debate has been fueled by Trump’s rapidly expanding crypto business interests spanning meme coins, World Liberty Financial and other digital asset holdings.

Related: Trump claims he can ‘future proof’ crypto regulation with CLARITY Act

The President’s crypto ventures have reportedly generated $1.4 billion on paper, prompting Democrats to argue stronger safeguards are needed to address potential conflicts of interest.

Senator Elizabeth Warren has focused on whether the restrictions go far enough, with the Massachusetts Democrat saying that the latest draft “does nothing to stop President Trump from making his next $1.4 billion from crypto.”

Former SEC official Amanda Fischer also argued the draft would still allow Trump to benefit from his existing projects, with limited restrictions on future crypto income streams.

Republicans say proposal already unprecedented

Republicans reject the idea that the ethics provisions are weak. Senator Bernie Moreno described the draft as containing “the most powerful ethics language in US history,” pushing back against Democratic claims that the provisions are insufficient.

The latest CLARITY Act text. Source: US Congress.

Patrick Witt, a former White House and Senate counsel, said Democratic opposition appeared to rest on one of two positions: either that ethics rules without state attorneys general are “meaningless,” or that they fail to penalize President Trump for past crypto activity.

“If you hold position (1), then you are basically saying that ALL current federal ethics laws are meaningless because none of them are enforceable by state AGs,” he said. “If you hold position (2), then there is literally nothing that can be done to appease you because what you are advocating for is blatantly unconstitutional.”

Others argue that, even if the legislation is imperfect, passing it would be preferable to preserving the status quo. Andreessen Horowitz co-founder Chris Dixon said the US has a similar opportunity to the early internet era, when lawmakers established rules that allowed innovation to flourish rather than forcing new technology into outdated regulatory frameworks.

While acknowledging that “no law is perfect,” Dixon argued the CLARITY Act would deliver long-overdue consumer protections and provide regulatory certainty for blockchain innovation in the US.

Can lawmakers find a middle path?

Despite stumbling over the ethics hurdle, most industry and policy observers still believe a deal remains in reach.

Kristin Smith, former chief executive of the Blockchain Association and now president of the Solana Policy Institute, sees that the latest draft is already a meaningful compromise.

“The new text includes a substantive, one-of-a-kind ethics provision, a necessary step to win the support of Senate Democrats,” Smith told Cointelegraph.

“But ethics is far from the only thing at stake. The Senate has added a full disclosure regime, an entire illicit finance section, and improved spot market regulation.”

Smith warned that rejecting the bill in pursuit of stronger ethics language could leave lawmakers stuck with no market structure legislation at all.

“There is no version of a ‘no’ vote that produces a stronger bill,” she said. “A ‘no’ vote produces no bill at all: no disclosure regime, no illicit finance protections, no spot market improvements, no ethics provisions, nothing.”

Vincent Chok, co-founder and chief executive of stablecoin issuer First Digital, said the fact negotiations have narrowed to ethics rather than the broader structure of the bill is itself a sign of progress.

“The core debate is no longer whether digital assets need a regulatory framework, but how to finalize one that commands broad support,” Chok told Cointelegraph.

He said that while no regulatory framework is likely to be perfect from day one, businesses can adapt to clear rules that evolve over time. Prolonged uncertainty makes long-term investment and product development far more difficult, he said.

Salman Banaei, head of public policy at Plume, a blockchain network focused on tokenized real-world assets, also believes a compromise remains possible, although he cautioned that the White House’s initial ethics proposal “is not a good starting point.”

For now, both sides appear to agree on one thing: a compromise is still possible, but exactly what it looks like remains the biggest unanswered question.

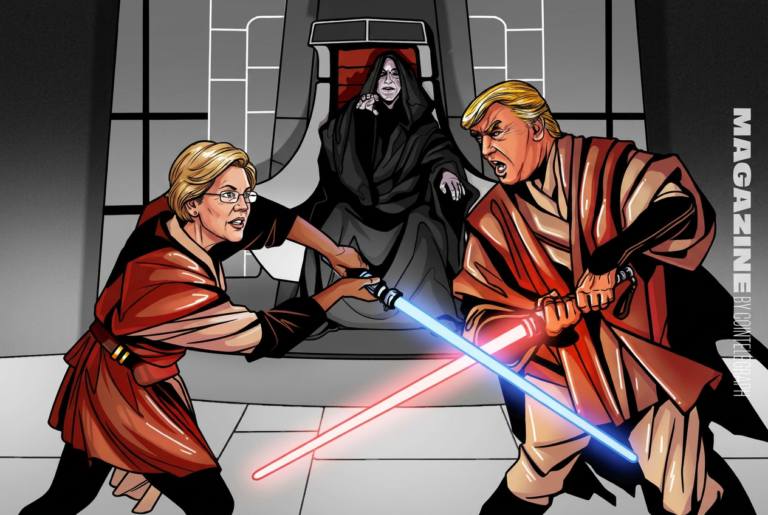
Magazine: Will the crypto lobby’s $189M campaign get CLARITY over the line?

Cointelegraph publishes long-form journalism, analysis and narrative reporting produced by Cointelegraph’s in-house editorial team with subject-matter expertise. All articles are edited and reviewed by Cointelegraph editors in line with our editorial standards. Content published in here does not constitute financial, legal or investment advice. Readers should conduct their own research and consult qualified professionals where appropriate. Cointelegraph maintains full editorial independence.

Lombard Opens Bitcoin-Backed Credit Vault With Flow Traders as First Borrower

0

  • Lombard Finance has launched a Bitcoin-backed onchain credit strategy with Flow Traders as its first borrower.
  • The structure allows Bitcoin holders to earn yield from institutional stablecoin financing demand, while Flow Traders accesses liquidity without posting its own collateral in a public DeFi lending pool.

Lombard Finance has launched an onchain credit strategy designed to connect Bitcoin holders with stablecoin financing demand from institutional trading firms.

Flow Traders, the Amsterdam-listed global market maker, is the first borrower using the new structure.

The Bitcoin Onchain Credit Strategy allows Flow Traders to obtain stablecoins for its digital-asset market-making operations without depositing its own collateral into a public DeFi lending pool.

Instead, Bitcoin supplied by investors to Lombard’s vault provides collateral coverage for the financing.

The arrangement attempts to solve a persistent problem in institutional DeFi lending.

Traditional crypto money markets generally require borrowers to post more collateral than they receive. That model reduces lender risk but makes the capital inefficient for market makers and other financial businesses that need working liquidity.

Institutional credit platforms have tried to address that limitation through underwriting, permissioned pools and bilateral lending structures.

Lombard’s model separates the institutional borrower from the investors supplying the collateral.

Flow Traders pays an underwriting premium for access to stablecoin liquidity. The premium is then passed to depositors in the Lombard strategy as Bitcoin-denominated yield, according to the announcement.

The stablecoin loans are facilitated through Cap, an onchain private-credit marketplace that uses smart contracts to allocate capital among approved borrowers.

Lombard did not disclose the amount Flow Traders plans to borrow, the premium it will pay or the targeted return for depositors. It also did not provide details about loan maturities, liquidation thresholds or the losses Bitcoin suppliers could face if the borrower defaults.

Those terms will be central to assessing whether the product can offer returns that are meaningfully more stable than existing crypto-credit strategies.

“Asset managers have a real, persistent need to borrow stablecoins, but until now, DeFi markets weren’t built in a way they could access,” Lombard Labs CEO Jacob Phillips said in a statement shared with AlexaBlockchain.

“This structure changes that. By separating the borrower from the collateral provider, the parties involved have made it possible for regulated, institutional trading firms to tap into onchain credit for the first time.”

Phillips said the yield would come from institutional borrowing demand rather than token incentives or speculative trading activity.

That distinction matters because many earlier DeFi yield products depended on the distribution of governance tokens. Returns frequently fell once those incentives were reduced or users moved their capital elsewhere.

Lombard’s strategy is instead tied to the financing needs of a market maker.

Flow Traders has operated in digital assets since 2017 and provides liquidity across crypto exchange-traded products, centralized venues and onchain markets. It has been expanding its digital-asset business, including the launch in March of a round-the-clock over-the-counter service for tokenized money-market funds, equities and commodities.

“Liquidity providers like Flow Traders use stablecoin financing to efficiently support their digital asset trading operations,” Michael Lie, Flow Traders’ global head of digital assets, said.

“Lombard’s Bitcoin Onchain Credit Strategy connects Bitcoin holders with institutional financing activity, driven by real institutional demand and less correlated to DeFi market conditions.”

Stablecoins are widely used by crypto trading firms as settlement assets, margin and working capital.

Having reliable access to stablecoin credit can allow a market maker to quote across more venues, manage inventory and settle trades without selling its longer-term asset holdings.

Moving Bitcoin Between Avalanche and Ethereum

The strategy also uses Chainlink’s Cross-Chain Interoperability Protocol, or CCIP, to accept BTC.b deposits from Avalanche into a vault operating on Ethereum.

That integration reduces the need for investors to manually bridge, exchange or reissue their Bitcoin-linked assets before entering the strategy.

Lombard had already selected CCIP as the exclusive interoperability system for more than $1 billion of Bitcoin-backed assets, including LBTC and BTC.b. The company said in May that it was consolidating cross-chain transfers around the Chainlink infrastructure.

Cross-chain distribution is important for lending products because crypto collateral is fragmented across multiple networks.

A vault limited to one chain can only draw liquidity from assets already present on that network. Interoperability can expand the depositor base, although it also introduces bridge, messaging and smart-contract risks.

Chainlink says CCIP uses independent node operators, transaction-rate limits and separate risk-management systems to reduce those risks. The protocol is intended to let financial applications move assets and instructions across networks through one integration.

Why the Structure Matters

The launch represents another attempt to turn Bitcoin from a largely passive holding into collateral for institutional credit markets.

A substantial share of Bitcoin remains outside DeFi because holders must often wrap the asset, transfer it between networks and accept additional custody or smart-contract exposure to earn a return.

Lombard is positioning Bitcoin Earn as an aggregation layer for several yield strategies rather than a single lending pool.

The company said the platform has attracted more than $1 billion from over 38,500 users since its launch. That figure was provided by Lombard and could not be independently verified from public onchain data at the time of publication.

The new Flow Traders allocation will sit alongside strategies including a Bitcoin money-market product managed by Sentora.

Combining several strategies may reduce dependence on one source of returns. It does not eliminate credit, collateral, liquidity, bridge or smart-contract risks.

The more significant innovation is the separation of borrower capital from collateral supplied by investors.

That structure could give trading firms access to credit without forcing them to lock up an equivalent or larger amount of their own assets. For Bitcoin holders, it creates a potential yield source linked to financial activity rather than token emissions.

It also shifts risk in a way investors will need to understand.

Depositors are effectively allowing their Bitcoin exposure to support financing extended to an institutional counterparty. The quality of underwriting, the enforceability of guarantees and the mechanism used to absorb defaults may matter more than the stated yield.

Earlier Onchain Credit Models Show Both Potential and Risk

Lombard is not the first platform to bring institutional borrowing onchain.

Maple Finance pioneered permissioned credit pools for crypto trading firms and later expanded into overcollateralized institutional lending. Maple says it has issued more than 400 loans worth a cumulative $23 billion and currently manages an institutional secured-lending pool of more than $800 million.

The platform’s history also shows the risks.

Maple suffered loan defaults after the collapse of FTX and the failure of several crypto trading businesses in 2022. It subsequently changed its default-management and lender-protection systems.

More recent secured products have performed better during market stress.

Maple said its loan book recorded no liquidations during a sharp crypto selloff in February 2025, after borrowers resolved 15 margin calls and maintained collateral coverage.

Goldfinch, Clearpool and other private-credit protocols have also used borrower underwriting or permissioned pools to reduce the need for full onchain collateral.

These models can improve capital efficiency, but they introduce conventional credit risks that automated, overcollateralized DeFi lending was designed to avoid. Borrower assessment, legal agreements and recovery processes become critical when onchain collateral alone is insufficient.

Cap founder Benjamin Sarquis Peillard said the platform was created to improve incentive alignment and liquidity in private credit.

“The fact that Flow Traders, one of the world’s leading global trading firms, is using our platform reflects the potential our platform has to compete in legacy markets,” he said.

The Flow Traders pilot gives Lombard a recognizable institutional borrower and a real-world test of its structure.

Its broader significance will depend on whether the model can attract additional borrowers, disclose sufficient risk information and deliver returns without exposing Bitcoin suppliers to losses that are difficult to evaluate.

The launch right now shows how Bitcoin yield products are moving beyond staking incentives and basic overcollateralized lending.

They are beginning to resemble structured credit funds, with smart contracts handling distribution while underwriting and counterparty risk remain firmly rooted in traditional finance.

The above article “Lombard Opens Bitcoin-Backed Credit Vault With Flow Traders as First Borrower” was first published on AlexaBlockchain. Read the complete article here: https://alexablockchain.com/lombard-opens-bitcoin-backed-credit-vault-with-flow-traders-as-first-borrower/

Read Also: This is the First U.S.-Chartered Depository Bank to Offer Stablecoin Invoicing

Disclaimer: The information provided on AlexaBlockchain is for informational purposes only and does not constitute financial advice. Read complete disclaimer here.