Home Blog Page 358

US Senator Gillibrand says crypto market structure vote could happen by August

US Senator Kirsten Gillibrand said lawmakers working towards passage of a digital asset market structure bill likely need to meet three conditions before the chamber could vote on the legislation.

Speaking at the Consensus conference in Miami on Wednesday, Gillibrand said she considered addressing consumer protection, illicit finance, and ethics provisions essential before any potential vote on the CLARITY Act. She said that if Congress were to consider those issues, as well as combine the draft of the market structure bill with the version already passed in the Senate Agriculture Committee and ensure ethics language, lawmakers could have a vote “before the August recess,” which begins Aug. 10.

“There will be no one voting for this bill if we don’t have an ethics provision,” said Gillibrand. “Because the truth is, is that we cannot allow members of Congress, senior administration officials, presidents or vice presidents, to get rich off of these industries because of their insider status. It is the worst form of pay for play.”

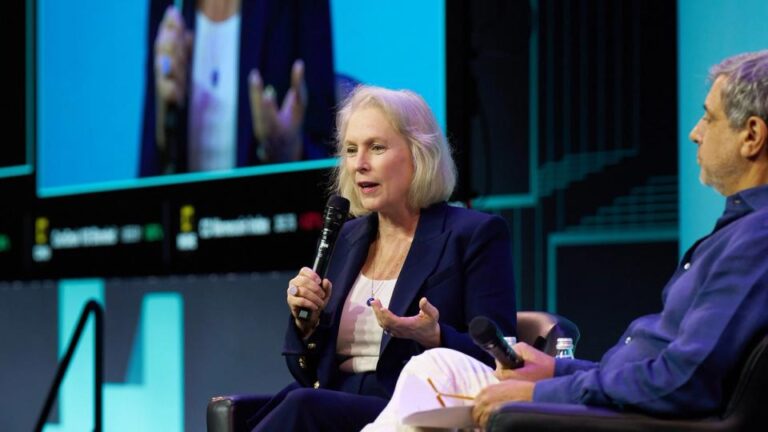
Senator Kirsten Gillibrand speaking on Wednesday. Source: Cointelegraph

Although Gillibrand did not explicitly mention US President Donald Trump by name, his ties to the crypto industry, through the launch of his memecoin, his family’s crypto business World Liberty Financial, and other dealings with the industry have come under scrutiny as lawmakers consider the CLARITY Act.

Last week, senators on the banking committee announced a deal on stablecoin yield which could allow the market structure bill to advance, but did not address language on public officials’ potential conflicts of interest.

Related: Americans distrust crypto, AI as industry super PACs flood midterms, poll finds

Crypto industry leaders and advocates have been weighing in on the market structure bill since the stablecoin yield compromise was announced. Ripple CEO Brad Garlinghouse said on Tuesday that lawmakers likely needed to address the bill in the next two weeks before it became muddied by issues amid the US midterm elections.

“There’s a window of opportunity, and that’s always important that you act when you find that window of opportunity,” said Summer Mersinger, a former commissioner at the Commodity Futures Trading Commission and CEO of the Blockchain Association, in a separate panel on the market structure bill at Consensus on Wednesday.

“That doesn’t mean the window’s not going to open again. You just never know what’s going to happen in the intervening events that maybe will bring people back to this issue after August recess,” she said.

Bill awaits markup in Senate Banking Committee

As of Wednesday, the Senate Banking Committee had not rescheduled a markup on the market structure bill after postponing the event in January. At the time, Coinbase CEO Brian Armstrong said that the exchange could not support the legislation as written, leading to other crypto companies and advocates speaking out against certain provisions in the bill on decentralized finance, stablecoins and tokenized equities.

Traders on prediction markets platform Polymarket see a 65% chance of the CLARITY Act being signed into law by the end of 2026. On Kalshi, traders currently put the probabilty that the bill will become law before August at 49%.

Magazine: Guide to the top and emerging global crypto hubs: Mid-2026
Cointelegraph is committed to independent, transparent journalism. This news article is produced in accordance with Cointelegraph’s Editorial Policy and aims to provide accurate and timely information. Readers are encouraged to verify information independently.

Bitcoin’s post-quantum migration will be harder than Taproot and needs to start now, Project Eleven CEO says

0

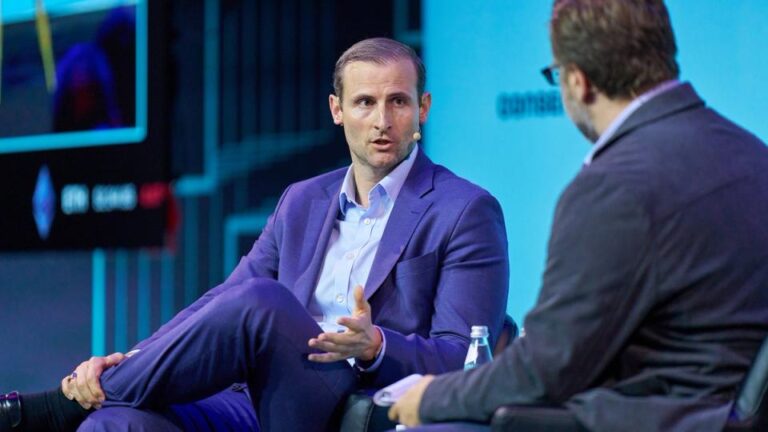
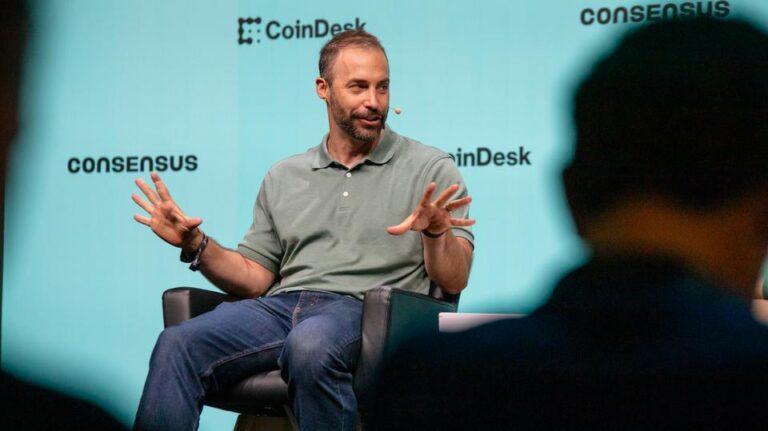
Bitcoin’s developer community should stop waiting for certainty about quantum-computing timelines and focus on getting a post-quantum signature scheme into production, Alex Pruden, CEO of Project Eleven, told CoinDesk’s Consensus Miami conference on Wednesday.

Pruden said the asymmetry between acting now and waiting favors action.

“We added some new cryptography, we kind of built in this optionality, it turns out we didn’t need quite yet, but at least we have it,” he said, describing the worst case of moving early.

The worst case of moving late is far worse: a sufficiently capable quantum computer could derive private keys from any exposed public key using Shor’s algorithm, the 1994 algorithm that remains the canonical example of what a quantum machine can do that a classical one cannot.

Pruden valued the asset at stake at roughly $2.3 trillion.

“In a very real sense, someone with a sufficiently large and capable quantum computer kind of owns everyone’s digital assets or bitcoin for the public key that they can see,” Pruden said.

The path forward, Pruden said, is to introduce a new signature scheme into Bitcoin that does not rely on the classical math underlying the elliptic-curve digital signature algorithm, or ECDSA, it uses today.

The National Institute of Standards and Technology has standardized post-quantum schemes based on hash functions and lattices, he said, and Bitcoin community discussion has trended toward the hash-based option. BIP-360, proposed last year, laid groundwork for adding a quantum-resistant Taproot output type, and Blockstream has deployed a hash-based signature scheme on its Liquid Network.

“Moving stuff out of just research into production is, I think, actually what we need to focus on,” Pruden said. “Let’s focus on the D of R&D.”

The migration will be substantially harder than the Taproot upgrade, Pruden warned.

“Taproot took five years, but that’s not even really the entire challenge that this will take.” Where Taproot was opt-in and most users never bothered migrating, every bitcoin holder and every wallet, exchange and institution that touches the asset will need to participate in a post-quantum migration.

Pruden said the timing risk is severe: if a quantum computer arrives before users have migrated, an attacker could front-run pending transactions within a single block time, paying a higher fee to capture funds whose private keys it has just derived.

Pressed on the unresolved debate over what to do with bitcoin sitting in dormant, quantum-vulnerable addresses, Pruden urged the community to defer that fight and focus on the migration itself. Harper framed that debate as involving upward of 5 million dormant coins, including coins attributed to Satoshi Nakamoto via the so-called “Patoshi” pattern of early miner blocks.

“The question of the Satoshi coins in particular is a hard one,” Pruden said, because it puts two philosophical commitments in tension: Bitcoin’s fixed-supply ethos and its commitment to digital property rights. Asked for his personal lean, Pruden said the dormant coins could potentially be “recycle[d] back into the end of the supply curve” to extend Bitcoin’s mining-incentive runway after the block subsidy runs out.

“If you put me on the hot seat, that’s probably what I would say,” Pruden said. “So I guess overall would be the confiscation side. But again, I think ultimately, the community is going to decide. The institutions and the market are going to decide.”

On whether Bitcoin Core developers are taking the threat seriously, Pruden said the answer is mixed. “Core is not a monolithic entity. So I think there are definitely [some] in Core that are taking it seriously. I think there are some people that have the opinion” that quantum computers will never arrive. He pointed to the broader scientific community as a counterweight: “The majority of physicists out there, if you ask them this, they’ll say, yes, it will be a thing. And by the way, many of them believe that the timelines are accelerating.”

The same physics that makes quantum computers a threat to existing cryptography may also seed the next generation of cryptographic primitives, he said, citing key-exchange protocols based on quantum entanglement and certified-randomness work that won the Turing Award last year.

ekko Launches the Nature Footprint, Enabling Payment Providers to Embed Environmental Impact Insights and Action Into Everyday Spending

0

WHY THIS MATTERS: The financial services industry is in the midst of a pivot from voluntary environmental, social, and governance (ESG) reporting to mandatory, granular data disclosure. For consumers, this shift is manifesting through deeper integration of sustainability metrics into day-to-day services. This announcement is significant because it elevates the conversation beyond simple carbon tracking, which has become a baseline offering. By launching a real-time biodiversity metric, ekko is demonstrating a critical advancement in sustainable finance. This tool represents a powerful application of embedded finance, bringing sophisticated environmental impact data directly into the transactional flow. It allows banks and payment processors to offer customers a tangible, immediate feedback loop on their spending choices, forging deeper loyalty while simultaneously preparing the payments ecosystem for a future where nature-related risk is a quantifiable factor for every transaction. This moves ESG from a back-office compliance issue to a front-end customer proposition, offering a new competitive advantage in a crowded market.

ekko, a mission-led fintech platform enabling banks, payment providers, and merchants to embed positive environmental action into everyday purchases, today announces the launch of its world-first solution, the Nature Footprint. 

The Nature Footprint is ekko’s real-time biodiversity metric, embedded directly into the payment experience. Through integration with payment providers and financial institutions, it enables consumers to see how their everyday spending impacts the natural world. This helps to raise awareness and educate consumers, enabling them to make more informed and sustainable choices. 

ekko’s Nature Footprint is the first to bring biodiversity impact to the point of payment. It translates complex biodiversity modelling into a clear, real-time metric that shows consumers how their spending affects the living natural world – from habitat loss and land use to pollution – complementing their existing carbon footprinting solution to give consumers a more holistic view of environmental impact.   

Beyond education, the Nature Footprint enables payment providers to offer consumers the option to take action at checkout, such as rounding up purchases to contribute to vetted environmental projects. Working with partners across the payments ecosystem, ekko aims to channel $1 billion USD into sustainability projects worldwide by the end of 2030.     

“Small steps can create monumental change. We know that 80% of consumers want to live more sustainably, but until now they haven’t had a tangible picture of the environmental impact of their everyday purchases. This is where the Nature Footprint will turn the tide,” comments Oli Cook, CEO and Co-Founder of ekko. 

“With 1 trillion purchases happening every year, every 1% of those contributing to meaningful environmental projects can unlock extraordinary impact. By partnering with payment providers, banks, and merchants to embed nature education and action into day-to-day spending, we can turn everyday activities into powerful forces for change. For our commercial partners, this creates an opportunity to deepen customer engagement and retention, stand out in a crowded market, and strengthen their relevance with increasingly values-driven customers.”

The Nature Footprint is a spend-based indication calculated using transaction amounts, merchant category codes, country of purchase, and a life-cycle assessment using ekko’s proprietary methodology, developed alongside expert-driven environmental and social sustainability consultancy, Nature Positive. It draws on peer-reviewed, internationally recognised data sources including EXIOBASE, GLOBIO, AWARE water stress indicators, and biodiversity impact indicators via CDC Biodiversité’s Global Biodiversity Score.  

The indicative footprint is then translated into a relatable area of nature affected, making it easier for consumers to understand – such as the size of a football pitch or a parking space.

“The Nature Footprint turns complex data into something people can actually see and feel. We know consumers want to live more sustainably. Now they have a real-time window into how their everyday spending affects not only climate but the natural world, and a simple way to act on it. The combined action over many millions of payments has an incredible power to transform financial transactions moving forward,” comments Majda Dabaghi, Chief Sustainability Officer at ekko. 

“It is built on the same scientific foundations used by institutional biodiversity analysts, but made accessible through the banking and payment experiences people already use every day. We are helping to build the infrastructure for an economy that takes into account not only the financial cost, but also the environmental one – and we make it possible for everyone, everywhere, to do something about it,” she concludes. 

FF NEWS TAKE: This product decisively moves the needle in the sustainable finance space by giving consumers the first practical tool to measure their direct, real-time impact on the natural world. Previously, biodiversity was too abstract for the point-of-sale experience. The key challenge now shifts from what is measured to who adopts it. We are watching for partnerships with Tier 1 financial institutions to validate the methodology and drive mass consumer adoption. The future of payments is inherently linked to impact; this is infrastructure for that reality.

White House targets July 4 for Clarity Act passage, says crypto adviser Patrick Witt

0

The White House is aiming for July 4 for Congress to pass the Digital Asset Market Clarity Act, Patrick Witt, executive director of the President’s Council of Advisors for Digital Assets, told CoinDesk’s Consensus Miami conference on Wednesday.

“We’re targeting July 4th. I think that would be a tremendous birthday present for America, celebrating our 250th,” Witt said. The mechanics, according to Witt, are: Senate Banking Committee markup this month, four working Senate weeks in June for floor passage and enough runway for a U.S. House of Representatives vote before the Independence Day deadline.

That timeline runs ahead of the prediction Sen. Kirsten Gillibrand shared on the same stage earlier in the day, when the New York Democrat predicted Clarity would reach the president’s desk by the first week of August.

“There’s not a lot of slack left in the rope right now,” Witt said. “But it is an achievable timeline.”

The path to markup opened when Sen. Thom Tillis (R-NC) and Sen. Angela Alsobrooks (D-MD) released a compromise on the bill’s stablecoin-yield provisions in early May, banning bank-deposit-equivalent yield on stablecoins while leaving room for rewards tied to spending. Witt said the White House convened banks and crypto firms to fashion the language, then handed it to the senators, who ran their own process and arrived at a text both sides found equally unsatisfying.

“Crypto is unhappy, banks are unhappy, but they’re both about equally unhappy,” Witt said. “And so we know that we got the right compromise.” Witt considered that the stablecoin-yield issue “is closed.”

The White House is also closing in on a deal on the conflict-of-interest provision that has divided Democrats and the administration. Witt said the negotiating posture is to accept rules that apply “across the board, from the president all the way down to the brand new intern on Capitol Hill,” but reject anything that singles out a particular office or officeholder. “We’re not going to allow targeting of anyone’s family, any one particular politician,” he said. “I’m optimistic that we’re going to be able to close that out.”

Speaking on what happens if Clarity slips past 2026, Witt said “If we’re not setting the standard, if we’re not writing the rules, then we are going to be a rule follower, and we’re going to be following somebody else’s rulebook on this. And God forbid it’s China that’s ultimately writing those rules.”

U.S. leadership in global capital markets, he added, is one of the things that “underwrite American hegemony.”

Witt also discussed the Guiding and Establishing National Innovation for U.S. Stablecoins (GENIUS) Act, the stablecoin-issuer law passed last year, where rulemaking by the Treasury Department, the Office of the Comptroller of the Currency, the Federal Deposit Insurance Corp. and other agencies is closing in on a one-year July deadline.

“These are complicated issues. They require following the Administrative Procedures Act, soliciting comments. And we received a flood of comments,” Witt said. The law, he added, exemplifies “the efficient frontier of regulation: just enough to allow an industry to flourish… but not so much that you overly burden an innovation into irrelevance.”

Dominance of Tether and Circle is a net bad for stablecoins, says Bridge executive

0

Miami Beach — The stablecoin universe, dominated by Tether and Circle, hampers competition that could lead to better product-market fit for some important use cases, according to Ben O’Neill, Bridge’s head of money movement.

“I think it’s a net bad for the growth of stablecoins as a whole, because you have two counterparties that have pros and cons to what they’ve built, and the design choices they’ve made. But they don’t work for every use case,” O’Neill said on a panel about stablecoin growth at Consensus Miami.

Tether’s USDT, with its gargantuan market capitalization of approximately $189.5 billion, and Circle’s USDC, which has grown to around $71 billion, each emerged at different generational eras in the crypto evolution.

Tether, launched in 2014 as Realcoin, won the Chinese export trade, O’Neill said, and built this shadow economy of dollars that people can use without the U.S. financial system. Circle, launched in association with Coinbase in 2018, sought to do the exact opposite: a U.S.-regulated stablecoin, which later leaned hard into decentralized finance (DeFi).

For O’Neill, the perspective of a large payments firm, such as Bridge-owner Stripe, illustrates the shortcomings of the two dollar-pegged token giants.

“As a payments company, I need certainty on how things are going to work,” he said. “So with Tether, they say we’ll burn for 10 bips, which is crazy expensive for a payments company, or you can trade on the open market, which means I have no certainty.”

“For Circle, their whole business is AUM, and they keep kind of notching up those burn fees. So again, if I’m someone like Visa, and I want to do trillions of dollars of card settlement and stablecoins, I’m burning a bunch of USDC, and that’s gonna be a net bad,” O’Neill said.

The solution, “which needs to come pretty quickly over the next couple of years,” is more stablecoins built for specific use cases, so they can be optimized for those use cases. The other part is the rise of the clearing house, “a sexy topic for founders and VCs” to make it “as efficient as possible swapping between stablecoins,” he added.

Closing out his argument, O’Neill said, “You need more competition, otherwise [Tether and Circle] are going to just keep upping the fees. They’re not gonna share the yield. They’re gonna disincentivize you from burning it. They’re gonna make it harder and harder to make it feel like money at each turn.”

Crypto bill won’t move without a ban on officials’ industry ties, says U.S. Senator Gillibrand

0

MIAMI — The long-awaited legislation to establish U.S. regulations for the crypto markets won’t survive the Senate if it doesn’t include a contentious ethics provision that bans senior government officials from personal interests in the industry, said U.S. Senator Kirsten Gillibrand.

“There will be no one voting for this bill if we don’t have an ethics provision,” Gillibrand, a New York Democrat who has been engaged in bipartisan crypto legislation for years, said Wednesday at Consensus Miami 2026. The inclusion of that section — aimed largely at the business interests of President Donald Trump — remains one of the few major sticking points on the bill negotiation, which is coming to a head this month.

“We cannot allow members of Congress, senior administration officials, presidents or vice presidents to get rich off of these industries because of their insider status,” Gillibrand said. “It is the worst form of pay-for-play; it is the worst form of campaign finance violations; it’s a violation of the Constitution.”

The Digital Asset Market Clarity Act — the crypto industry’s top policy aim in Washington — is awaiting a necessary Senate Banking Committee hearing in order to advance to the Senate floor for a vote.

Gillibrand said the ethics negotiation needs to be resolved in the next week to get a bipartisan approval in the hearing, which is expected as soon as next week. She said the negotiators are also working on consumer protection and illicit finance elements. So far on the ethics provision, White House officials have denied that Trump’s business interests represent a conflict, and they’ve said they won’t tolerate a bill that targets him.

“We cannot let greed and corruption in Washington tear this industry down, and without that provision, that’s exactly what will happen,” Gillibrand argued.

The window for legislative action is narrowing considerably, and the needed Senate bandwidth to move the legislation will be at a premium, with about 10 weeks of Senate calendar time remaining before Congress pivots to the midterm elections.

Gillibrand predicted a final vote could happen in the first week of August, “if we’re lucky.” That would mark the last chance before Congress’ summer break.

However, in another Consensus panel, Summer Mersinger, the CEO of the Blockchain Association who served on the Commodity Futures Trading Commission, suggested a legislative window may never permanently close.

“There’s a window of opportunity, and that’s always important that you, you act when you find that window of opportunity,” she said. “But I always say that that doesn’t mean the window’s not going to open again.”

Read More: Ripple CEO Brad Garlinghouse says Clarity better than chaos as Senate hits key moment

OpenAI Launches Training Spec to Boost Large-Scale AI

0

OpenAI released Multipath Reliable Connection, an open source specification for large-scale AI training networks developed alongside AMD, Broadcom, Intel, Microsoft and Nvidia.

The new spec is designed to improve GPU performance and resilience in large training clusters, responding to growing compute demands that require vast amounts of high-performance GPUs.

Using MRC, engineers can train AI models on supercomputers with more reliability and speed than ever before. In particular, OpenAI said it developed MRC to address two core challenges: reducing avoidable network congestion and minimizing the impact of inevitable hardware failures. 

The protocol does this by spreading individual data transfers across hundreds of paths, meaning the data can be rerouted depending on congestion or failures in milliseconds.

“MRC helps us keep GPUs moving together through congestion, link failures, and maintenance events that would previously have disrupted training,” OpenAI said in a May 5 blog post. “At meaningful scale, that reliability and efficiency is not a nice-to-have; it is part of what makes synchronous frontier model training possible.”

Related:SAP Plans to Turn Spreadsheet AI Startup Into Top Frontier Lab

The launch is expected to feed into the company’s Stargate project, a $500B effort to build out AI infrastructure in the U.S.

“To efficiently use compute at the scale of Stargate, we need to drastically reduce complexity in every layer of the stack — including network design,” the vendor said

OpenAI has already rolled out MRC across the vendor’s supercomputers, including systems built with Oracle Cloud Infrastructure in Abilene, Texas, and Microsoft’s Fairwater supercomputers. 

The vendor also said it has used the technology to train multiple frontier models using hardware from Nvidia and Broadcom. 

As of today, MRC will be available under OpenAI’s Open Compute Project, for community users to deploy and tailor.

OpenAI positioned the release as part of a broader push toward shared infrastructure standards.

Bermuda pushes stablecoin payments with USDC airdrop as it courts crypto firms, regulators

0

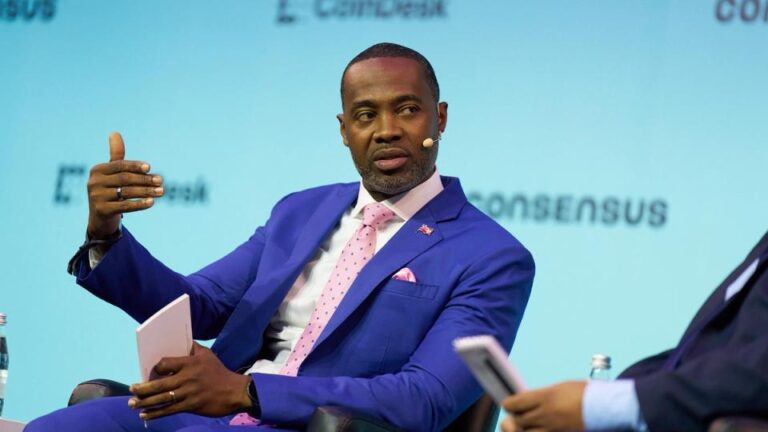
Bermuda is aiming to show an example how to move crypto into everyday commerce without breaking the financial system, Premier David Burt said onstage at Consensus Miami 2026 on Wednesday.

Burt said the tiny island on the Atlantic is expanding its “onchain economy” initiative, a push to get stablecoins into the hands of residents, merchants and local businesses. The project was first announced in January at the World Economic Forum, with stablecoin issuer Circle (CRCL) and exchange Coinbase (COIN).

The government plans another airdrop of USDC stablecoin this year, tied to next week’s Bermuda Digital Finance Forum 2026, while also onboarding merchants that can accept digital payments. Participants will receive stablecoins through wallets and can spend them with local vendors, Burt said.

“If you are a vendor and you’re accepting digital assets, but you do not have a way to use and spend those digital assets inside your economy, that presents a problem,” Burt said.

The broader goal for Bermuda is to build payment infrastructure outside traditional card networks and banking rails, he said, arguing that small businesses face high transaction fees and limited access to financial apps common in larger markets.

Coinbase Chief Legal Officer Paul Grewal, who joined Burt on stage, said Bermuda’s approach stands out because regulators and private firms are building in tandem instead of working separately.

“What’s most interesting about the Bermuda example is it is a parallel process,” Grewal said. “Government services can be accessed using payment stablecoins, while merchants and businesses are brought into the system at the same time.”

Bermuda, Burt said, has spent years building a digital asset framework through its Digital Asset Business Act. He described the island’s regulatory style as iterative and industry-facing, with the Bermuda Monetary Authority working directly with firms on issues such as staking, lending and DeFi supervision.

“You cannot regulate out failure,” Burt said. “But you can put in place the items which allow responsible innovation to happen.”

Grewal also contrasted Bermuda’s approach with the regulatory climate crypto firms faced in the U.S. over the past several years under former Securities and Exchange Commission (SEC) Chair Gary Gensler. That has changed for the better under the Trump administration, he argued.

“It is a new day here in the United States,” Grewal said, pointing to what he described as a more constructive tone from agencies under SEC Chair Paul Atkins and Commodity Futures Trading Commission (CFTC) Chair Michael Selig.

“We still have challenges, to be clear, but it’s a very different dynamic,” he said.

the Senate must act on crypto market structure legislation

0

Nine months ago, Congress passed the GENIUS Act, establishing the first federal regulatory framework for payment stablecoins. The results have been demonstrative: the stablecoin market grew 49% in 2025, reaching $306 billion by year’s end. Circle, Ripple and other digital asset companies received provisional national banking charters from the OCC. Institutional capital that had been sitting on the sidelines moved into these markets. Recruiters, who a year earlier described an industry in which “every protocol foundation was bailing to the Caymans [tradingview.com],” now report that 90% of senior crypto leadership searches are U.S.-based. Clear rules produced exactly what their advocates said they would: investment, institutional engagement and onshoring of activity that had been migrating elsewhere.

That outcome sharpens the task before the Senate Banking Committee: applying a clear framework to the broader digital asset market. The crypto market is currently worth $3.2 trillion. Nearly 70 million Americans, one in five, own crypto. This is a significant and growing market.

The GENIUS Act addressed payment stablecoins. The CLARITY Act sets the rules for everything else: registration and oversight of trading venues and intermediaries, jurisdictional lines between the SEC and CFTC, disclosure and compliance across the token lifecycle, and the protection of non-custodial technologies under U.S. law.

These are the foundational rules that determine whether the next generation of financial infrastructure gets built here in America – or elsewhere. Within the last 10 years, the number of developers in the U.S. dropped by 51%. Nearly 90% of global CEX volume is offshore. America needs foundational rules because without them, the same dynamic that preceded GENIUS would apply to the rest of the market. Trading activity, protocol development and institutional engagement in digital asset markets will continue to flow toward jurisdictions that have already provided the regulatory clarity Congress has yet to deliver. Other jurisdictions, including the EU, Singapore, and the UAE, have already enacted market structure regimes and are providing the regulatory clarity yet to be delivered.

The Senate Banking Committee, alongside offices on both sides of the aisle, has spent the better part of two years building toward this moment. Senators Tillis and Alsobrooks deserve credit for resolving the stablecoin yield question in a bipartisan manner, the single most contested provision in months of negotiations. The compromise substantially expands the scope of the prohibition framework in GENIUS across digital asset market participants. The digital assets industry made significant concessions. The resulting approach is restrictive in several respects – ultimately, the broader and most critical objective remains advancing comprehensive market structure legislation, and this agreement moves that process forward.

Nothing is perfect in this process, and legislating is complex, but it’s a result reached through the kind of sustained bipartisan engagement that serious legislation requires. Chairman Scott has managed a difficult process across deep disagreements between the banking industry and the digital asset sector, and the Committee is closer to a durable outcome than it has been at any point in that process.

The window to act is narrow. The legislative calendar leaves limited time to move a bill of this scope through committee, floor consideration and final passage. A markup in the near term is necessary to keep this effort on track and ensure there is a viable path to the President’s desk before year-end.

The CLARITY Act passed the House with 294 votes. That breadth of bipartisan support reflects genuine congressional judgment that clear rules for digital asset markets serve the public interest. The Banking Committee should schedule a markup as soon as possible. The case for moving forward has never been stronger.

The United States should finally establish the clear, durable, fit-for-purpose framework this market – and this country – needs. America has long led the world because it has embraced innovation, markets and the rule of law. Now is the time to do so again.

What Is Crypto Lending and Is It Right for You?

0

Byline: Will Jones

Over the past several years, cryptocurrency has become a pillar of modern finance. When the digitized currency first garnered such attention and prominence in early 2020, many were quick to dismiss it as little more than a passing fad aided by the unusual circumstances surrounding this time period, including COVID-19 lockdowns. However, in the years since then, while crypto’s overall value has consistently ebbed and flowed, it has remained, demonstrating a kind of resilience and longevity that many doubted it would be able to.

While it’s undeniable that the increased reliance on digital tools and platforms during the COVID lockdowns played a huge role in helping cryptocurrency break through, having spent over a decade with middling levels of success since the founding of Bitcoin in 2008, it has now long outlived that era. Like other technological innovations of the time, such as AI or even social media platforms like TikTok, cryptocurrency has remained an essential element of modern life.

To this end, as many people experience new waves of stress amidst inflation and a struggling economy, crypto lending has become an increasingly popular potential solution. In a time where making ends meet can seem infeasible, crypto lending can provide a viable alternative to traditional loan services. This only leaves one question: is crypto lending right for you?

What Is Crypto Lending?

Crypto lending is highly similar to traditional lending services, but entirely digitized and reliant solely upon cryptocurrency or digital assets. This process allows users to borrow fiat or digital assets by providing crypto as collateral (known as borrowers) or, on the other side of things, to lend out crypto to earn interest (known as lenders).

From the outset, cryptocurrency was designed to operate as a decentralized commodity, positioning it in stark opposition to traditional banking systems. After all, a large part of what inspired Satoshi Nakamoto to create the first kind of cryptocurrency back in 2008 was the US economic recession of 2007. In this way, crypto lending similarly stands in opposition to traditional lending methods through decentralized methodology, but is also offered on centralized crypto platforms, through popular types of coins such as Bitcoin, Ethereum, and stablecoins.

How Crypto Lending Works

Step-by-step process:

  • Deposit crypto assets
  • Earn interest
  • Borrow against crypto collateral

Overcollateralization is part of crypto lending that requires borrowers to deposit assets that ultimately exceed the value of the loan itself. This is done to provide a more worthwhile collateral, which protects lenders from crypto’s high volatility. 

Use Cases: Who Should Consider Crypto Lending?

  • Long-term crypto holders
  • Investors seeking passive income
  • Risk-tolerant individuals
  • Who should avoid it (beginners, risk-averse investors)

Is Crypto Lending Right for You?

Now that you have a better understanding of what crypto lending is and how it works, there are some important considerations to keep in mind that can help you determine if it is a viable solution for you. By considering your risk tolerance, your investment goals, and the overall potential volatility of crypto markets, you can take on a balanced perspective of the opportunities afforded by crypto lending, as well as the potential risks, and make a decision that is right for you.

FAQ Section

What is crypto lending in simple terms?

A way to earn interest by lending your cryptocurrency or borrowing funds using crypto as collateral.

Is crypto lending safe?

It carries risks, including market volatility and platform reliability.

How much can you earn from crypto lending?

Returns vary widely depending on the platform and asset, often higher than traditional savings.

Do you lose your crypto when lending it?

You temporarily give control to a platform, but you retain ownership unless liquidation occurs.