Home Blog Page 320

Bitcoin back above $81,000 after hot CPI print, BNB, DOGE lead majors gains

0

Bitcoin shrugged off the inflation scare almost as quickly as the print landed.

The largest cryptocurrency dropped to $79,879 in late U.S. hours Tuesday after the April Consumer Price Index came in at 3.8% year-over-year, hotter than economists had estimated, with gasoline prices doing most of the lift since the Iran war began. BTC recovered to $81,208 by Asian morning Wednesday, ending the session up 0.3% over 24 hours after trading a $1,400 range. The dip got bought aggressively.

Among the majors, BNB led with a 2.5% gain to $677, while dogecoin added 1.3% to $0.1114. Ether dropped 0.3% over 24 hours to $2,300 and is now down 3.2% on the seven-day, the laggard of the cohort. Solana slipped 0.6% to $95.52. XRP traded at $1.45, down 0.5% on the day.

The CPI print rattled traditional markets harder than crypto. The S&P 500 fell 0.2% and the Nasdaq 100 dropped 0.9%, with semiconductor stocks taking the brunt of the selling after weeks of outsized gains.

The rate-sensitive two-year Treasury yield held just under 4%, while Japan’s 20-year bond yield breached its January peak to touch the highest level since 1997 as elevated energy prices add to inflation pressure globally.

Asian equities clawed back early losses after the White House confirmed Nvidia CEO Jensen Huang would join President Donald Trump’s trip to China, lifting chipmaker futures.

The flows underneath crypto are still positive. CoinShares reported global crypto fund inflows of $858 million last week, with bitcoin products absorbing $706 million, ether $77 million, solana $48 million, and XRP $40 million.

The largest data point was the $14 million in outflows from bitcoin short positions, the biggest weekly short unwind of 2026. Money is leaving bearish bets on bitcoin even as the macro tape turns choppier, which is the kind of positioning shift that typically precedes upward grinds rather than capitulations.

FxPro’s chief market analyst Alex Kuptsikevich said the broader sentiment index has settled just below the midpoint of its range, recording readings of 47, 48 and 49 over the past three days, suggesting bears still have a slight upper hand.

Bitcoin “lost its upward momentum as it approached the 200-day moving average,” he said in a note, referring to the long-term trend line that smooths out short-term price noise.

“Although this line is trending downwards, the market has failed to break through it for the past six days. On the other hand, as the decline is quite modest, it resembles nothing more than a breather following a rally.”

CoinShares also noted that last week’s inflow surge came alongside a compromise on stablecoin yield treatment under the CLARITY Act, which the Senate Banking Committee is expected to consider next week. The regulatory progress is one of the few clean tailwinds the market has had since the Iran war began, and it is showing up in the flow data rather than the price action.

For now, bitcoin holding $81,000 after a CPI print this hot and a Treasury yield setup this tight is the kind of behaviour that suggests structural buyers are still active under the price. Whether that holds through next week’s Senate markup and the next round of macro data is the next test.
First Spot Zcash ETF? Grayscale Pushes Privacy Coin Into ETF Race

0

Trusted Editorial content, reviewed by leading industry experts and seasoned editors. Ad Disclosure

Grayscale has filed to convert its Zcash Trust into a spot exchange-traded fund, setting up a potential first for regulated exposure to a privacy coin in the U.S. ETF market. If approved and listed, the product would give investors exchange-traded access to ZEC without requiring them to custody the asset directly.

The proposed ETF would hold ZEC, the native asset of the Zcash network, and is expected to list on NYSE Arca under the ticker “ZCSH.” The filing says the trust would be renamed Grayscale Zcash Trust ETF once the registration becomes effective and the shares are listed.

Grayscale Brings Zcash Into the Spot ETF Race

The filing pushes Zcash into a category that has so far been dominated by larger, more liquid crypto assets. Spot Bitcoin ETFs and spot Ether ETFs created a template for regulated crypto exposure, but a Zcash product would test whether that structure can extend to an asset whose market identity is closely tied to privacy-preserving transactions.

Grayscale’s registration statement describes the product in direct terms. “The Trust’s purpose is to hold ‘ZEC’, which are digital assets that are created and transmitted through the operations of the peer-to-peer Zcash Network, a decentralized network of computers that operates on cryptographic protocols. The Trust’s investment objective is for the value of the Shares (based on ZEC per Share) to reflect the value of ZEC held by the Trust, as determined by reference to the Index Price, less the Trust’s expenses and other liabilities.”

The filing also stresses that the shares are not the same as holding ZEC directly. “While an investment in the Shares is not a direct investment in ZEC, the Shares are designed to provide investors with a cost-effective and convenient way to gain investment exposure to ZEC. Grayscale Investments Sponsors, LLC is the sponsor of the Trust.”

The trust is structured as a Delaware statutory trust. Grayscale Investments Sponsors, LLC is listed as sponsor, CSC Delaware Trust Company as trustee, The Bank of New York Mellon as transfer agent and administrator, Coinbase, Inc. as prime broker, and Coinbase Custody Trust Company, LLC as custodian.

Trust Held Nearly 391,104 ZEC at Quarter-End

The existing Grayscale Zcash Trust already holds a material ZEC position. In its latest quarterly filing, the trust reported 391,103.88769118 ZEC as of March 31, 2026, down from 393,522.33134026 ZEC at the end of 2025. Using the filing’s stated fair value of $254.27 per ZEC, that position was worth roughly $99.45 million at quarter-end, with Coinbase identified as the principal market for valuation purposes.

The registration statement says creations and redemptions would occur in blocks of 10,000 shares, referred to as baskets. As of Nov. 21, 2025, approximately 817.0998 ZEC were required to create one basket of 10,000 shares.

For now, the filing describes a cash-order model. Under that structure, an authorized participant deposits or receives cash, while a third-party liquidity provider sources or receives the ZEC. The trust is not currently able to process in-kind creations and redemptions with authorized participants, though NYSE Arca may later seek approval for that model.

Privacy-Coin Context Returns to the Foreground

The filing follows a notable shift in the regulatory backdrop around Zcash. The SEC concluded its review of the Zcash Foundation without recommending enforcement action or other changes, easing a long-running concern around one of the crypto market’s best-known privacy-focused networks.

The Zcash Foundation said: “We are pleased to announce that the SEC has concluded its review and informed us that it does not intend to recommend any enforcement action or other changes against Zcash Foundation regarding this matter. This outcome reflects our commitment to transparency and compliance with applicable regulatory requirements. Zcash Foundation remains focused on advancing privacy-preserving financial infrastructure for the public good.”

The SEC’s conclusion does not amount to ETF approval. It does, however, change the setting for Grayscale’s attempt to bring a privacy-coin product into a regulated public-market wrapper.

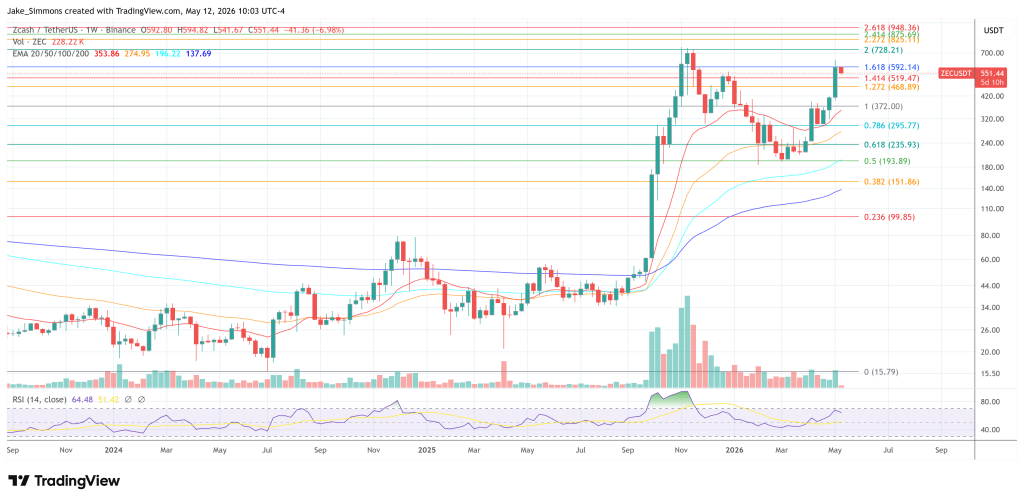
At press time, ZEC traded at $551.44.

Zcash price chart
ZEC faces the 1.618 Fib extension, 1-week chart | Source: ZECUSDT on TradingView.com

Featured image created with DALL.E, chart from TradingView.com

Editorial Process for bitcoinist is centered on delivering thoroughly researched, accurate, and unbiased content. We uphold strict sourcing standards, and each page undergoes diligent review by our team of top technology experts and seasoned editors. This process ensures the integrity, relevance, and value of our content for our readers.

Crypto analytics firm Elliptic lands $120 million as AI reshapes blockchain compliance

0

Blockchain analytics firm Elliptic said it raised $120 million in fresh funding from investors including Nasdaq Ventures and Deutsche Bank as financial institutions ramp up spending on crypto compliance and security infrastructure.

The fundraising round, led by growth equity firm One Peak, values the London-based company at $610 million, according to a Tuesday press release. The British Business Bank also participated.

The investment comes as crypto markets face a wave of security breaches and exploits that have exposed weaknesses in both decentralized finance (DeFi) protocols and centralized platforms. Hackers have stolen nearly $3 billion in crypto assets since the beginning of 2025 through smart contract exploits, phishing attacks and cross-chain bridge breaches, and regulators are pushing exchanges and banks to tighten anti-money laundering controls.

As a result, blockchain analytics firms have become critical infrastructure providers for institutions entering the digital asset industry. Elliptic’s software tracks crypto transactions across dozens of blockchains and flags wallets linked to sanctions, fraud, ransomware or illicit finance.

Banks, exchanges and government agencies use these tools to monitor transactions and comply with financial crime rules. The company said two-thirds of global crypto trading volume flows through exchanges that already use its services.

Demand for those systems has accelerated alongside the growth of stablecoins and tokenized assets, which are increasingly moving into mainstream finance. Stablecoins accounted for roughly $33 trillion in transactions last year, according to the company.

Large financial firms are also exploring tokenized securities and blockchain-based settlement systems, raising the stakes for compliance providers that can monitor activity across public blockchains in real time. At the same time, artificial intelligence (AI) tools are making attacks cheaper and faster, forcing a rethink of how crypto systems stay secure.

Elliptic said the new funding will be used to expand its AI-driven monitoring and risk analysis tools as institutional adoption of digital assets grows.

“One of the things that we will be accelerating with the funding is our agentic product roadmap,” CEO Simone Maini told CoinDesk. “What that means is building and launching agents that sit on top of Elliptic’s dataset to be able to automate a lot of what is otherwise highly manual, repetitive tasks performed by compliance analysts.

“That means those that that those precious resources can be redeployed to deep diving and investigating financial crime where they need to,” she said.

EBay rejects GameStop’s $56 billion bid as bitcoin exposure back in focus

0

Shopping giant eBay has rejected video game retailer GameStop’s ambitious $56 billion takeover offer, leaving the latter to decide whether it wants to walk away, raise the bid or take the fight directly to shareholders.

EBay’s board called the half-cash, half-stock offer “neither credible nor attractive” on Tuesday, per Reuters, citing doubts around financing and arguing the company is better positioned under its current management. The rejection was widely expected. EBay has traded well below GameStop’s $125-per-share bid since the offer surfaced, a sign investors were not convinced the deal could close.

That puts GameStop’s bitcoin position back in the conversation, as CoinDesk reported earlier this month.

The cultish firm holds roughly $368 million worth of bitcoin exposure via a covered-call options strategy. It shifted nearly all of its 4,709 BTC to institutional brokerage Coinbase Prime, as a filing showed in March, turning the position into a receivable rather than directly held bitcoin.

GameStop’s offer was built around $9.4 billion of cash and liquid investments, plus up to $20 billion in debt financing from TD Bank. But that financing is contingent on the combined company maintaining an investment-grade rating, and Moody’s has already warned the deal would be credit negative for eBay. Raising the offer or going hostile would likely make the financing math more challenging.

Cohen has previously framed the eBay deal as “way more compelling than bitcoin,” leaving open the question of whether GameStop’s BTC position could be unwound if more cash is needed.

Selling it would not fund the deal by itself, but it is one of the few discretionary assets GameStop can point to as it tries to convince investors the bid is real.

The market remains skeptical, however. EBay shares slipped about 1% to $107 before the bell Tuesday, still far below the offer price, while GameStop fell 4%.

The deal previously drew pushback from parts of GameStop’s own investor base.

Michael Burry, the investor made famous by The Big Short, sold his stake after the bid and warned that buying eBay could saddle GameStop with debt and dilute shareholders.

Adfin Raises $18M Series A from Index Ventures for Automated Business Finance

0

WHY THIS MATTERS

Adfin’s $18 million Series A funding on May 11, 2026, signals a definitive shift from passive financial automation to “agentic” execution. In the UK, where late payments drain the working capital of 63% of SMEs, Adfin has already proven its model: its customers see a late-payment rate of just 9%, roughly seven times better than the national average. By raising over $30 million in less than two years and securing backing from Index Ventures, Adfin is moving beyond mere reminders into an era of “money that moves itself.”

The platform’s core innovation lies in its proprietary payment infrastructure coupled with agentic AI. Unlike standard “autopay” features, Adfin’s agents act as autonomous negotiators and managers, deciding the optimal course of action to secure payments while preserving the delicate relationship between a business and its clients. For the professional services firms, accountants, and SMEs that Adfin serves, this funding allows for the expansion into end-to-end cashflow management, turning a business’s “bloodstream”—its money movement—into a high-speed, self-governing asset.

Adfin, the London-based fintech, has raised $18 million in Series A funding to build the agentic money movement platform: starting by helping businesses getting paid on time, and ending with money that moves itself.

The funding round was led by Index Ventures, with participation from Visionaries Club and new investors Stéphane Kurgan (former COO of King) and Andrey Khusid (founder of Miro). The investment brings Adfin’s total funding to over $30 million in less than two years and comes as Adfin was named the third fastest-growing technology company in Europe, and the fastest-growing UK company by Scaling Europe. 

In the UK alone, almost two-thirds (63%) of invoices sent by SMEs are paid late. This strains working capital, slows growth, and puts jobs at risk. Adfin gives SMEs the tools to get paid on time, uniquely coupling proprietary new payment infrastructure with agentic AI to decide the best course of action for each client and automate the tedious tasks that were preventing businesses doing what they do best: managing client relationships. This infrastructure has already delivered outstanding results for Adfin customers. Today, they see only 9% of their invoices paid late: nearly 7x better than the 63% figure for the UK as a whole.

Getting paid is just the start. With the Series A, Adfin plans to expand the Adfin product into end-to-end cashflow management, step up hiring across engineering and sales, and prepare for international expansion.

Tom Pope, Adfin Co-founder and CEO said: “Adfin is building the agentic finance platform for money movement: automating the workflows finance teams use to get paid, manage their money, and, in time, much more. And we’re doing it the way our customers keep telling us they want: safe, auditable, trackable, with humans firmly in control. By owning both the underlying financial infrastructure and the agentic workflows on top, we’ll let finance teams deploy agents in a way nobody else can. 

Why does this matter? If you’re getting paid faster and optimising how you manage cash, you’re building a better business. Money movement isn’t admin, it’s the bloodstream of every company. We believe this so strongly that we’ve rewritten our mission around it: Adfin exists to help the world build better businesses.”

Liam McHugh, Director at Steve Pye & Co, a Norwich-based accounting practice said: “Since using Adfin we’ve seen nearly a 3x reduction in the number of our invoices that are paid late. It’s had a meaningful impact on our cashflow. It also means our team no longer has to spend time chasing invoices, and instead can focus on serving our customers and growing our business.” 

Julia André, Partner at Index Ventures said, “Index backs founders who have the rare ability to obsess over a problem and build category-defining businesses. We see that same pattern in Tom and Ciprian. We backed them at pre-seed and seed and we’re tripling down, because their results speak for themselves.”

FF NEWS TAKE

Adfin is effectively building the “Central Nervous System” for business finance. By naming it an “agentic money movement platform,” Tom Pope and Ciprian Diaconasu are setting a new standard where finance teams stop being “chasers” and start being “overseers.” Index Ventures’ decision to “triple down” on the team reflects the rarity of a fintech that delivers such high-impact operational results so early in its lifecycle. In a 2026 market where “Agentic Payments” is becoming the industry’s buzziest category, Adfin has a significant head start by owning both the underlying payment rails and the AI decision layer.

However, the leap from “getting paid” to “money that moves itself” is an immense technical and regulatory challenge. As Adfin scales internationally, it must navigate a fragmented global landscape of real-time payment schemes and varying AI governance standards. The inclusion of visionary investors like Andrey Khusid (Miro) suggests that Adfin is prioritizing the “user-centricity” of its agents. If Adfin can prove that its AI agents can handle complex, multi-currency treasury tasks with the same 99% accuracy it brings to simple invoicing, it will likely become the definitive operating system for the world’s mid-market businesses.

The battle for the digital euro is heating up as central bankers clash over how to take on Tether

0

France’s central bank deputy governor called Tuesday for the “mobilization of all relevant European players, public and private,” to develop tokenized money.

Beau’s comments are in stark contrast with European Central Bank (ECB) President Christine Lagarde’s recent speech in which she said that “the case for promoting euro-denominated stablecoins is far weaker than it appears.”

While Lagarde described the $310 billion privately-issued stablecoin market, currently dominated by Tether’s USDT and Circle’s USDC, as instruments that “risk amplifying the very vulnerabilities we are trying to overcome,” Beau told CoinDesk that private sector solutions are necessary for the region’s economic development.

The different views, however, reveal a growing concern in Europe over the “digital dollarization.” With a stablecoin sector projected to rise to the trillions of dollars in the coming years, a lack of euro-pegged currencies could force European capital into dollar-backed assets, potentially eroding the euro’s global influence and monetary sovereignty.

“To ensure a sound development of tokenized finance in Europe, its payment and settlement asset pillar should be in euro and build on the solid foundation of our current two-tier monetary system,” Beau said in an interview with CoinDesk.

The central banker outlined a “triple objective” for the region, which requires the European Union (EU) to adapt central bank money services, develop “pan-European solutions in tokenized private money issued by regulated financial institutions,” and strengthen the bloc’s Markets in Crypto-Assets Regulation (MiCA).

Beau’s stance aligns with Qivalis

Beau’s stance aligns with Qivalis, a group of 12 major European banks, including ING, BBVA, and BNP Paribas, which plans to launch a private digital euro later this year.

Qivalis CEO Jan-Oliver Sell recently told CoinDesk that without a liquid onchain euro, “the only alternative is the U.S. dollar,” which he described as a “risk to Europe’s financial and digital sovereignty.”

Lagarde agrees with the need for digital asset alternatives to dollar-pegged stablecoins, warning that USDT and USDC pose “financial stability risks” for Europe and could “transmit stress to the underlying asset markets during periods of turmoil.”

However, while Beau advocates for immediate private-sector mobilization to capture market share, Lagarde favors a central bank digital euro, which in previous statements she suggested would be ready by 2029.

Beau noted that the Eurosystem is already moving to provide native settlement options. “A first deliverable will become available by the end of this year, with the opening of our wholesale central bank money service in tokenized form,” he said, referencing projects such as Pontes.

The opposing views between Lagarde and Beau come as U.S. dollar-pegged tokens account for 98% of the stablecoin market.

While Lagarde argues that stablecoins, “do not confer the unconditional finality that central money does,” Beau maintains that public and private efforts “should complement and support each other” to ensure the euro remains a viable settlement instrument in an increasingly tokenized global economy.

Senate Confirms Bitcoin-Friendly Kevin Warsh To Fed Board, Clearing Path To Chairmanship

0

President Donald Trump’s push to install Kevin Warsh as the next chair of the Federal Reserve moved closer to completion Tuesday after the Senate confirmed him to the Fed’s Board of Governors, a step that clears the path for a final vote on the chairmanship later this week.

The Senate approved Warsh in a 51-45 vote that fell along party lines, with Sen. John Fetterman joining Republicans in support of the nominee. If confirmed as chair, Warsh would replace Jerome Powell, whose term leading the central bank ends Friday.

Warsh’s rise has drawn attention across financial markets and the Bitcoin industry because of his public support for bitcoin and his ties to crypto-related firms. 

Warsh’s consideration of bitcoin

Unlike past Fed leaders who treated digital assets with skepticism, Warsh has described bitcoin as “an important asset” and “a very good policeman for policy,” arguing that its price can reflect confidence in the Federal Reserve’s handling of inflation and monetary policy.

“Bitcoin doesn’t trouble me,” Warsh said during a Hoover Institution event last year, where he framed the asset as a signal of monetary credibility rather than a threat to the U.S. dollar.

His confirmation follows financial disclosures showing Warsh held an equity stake in Flashnet, a Bitcoin payments startup focused on lightning-style transaction infrastructure for merchants and fintech companies. The disclosure marked one of the clearest links yet between a potential Federal Reserve chair and a company tied to Bitcoin adoption.

Warsh has also maintained ties to the crypto sector through advisory work and investments connected to digital asset firms, including crypto index manager Bitwise and stablecoin project Basis.

At the same time, Warsh remains known as an inflation hawk. During his earlier tenure as a Fed governor from 2006 to 2011, he warned about inflation risks and criticized loose monetary policy following the financial crisis. 

Recent comments calling for “regime change” at the Fed and signaling openness to lower interest rates have created debate among investors over how he would balance inflation concerns with pressure from the White House.

Markets now face a Fed transition during a period of renewed inflation pressure, rising geopolitical tensions and uncertainty around future rate policy. 

Bitcoin traders and crypto investors are watching closely to see whether Warsh’s views on digital assets translate into a shift in tone from the nation’s most powerful financial institution.

Kraken Launches Flexline, Crypto-Backed Lending Product for Builders and Traders

0

Kraken introduced Flexline, a lending product that accepts cryptocurrency as collateral at 10–25% APR fixed rates, targeting crypto-native businesses and high-net-worth individuals excluded from traditional banking.

Kraken announced Flexline, a lending product designed for crypto holders who lack access to traditional credit markets. The service offers fixed APR rates between 10–25% and accepts cryptocurrency as collateral—a treatment traditional lenders do not provide. Flexline targets two use cases: working capital for operational needs and proof-of-funds verification for significant transactions.

Crypto-native businesses and high-net-worth individuals often hold substantial digital asset balances but cannot leverage them with conventional lenders, which do not recognize crypto as collateral. Flexline addresses this gap by structuring loan terms that reflect how cryptocurrency balance sheets actually function, providing speed and collateral treatment unavailable in traditional finance.

Sources: Kraken Blog | Kraken Flexline Product Page

This article was generated automatically by The Defiant’s AI news system from publicly available sources.

When Process Breaks Down, Fraud Finds a Way: Through Invoices, Expenses or Both!

0

The cost of this fraud? 1% of the subsidiary’s annual turnover (over 8 years). It could have been halted before it got started by flagging bank deposits that do not have a corresponding accounting entry.

What is Invoices/Expenses Fraud & How Does it Work?

This type of invoice/expenses fraud is a structural risk that is often underestimated. The duration of exposure is as decisive as the unit amount embezzled, which in this instance was carried out over eight financial years and cost 1% of the subsidiary’s annual turnover. In this case, the mechanism was simple but invisible to the naked eye: a customer payment deposited in the bank was never recorded in the accounts, while a fictitious expense report, validated internally, reimbursed the same amount to the accountant.

In this case study we’re entering accounting mechanics. The subsidiary had a very small accounting team, and the chief accountant had the ability to process payments himself. The Group also used an external service provider to manage expense reports.

The issue with such providers is that their role is generally limited to checking that receipts exist. They don’t know the company’s internal rules, nor can they challenge the validity or appropriateness of the expenses submitted.

Eight years of fraudulent activity

Here’s what happened: several clients were paying their invoices normally, but these payments were not recorded in the accounting system. At the same time, the chief accountant was submitting expense reports, which were approved by the external provider. He then reimbursed himself using the funds received from clients’ payments that had never been booked. The amounts appeared on the bank statements but not in the accounts.

During each monthly close, adjusting entries were posted to artificially record the client payments, then reversed the following month. This allowed the fraud to keep rolling smoothly from one month to the next. And it went on for eight years.

Why wasn’t it detected sooner?

Fraud can rumble on for many months, if not years before it’s detected. Some of the issues in this
case were:

  • There was no proper internal process to validate expense reports.
  • Bank account access was extremely restricted, and the chief accountant could authorise payments himself.
  • Bank reconciliations were performed very infrequently — and unsurprisingly, by the chief accountant himself.
  • No independent review of the accounts receivable ledger was ever performed: not by controlling, not by internal control teams, not by internal audit.
  • With all these weaknesses combined, the fraud mechanism could operate comfortably and remain unnoticed for many years.
What can organisations do to prevent this type of fraud?

One of the issues with this type of fraud is the length of time it can go on for. The company is being systematically weakened by poor processes; no expense report, restricted access to bank accounts and infrequent reconciliation. This can be caused by siloisation; the concentration of responsibility in one person. The opportunity for fraud is revealed and rationalisation follows because of a lack of oversight.

Two Ways to Prevent Invoice/Expenses Fraud:

  • Improve validation processes with proper verification
    At the heart of this fraud were two flawed manual processes: the recording of customer receipts, which was often delayed or handled inconsistently, and the validation of expense reports, which were approved by management without verification of supporting documents or reconciliation with other flows. By automating the monitoring of bank reconciliations and integrating specific controls on expense reports, the organisation could have closed both of these windows of opportunity simultaneously.
  • Making fraud untenable through traceability and transparency
    For eight years, the chief accountant was able to maintain this fraud because he was the only one with a complete view of the flows. To avoid this, organisations can use advanced technical solutions to redistribute visibility via a fully collaborative platform. In this environment, recurring monthly closing manipulations would be immediately flagged as points of attention, such as over-the-counter reversals on the 1st of the month to hide cash receipts.
How to Spot and Prevent Invoice/Expenses Fraud
  • Monitoring reversal patterns and closing manual adjustments
    Improve analyses of the recurrence and logic of various manual adjustments. A systematic reversal on the 1st of the following month, applied to the same amounts and the same accounts, may constitute an accounting anomaly that a platform immediately flags as a priority alert. This type of monthly closing manipulation should be one of the indicators covered by the organisation’s controls.
  • Cross-checks on expense reports Organisations can build customised control programmes for expense reports. For example they can choose to identify validators who systematically approve the same people or who validate their own expense reports. Analyses of the descriptions of these entries can sometimes be very useful. We have found that attempts to conceal fraud are often what make it most obvious to detect.
Stop it; before it starts

Sharing approval processes, and more generally, ensuring a proper segregation of duties whenever there is a cash output, can deter fraud. A sense of impunity is created when processes sit in silos and critical changes depend on a single individual. Strengthening controls and connecting finance, procurement and audit data flows reduces that space, where fraud thrives. With structured workflows, shared visibility and automated monitoring, fraudulent actions become detectable early and therefore far riskier for anyone tempted to act.

It’s time to improve your organisation’s controls and remove isolated decision points, to reduce both the opportunity and the rationalisation that make fraud possible. Don’t let fraud run unnoticed in your organisation for years.

  • As the UK Country Manager for SixthFin and a leader at BM&A, Olivier Cornet leverages over 20 years of B2B SaaS expertise to simplify complex regulatory landscapes like UK SOX and ECCTA. He specializes in RegTech innovation, helping international organizations transform compliance requirements into drivers of operational performance.

    View all posts


    UK Country Manager, SixthFin

Square Crosses 1 Million Bitcoin-Enabled Merchants As Real-World Adoption Continues To Grow

0

Block Inc.’s (XYZ) Square has crossed a threshold of roughly 1 million merchants now enabled to accept Bitcoin payments.

The figure, cited by a member of Block’s team, reflects a wave of auto-enrollment that began March 30, when Square automatically switched on BTC payments by default for eligible U.S. sellers.

At its peak pace, a new business was activating the feature every eight seconds. The rollout is powered by the Lightning Network, enabling near-instant settlement while merchants receive U.S. dollars by default, removing currency risk from the equation.

In other words, customers can pay in Bitcoin via Lightning while merchants still receive USD settlements, with the system handling conversion in the background and allowing sellers to opt out if needed.

Bitcoin as everyday money

At the Bitcoin Conference in Las Vegas, Block outlined an expanded push to make bitcoin usable as everyday money rather than simply a long-term investment. Speaking on the Nakamoto Stage, Bitcoin Product Lead Miles Suter said BTC “must circulate, not just sit still,” arguing that the cryptocurrency loses its transformational value if it does not function as peer-to-peer cash.

Suter highlighted Block’s growing adoption metrics, revealing at the time that there were more than 800,000 Square merchants who now have BTC payments auto-enrollment enabled. This number seems to be above According to Suter, a new business activates the feature every eight seconds. The company is also rolling out a tap-to-pay BTC feature using NFC hardware and the Lightning Network, eliminating QR codes and offering zero processing fees through 2026.

The company’s broader strategy centers on integrating bitcoin across its ecosystem. Cash App users can now automatically convert peer-to-peer payments into BTC, earn 5% Bitcoin Back rewards at Square merchants, and withdraw up to $10,000 per day and $25,000 per week. 

Block also introduced an updated Bitkey hardware wallet featuring a touchscreen and 2-of-3 multisig security model designed to simplify self-custody.

Alongside the product announcements, Block released its Q1 2026 proof-of-reserves report showing holdings of 28,355.05 BTC worth roughly $2.2 billion.