Wells Fargo reported larger positions in Ether exchange-traded funds in the first quarter while reshuffling its Bitcoin ETF holdings across several products, according to its latest Securities and Exchange Commission filing.
The bank said it raised its holdings in Ether (ETH) ETFs, including BlackRock’s iShares Ethereum Trust ETF (ETHA) and the Bitwise Ethereum ETF (ETHW), according to its latest Form 13F filing released on Monday.
ETHA rose 63.5% from about 672,600 shares in Q4 2025 to roughly 1.1 million shares in Q1 2026, while ETHW increased by 37% from about 186,800 to more than 257,000 shares, showing a broad-based increase across Ether-linked funds.
Bitcoin (BTC) ETF exposure, by contrast, showed a more mixed pattern: positions in the iShares Bitcoin Trust ETF (IBIT) were slightly reduced, while Bitwise Bitcoin ETF Trust (BITB) and Grayscale Bitcoin Mini Trust ETF (BTC) holdings increased by roughly 24% and 41%, respectively.
The filing suggests Wells Fargo reported larger Ether ETF positions at quarter-end, even as its Bitcoin ETF exposure was more mixed.
Accumulation amid ETH price dip
Wells Fargo’s Ether ETF accumulation came during a period of weakening spot prices. According to CoinGlass data, Ethereum posted two consecutive quarterly declines, falling around 28% in Q4 2025 and 29% in Q1 2026.
Over the same period, spot Ether ETFs saw sustained outflows, totaling roughly $769 million across three straight months of withdrawals.
Despite the broader downturn, Wells Fargo held around $21.5 million in Ether ETFs in Q1 2026, with ETHA as the largest position at $17.6 million.
Bitcoin dominates holdings, equity rotations favor Strategy over Galaxy
Bitcoin ETFs remain the dominant crypto ETF exposure in Wells Fargo’s portfolio, with IBIT making up the bulk of the exposure at roughly $250 million.
In equities, Wells Fargo made a more pronounced shift in crypto-linked holdings. The bank significantly reduced its stake in Michael Novogratz’s Galaxy Digital (GLXY), cutting its position from about 2.5 million shares in Q4 2025 to roughly 78,600 shares in Q1 2026, a decline of nearly 97% and an estimated $54.7 million reduction in exposure.
Related: Galaxy Digital posts $216M Q1 loss as crypto market slides 20%
On the other hand, Wells Fargo significantly increased exposure to Michael Saylor’s Strategy, the world’s largest public Bitcoin holder.
The bank raised its stake from about 322,700 shares in Q4 2025 to roughly 726,000 shares in Q1 2026, a gain of around 403,000 shares, or 125%, and an estimated $41.6 million increase in exposure.
Magazine: Strategy reveals why they would sell BTC, Trump Media posts loss: Hodler’s Digest, May 3 – 9
The following gives an overview of the fintech, digital and wider economic development of the Southeast Asian nation of Malaysia in 2026.
Malaysia has long been viewed as one of Southeast Asia’s more structured digital economies. It is less chaotic than its regional peers, but arguably more deliberate in how it builds financial innovation. The past few years, the country’s fintech ecosystem was already among the most developed amongst the Association of Southeast Asian Nations (ASEAN). This was supported by strong regulation, high digital adoption, and a diversified financial sector. Now, that positioning has deepened. Malaysia is no longer simply a regional participant in fintech. It is increasingly shaping the architecture of digital finance in Southeast Asia.
Minus ASEAN nations of Singapore and Brunei, Malaysia is one of the wealthiest nations in the region with a gross domestic product (GDP) per capita of over $16,000. Last year, GDP as a whole grew 5.2 per cent. This is supported by domestic demand, exports, and investment.
Spanning towards the fintech sector
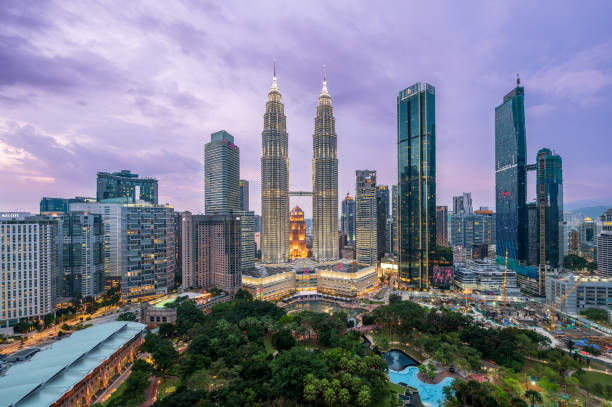
Petronas Towers, Kuala Lumpur IMAGE SOURCE: GETTY
Malaysia’s economy is highly diversified, spanning manufacturing, services, finance, and digital industries, with Kuala Lumpur serving as the financial and commercial hub. Major institutions such as Maybank remain central to the financial system, while increasingly embracing digital banking and fintech partnerships.
This economic structure has enabled Malaysia to build one of the most mature fintech ecosystems in the region. There are over 500 fintech players in the country. In terms of active players, there are, as of last year, shy of 400 active fintech players. Payments remain the dominant segment, followed by e-wallets, lending platforms, and digital wealth services. Importantly, the ecosystem is no longer defined by early-stage experimentation. Rather, it is entering a phase of scale, integration, and regulatory sophistication.
At the heart of this transition is Bank Negara Malaysia, which is the country’s central bank. In the last few years, they have taken a highly proactive approach to fintech development. One of the most notable milestones has been the full rollout of five licensed digital banks, which are now operational and targeting underserved segments such as small and medium enterprises (SMEs), younger consumers, and rural populations. This move signals a deliberate effort to expand financial inclusion through digital-first models.
At the same time, Malaysia’s payments infrastructure has undergone significant upgrades. Last year, the launch of RENTAS+ positioned Malaysia as ASEAN’s first country with a 24/7 real-time gross settlement system, enabling continuous interbank transfers and improving liquidity efficiency. Complementing this, the DuitNow ecosystem has expanded rapidly, with millions of QR acceptance points and widespread consumer adoption, reinforcing Malaysia’s transition towards a cash-lite society.
What is particularly notable this year is the shift towards open finance. Bank Negara Malaysia has introduced exposure drafts outlining a consent-driven data-sharing framework, designed to give consumers greater control over their financial data while enabling innovation across the ecosystem. This marks a critical evolution from open banking concepts towards a broader, system-wide approach to financial data interoperability.
Alongside this, Malaysia is also advancing in digital assets and next-generation finance. The launch of the Digital Asset Innovation Hub in 2025 created a controlled environment for testing new financial products, including tokenised deposits and stablecoin-based settlement solutions in collaboration with major banks and corporates. These initiatives suggest that Malaysia is positioning itself not just as a consumer fintech market, but as a laboratory for financial innovation.
Boosting financial and digital inclusion
Financial inclusion in Malaysia is relatively high compared to many emerging markets, with widespread access to banking services and digital payments. The growth of e-wallet usage, which accounts for a significant share of e-money transactions, highlights how digital finance has become embedded in everyday life. At the same time, fintech solutions are increasingly targeting SMEs, where access to financing remains a persistent challenge despite the sector accounting for over 96 per cent of businesses.
Beyond financial services, Malaysia’s broader digital transformation agenda continues to reinforce fintech growth. Government strategies emphasise digital economy expansion, with projections suggesting digital technology could contribute over 25 per cent of GDP in the coming years, according to PwC. This aligns with the country’s ambition to position itself as a regional hub for digital services, Islamic finance, and technology innovation.
Institutionally, Malaysia benefits from a well-developed ecosystem of regulators, industry bodies, and innovation platforms. Regulatory sandboxes, fintech associations, and strong collaboration between banks and startups have created a relatively balanced environment. This is one where innovation is encouraged, but within clearly defined regulatory boundaries.
On thing to note – one aspect of financial inclusion in Malaysia has been the popularity of QR payments. Like much of Asia, this is a reflection of its impact in the country. In fact, the country is reported to be the second highest user of QR payments in the world behind China.
Despite Malaysia’s successes, challenges remain. Competition from regional fintech hubs such as Singapore and Indonesia continues to intensify, while regulatory complexity and the need for continuous innovation place pressure on both incumbents and startups. Additionally, ensuring that fintech growth translates into meaningful inclusion. This is in particular with SMEs and lower-income segments.
Malaysia represents one of the more complete fintech ecosystems in Southeast Asia – they combine scale, structure, and strategic intent. By this year, its fintech landscape is no longer defined by growth alone, but by maturity, integration, and a clear sense of direction. The challenge now is to sustain innovation, deepen inclusion, and maintain regional competitiveness in an increasingly crowded and fast-evolving fintech landscape.
Richie is a global economic development advisor and Managing Partner of Santos-Diaz LLC, specializing in international trade and foreign direct investment across the UK, Middle East, and North America. With over 15 years of experience and a Masters from SOAS University of London, he has advised high-level governments and multinational corporates while contributing to major outlets like Forbes and the World Economic Forum. Currently based in Dubai, he leverages his background in emerging markets and RegTech to bridge the gap between global policy and private sector growth.
View all posts
Executive Economic Development Advisor (Emerging Markets) | Contributor
Trusted Editorial content, reviewed by leading industry experts and seasoned editors. Ad Disclosure
A Florida man accused of running a nearly three-year crypto investment scheme is speaking out — and saying sorry.
Christopher Delgado, former CEO of Goliath Ventures, sat down for a televised interview this week to apologize to the people who lost money under his watch.
Confined To A Luxury Estate
Delgado is currently out on bail, but he is not a free man. He is confined to his home — an 11,000 square foot estate in Florida — and fitted with an ankle monitor.
That estate, according to US prosecutors, was bought with investor funds. Three other Florida properties, bringing the combined real estate total to $14.5 million, were also allegedly purchased using money from investors.
Prosecutors with the Orlando US Attorney’s Office charged Delgado with fraud and money laundering on February 20 over an alleged $328 million crypto investment Ponzi scheme. He faces up to 30 years in federal prison if convicted on all counts.
In the interview, which aired on ABC-affiliated station WFTV, Delgado said he wanted to explain what happened and make clear how sorry he was. “They put their trust in me, and I failed them,” he said.
Who Were The Crypto Investors?
The people who lost money were not wealthy speculators. Reports indicate the investor pool included nurses, teachers, firefighters, and retirees — people who handed over their savings based on promises of steady monthly returns from cryptocurrency liquidity pools.
One investor lost roughly $720,000. That person was told returns were guaranteed and that the money could be pulled out at any time.
According to federal prosecutors, Goliath Ventures operated as a Ponzi scheme from January 2023 through January 2026. Company funds were used not only on real estate but also on lavish company events, Christmas parties, and upscale travel.
BTCUSD currently trading at $80,574. Chart: TradingView
When asked how Goliath handled investor money, Delgado acknowledged the company was paying people what he called an astronomical amount.
By the time of his arrest, Delgado said only $160,000 remained in Goliath’s bank account.
JPMorgan Pulled Into Legal Fight
The case has spilled beyond Delgado himself. In March, a group of investors filed a proposed class action lawsuit against JPMorgan Chase, claiming the bank played a role in moving funds tied to the alleged scheme.
Based on reports, the lawsuit claims $253 million was deposited into a JPMorgan account between January 2023 and June 2025, with about $123 million of that later transferred to Goliath wallets at Coinbase.
Featured image from Unsplash, chart from TradingView
Editorial Process for bitcoinist is centered on delivering thoroughly researched, accurate, and unbiased content. We uphold strict sourcing standards, and each page undergoes diligent review by our team of top technology experts and seasoned editors. This process ensures the integrity, relevance, and value of our content for our readers.
NEAR Intents upgraded its frontend to enable single-flow swaps from over 100 tokens directly into ZEC, leveraging intent-based architecture for crosschain transactions.
NEAR Intents announced an expanded crosschain swapping capability, allowing users to swap from 100+ tokens directly into Zcash (ZEC) through a single transaction flow on an upgraded frontend. The update leverages NEAR’s intent-based infrastructure to facilitate the multi-token-to-ZEC conversions, streamlining the user experience for accessing privacy-focused digital assets across blockchains.
The upgrade demonstrates NEAR’s focus on crosschain interoperability through its Intents protocol, which abstracts complex backend routing logic to simplify user interactions. By integrating Zcash into the broader swapping ecosystem, NEAR Intents targets users seeking to consolidate multiple token holdings into a single privacy-enhanced asset without navigating multiple separate protocols or bridges.
Sources: NEAR Intents
This article was generated automatically by The Defiant’s AI news system from publicly available sources.
Payward, the parent company of crypto exchange Kraken, is working with asset manager Franklin Templeton to expand the use of tokenized financial products for institutional investors.
The companies said Tuesday they will develop a range of blockchain-based investment offerings, including tokenized yield products, tokenized equities and custody services tied to digital assets.
The move comes as large financial firms explore testing tokenized versions of conventional assets. BlackRock, Fidelity and JPMorgan have all expanded blockchain-related financial products over the past two years, particularly tokenized Treasuries and money market funds.
Tokenization refers to representing traditional financial assets such as stocks, bonds or money market funds on blockchain networks, where they can be traded and settled digitally. Supporters argue the approach can reduce settlement times, expand market access and allow assets to move more easily between financial platforms.
The collaboration joins two firms that have taken different routes into tokenized finance. Franklin Templeton has spent years building blockchain-based investment products. Payward has focused on crypto trading infrastructure through Kraken and its xStocks tokenized equities platform, which the company says has processed more than $30 billion in trading volume since starting up in 2025.
The firms plan to explore actively managed tokenized investment products that could trade onchain and become available to institutional investors and, in some jurisdictions, retail Kraken users.
Kraken also plans to integrate BENJI, Franklin Templeton’s suite of tokenized money market funds, into its platform. The funds could serve as collateral or cash management tools for institutional trading clients seeking blockchain-based alternatives to traditional treasury operations.
Analysts view tokenized Treasury funds as one of the fastest-growing sectors in digital assets because they offer yields tied to government securities while operating on blockchain rails. In practice, that can allow institutions to move collateral around the clock instead of waiting for banking hours or multiday settlement periods.
Read more: Kraken parent Payward seeks fresh funding at $20 billion valuation ahead of planned IPO
Management consulting firm Arthur D. Little has published an in-depth report titled ‘The Next Phase of MENA Fintech Growth’. Conducted jointly with the grassroots community Fintech Tuesdays in the second half of 2025, the research draws on first-hand perspectives from more than 140 founders and C-suite executives operating across the region.
The findings provide a grounded assessment of the sector’s structural foundations—including regulatory depth, investor track records, and accelerating digital adoption—as the industry navigates near-term economic headwinds.
Optimism meets market realism
The survey reveals a landscape defined by profound optimism meeting realistic capital constraints. A significant 77 per cent of respondents indicated that MENA fintech was stronger in 2025 than in the preceding year, while 75 per cent rated their optimism about the medium-term future at a four or five out of five. However, founders are not ignoring market realities, as 78 per cent of participants cited a lack of cross-border regulatory harmonization as a major barrier, and 73 per cent reported fundraising difficulties.
Industry leaders pointed to the United Arab Emirates and Saudi Arabia as the primary engines for future development. Around 60 per cent of respondents identified the UAE as the market most likely to lead fintech innovation over the next three years, with nearly half viewing the country’s regulatory landscape positively. Meanwhile, Saudi Arabia’s rising fintech strength also earned significant recognition, capturing 31 per cent of the vote from entrepreneurs and founders backing the Kingdom to lead on innovation.
Overcoming global funding constraints
Arjun Singh, partner and global head of financial services at Arthur D. Little Middle East
Despite cautious funding environments worldwide, the Middle East successfully recorded a series of standout transactions in 2025, pushing venture capital funding to an impressive $3.8billion across the region. High-profile deals reflected continued investor conviction in regional infrastructure, including major raises by AI-native Islamic bank Mal at $230million, financial services app Tabby at $160million, embedded finance firm HALA at $157million, and crypto exchange Rain at $58million.
Arjun Singh, partner and global head of financial services at Arthur D. Little Middle East, noted that the region’s historical track record is now paying off. Fintech in the Middle East has spent a decade earning the right to be taken seriously through regulatory frameworks, record investment cycles, and genuine adoption, Singh explained, adding that this structural depth is exactly what the region will draw on as the current environment tests it.
Growth opportunities and technological innovation
Mehdi Letaief, principal of financial services at Arthur D. Little Middle East
The report identifies six major structural opportunity areas poised for immediate disruption. These include SME financing to address underserved enterprises, cross-border payments leveraging digital rails, and digital wallets functioning as a leapfrog technology for financial inclusion. Additionally, the study highlights strong potential in digital-first Islamic finance products, the ongoing evolution of Web2-to-Web3 payments, and tokenization opportunities within the massive regional real estate market. Driving these opportunities are several transformative technological innovations, with respondents ranking embedded finance highest at 34 per cent, closely followed by artificial intelligence and machine learning at 29 per cent, and open banking capturing 21 per cent of the focus.
To capitalize on this momentum, the report outlines clear recommendations for key stakeholders. It highlights the urgent need for greater regulatory harmonization and clearer rules across the Gulf Cooperation Council. It also urges traditional banks to move beyond simple pilot programs to enable genuine, win-win partnerships, while advising fintechs to adapt to the operating models of their traditional partners and fully embrace embedded finance architectures.
Mehdi Letaief, principal of financial services at Arthur D. Little Middle East, framed these recommendations as a critical call to action. The data is clear that this ecosystem has built something real over the past decade, Letaief commented. He stated that the task now is to protect what has been built, maintain collaboration between regulators, banks, and fintechs, and use the current moment to demonstrate that structural depth holds under pressure.
The ongoing war in Iran and the race to dominate the AI sector will result in money printing that could benefit the crypto ecosystem and push Bitcoin back to its all-time high this year, according to Arthur Hayes, the chief investment officer of crypto investment fund Maelstrom.
In a Substack post on Tuesday, Hayes said the competition between US and China to win the arms race has led both to pursue looser financial conditions and more fiat printing as the technology “directly relates to national security.”
“The combination of the political will to win the AI race and the financial will to fund the build-out with printed money and bank loans produces the perfect environment for crypto,” he said.
Source: Arthur Hayes
“There will be vastly more units of fiat tomorrow than today, and the rate of change is accelerating due to rapidly increasing yearly AI and electrification CAPEX expenditures,” Hayes added.
Most of the crypto sector registered new all-time highs last year, with the market capitalization hitting $4.28 trillion in October, according to CoinMarketCap. However, the market slumped toward the end of last year, and analysts have debated when it will fully recover.
Bitcoin to $126,000 is a “foregone conclusion”
Hayes said war is inflationary and the Iran conflict is no different. Military spending and a shift by nations toward domestic infrastructure investment rather than US Treasurys and equities will lead to further money printing.
He also predicted in March that the US Federal Reserve could ease monetary policy to help finance the country’s conflict with Iran and boost crypto.
Related: Hyperliquid’s HYPE price will increase by August, predicts Arthur Hayes
“The politicians support this money printing out of real and perceived necessity. That is why Bitcoin post-February 28th is outperforming the other major risky assets such as gold and US tech stocks,” Hayes added.
Bitcoin has traded between $79,467 and $82,496 over the past seven days, according to CoinGecko. It was trading at about $81,000 as of Wednesday, up more than 31% from its Feb. 6 low of $62,822. Gold was trading around $4,581 at the start of February and has climbed to $4,710 in the same timeframe, for a 2% gain.
Arthur Hayes said Bitcoin has been outperforming other major assets, such as gold, since February. Source: Substack
“Bitcoin bottomed earlier this year at $60,000, and with a tailwind of trillions of dollars and yuan yet to be created at its back, retaking the $126,000 is a foregone conclusion,” Hayes said.
“I expect the rally to intensify and the haters to cower in the corner as Bitcoin’s upward price trajectory turns explosive after punching through $90,000, where many call over-writers will rush to cover as their strike gets taken out.”
Magazine: Guide to the top and emerging global crypto hubs — Mid-2026
The Senate Banking Committee publicly released the full text of its crypto market structure bill ahead of Thursday’s markup, with amendments due by end of business Wednesday.
The US Senate Banking Committee released the full 309-page draft of the Clarity Act on Tuesday, May 12, 2026, making public the cryptocurrency market structure bill it has been developing since January. Committee members now have until close of business Wednesday to file amendments before the scheduled Thursday markup vote. The legislation had previously circulated among industry stakeholders behind closed doors.
The Clarity Act represents a major regulatory effort to establish clear federal framework for digital asset classification and oversight. The bill’s public release marks a critical step in the legislative process, allowing committee members and the broader crypto industry to formally review and respond to the proposal before markup proceedings begin.
The Ethereum community has introduced Clear Signing, a security feature that ensures users can clearly understand transaction details before signing, replacing unreadable hex data and reducing risks from blind signing attacks.
“Approving a transaction is meant to be the last line of defense when exercising control over what happens to your assets on the blockchain. When it is done blindly, that defense does not hold,” the Ethereum Foundation said on Tuesday, calling blind signing a “structural flaw” that has contributed to billions of dollars in losses, including the $1.4 billion Bybit hack last year.
The “What You See Is What You Sign” security feature aims to address this issue and is being integrated by several self-custody crypto wallets, including Ledger, Trezor and MetaMask.
Source: Ethereum Foundation
The security feature comes as bad actors target the crypto industry with increasingly sophisticated hacks and scams despite considerable improvements in security measures in recent years.
North Korean state-backed workers have stolen over $7 billion in funds alone since 2009, with a large share of that coming from crypto protocols. The Bybit hack was its largest crypto heist by compromising a third-party service provider and manipulating transaction signatures.
Trezor chief technology officer Tomáš Sušánka told Cointelegraph that attackers have been exploiting this relentlessly due to there not being a widely accessible security feature that is capable of distinguishing malicious smart contracts from legitimate transactions.
This issue has led users to “unknowingly sign them, and lose everything,” Sušánka said, adding that the Clear Signing feature “directly addresses this by making transactions human-readable before approval.”
The Clear Signing feature was introduced through the Ethereum Foundation’s Trillion Dollar Security Initiative and initiated by Ledger through the open-source ERC-7730 token standard.
The foundation said the key components of the Clear Signing feature include “human-readable transaction descriptions” and a “neutral, mirrorable descriptor registry.”
Related: Ethereum’s EEZ could pull other blockchains into its orbit
It also includes an attestation framework enabling auditors to verify those descriptors.
A host of crypto platforms are supporting Clear Signing
Several other crypto wallets and Ethereum privacy and security platforms contributed to the Clear Signing feature, including Keycard, WalletConnect, Argot, Sourcify, Zama, ZKnox and Fireblocks.
Sušánka said Trezor seeks to implement the security feature before June 30.
“We’re implementing this standard because it’s the right thing to do for our users,” Sušánka said before calling the Clear Signing feature a “critical security advancement for our entire industry.”
Magazine: Guide to the top and emerging global crypto hubs: Mid-2026
Affirm’s pay-over-time options will be integrated into the Gemini app and Google Search, including AI Mode, through Google Pay
AI is changing how people discover and decide what to buy. But those decisions can’t turn into purchases without a clear and trustworthy way to pay.
At the moment of payment, people want to know exactly what they’re agreeing to — especially when decisions are happening quickly or with the help of an agent. Without that clarity, AI-driven commerce breaks down.
That’s why Affirm is expanding its work with Google to start rolling out its payment options into Google Search, including AI Mode, and the Gemini app when checking out with Google Pay. Shoppers will be able to move confidently from decision to purchase, with the same clear options and transparent terms they rely on from Affirm.
Built for the agentic commerce shift
Many traditional financial products have inherent complexities — balances that change over time, interest that compounds, and terms that make it difficult to calculate the total cost when you’re ready to check out.
Affirm was built differently. Every transaction is evaluated in real time, with straightforward terms, no hidden fees, and payment plans designed around what a consumer can afford. Those terms are designed to be instantly understood — by both discerning shoppers and the agents supporting them.
Because Affirm evaluates each purchase individually, it can present options that make sense in the moment. Consumers can choose what works for them with confidence, merchants can see more intent turn into completed purchases, and platforms can deliver experiences that feel consistent and trustworthy wherever people shop.
“People deserve transparent, flexible financial options. Agentic commerce may be the moment that makes that impossible to ignore,” said Vishal Kapoor, SVP of Product at Affirm. “From day one, Affirm was built around clear terms and transparency, so people can confidently use credit for specific purchases without worrying about fine print or surprises. As more decisions are made by AI on people’s behalf, products that rely on hidden terms or ambiguity won’t hold up — the ones that are clear and predictable will.”
Bringing buy now, pay later experiences to Google
Now in Google Search and the Gemini app, shoppers will start to see Affirm as a payment option within Google Pay at checkout. After choosing Affirm, they’ll go through a real-time eligibility check and, if approved, choose the plan that works best for them. They’ll see the full cost, payment schedule, and end date before committing, and as always with Affirm, will never owe a penny in late or hidden fees.
“As AI becomes a more active part of how people discover and buy, it’s critical that the payment options remain secure and reliable,” said Ashish Gupta, VP/GM, Merchant Shopping at Google. “Our work with Affirm brings transparent, flexible payment options into these new journeys, so as shopping evolves, people can continue to make decisions with confidence.”
This experience is rolling out to consumers and merchants in the coming weeks, giving people more ways to use Affirm across the Google ecosystem, from wallets and browsers to AI-powered shopping journeys.
Building what comes next
As shopping evolves, it’s not just about showing up in new experiences — it’s about helping define how they work.
In addition to initial launches within Google Pay on the Gemini app and Google Search, Affirm has independently developed an early version of BNPL extensions for the Universal Commerce Protocol (UCP), the open standard for agentic commerce. Affirm is hosting this extension on its site to gather feedback and refine development.
These extensions are designed to ensure pay-over-time works consistently across the ecosystem — embedding transparency, clear terms, and consumer-first principles into the foundation of how transactions happen. The goal is not just to make payments seamless, but to make them understandable and aligned with how people actually want to manage their money.