Home Blog Page 247

Paxos Wins SEC Clearing Agency Registration

Blockchain infrastructure platform and stablecoin issuer Paxos says it has become the first “blockchain-native” firm that the US Securities and Exchange Commission has granted registration as a clearing agency.

Paxos said on Thursday that its subsidiary, Paxos Securities Settlement Company, has become “the only blockchain-native firm” that the SEC approved to provide clearing and settlement services as a central securities depository in the US.

The approval represents a “critical piece of financial market infrastructure” as blockchain technology and traditional capital markets continue to converge, the company added. 

Clearing agencies ensure securities trades are executed cleanly. Stock buyers and sellers do not trade directly and need clearing and settlement providers that verify the trade, match the buyer and seller, and then ensure the actual exchange of money and securities happens correctly.

A registered, SEC-approved blockchain clearinghouse removes barriers for banks and brokerages to build crypto-based infrastructure.

In October 2019, the SEC issued a no-action letter allowing Paxos to pilot a blockchain-based settlement service for US equities, and the service launched in February 2020.

Paxos said the pilot demonstrated that blockchain-based post-trade infrastructure could deliver same-day settlement, reduce costs and improve operational efficiency within a fully regulated framework.

“Our clearing agency registration is the result of seven years of work with the SEC, beginning with our No-Action Letter in 2019 and the settlement pilot we operated with some of the world’s largest and most sophisticated financial institutions,” said Paxos co-founder and CEO Charles Cascarilla.

Related: Paxos Labs to use $12M raise toward yield, lending, issuance tools

Paxos is the issuer of several stablecoins and digital assets, including PayPal USD (PYUSD), Global Dollar (USDG) and Pax Gold (PAXG).

The company has had a rocky history with the SEC under its former chair, Gary Gensler, having received a Wells Notice in 2023, with the agency planning to recommend an enforcement action over the issuance of Binance USD (BUSD), a stablecoin tied to the crypto exchange Binance, which the SEC considered an unregistered security.

Around the same time, the New York Department of Financial Services (NYDFS) ordered Paxos to stop minting new BUSD. 

The SEC closed its investigation in 2024 and issued a formal termination notice, stating it would not pursue enforcement action. Paxos also reached a $48.5 million settlement with NYDFS in August 2025 over Binance and BUSD compliance issues.

Magazine: Big Questions: Do we really only need 2–5 cryptocurrencies?
Bitcoin’s Next Correction May Be Linked To $9B Options Expiry

0

Key takeaways:

  • Bears gained a major edge ahead of Friday’s $9 billion options expiry, especially if Bitcoin price stays below $74,000.
  • Spot Bitcoin ETF outflows and corporate BTC balance reductions fueled market pessimism.

Bitcoin (BTC) retested the $72,500 level for the first time in six weeks on Thursday, triggering $342 million in liquidations for bullish leveraged positions. Despite a subsequent relief bounce to $73,500, traders are worried that bears will keep control due to the upcoming $9 billion monthly options expiry.

May 29 Bitcoin call (buy) options open interest at Deribit, BTC. Source: Deribit

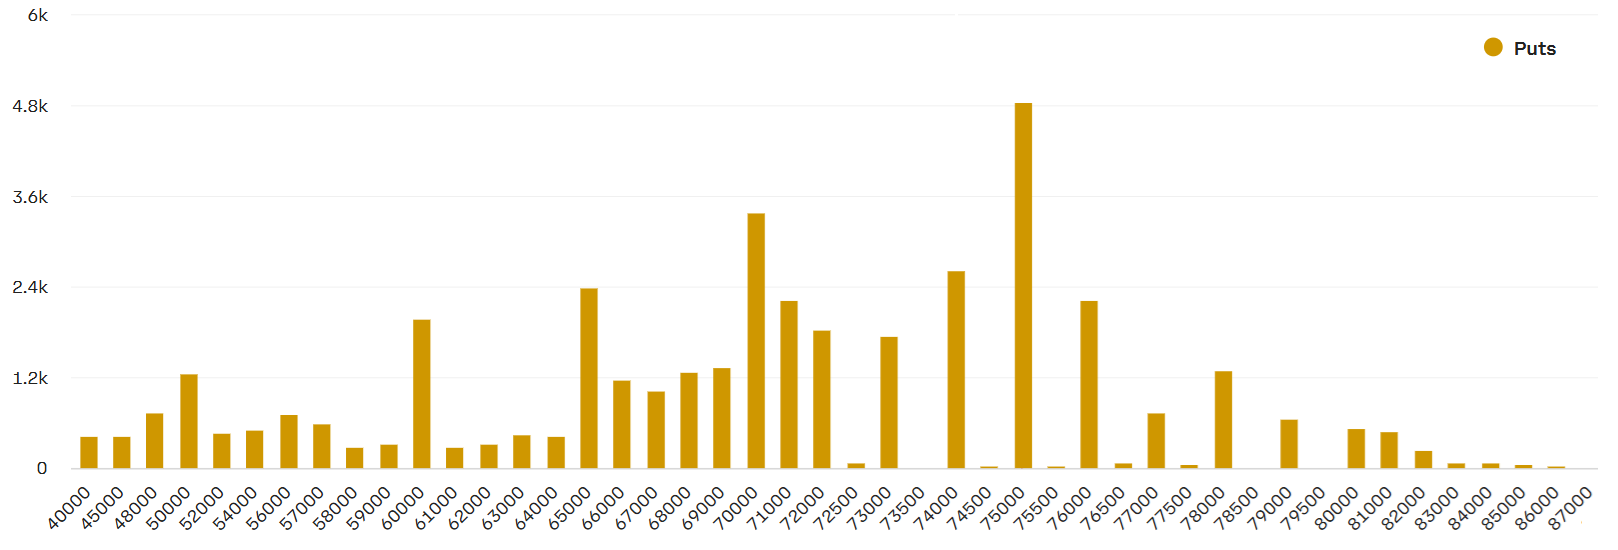
Deribit holds a 70% market share for the May monthly options expiry, capturing $3.4 billion in open interest for calls (buy) and $2.91 billion for puts (sell). However, bulls were caught off guard when Bitcoin broke below $78,000 on May 17.

If Bitcoin stays below $74,000 heading into Friday’s expiry, only $306 million worth of call options will remain in the money. In contrast, put options targeting $74,000 or higher total $1.05 billion, giving bearish strategies a massive advantage.

May 29 Bitcoin put (sell) options open interest at Deribit, BTC. Source: Deribit

Even if Bitcoin reclaims $74,000 by Friday, put options will still outpace call instruments by $265 million. On the bright side, there is no excessive demand for downside protection right now, as put options volume typically spikes only when traders anticipate severe negative surprises.

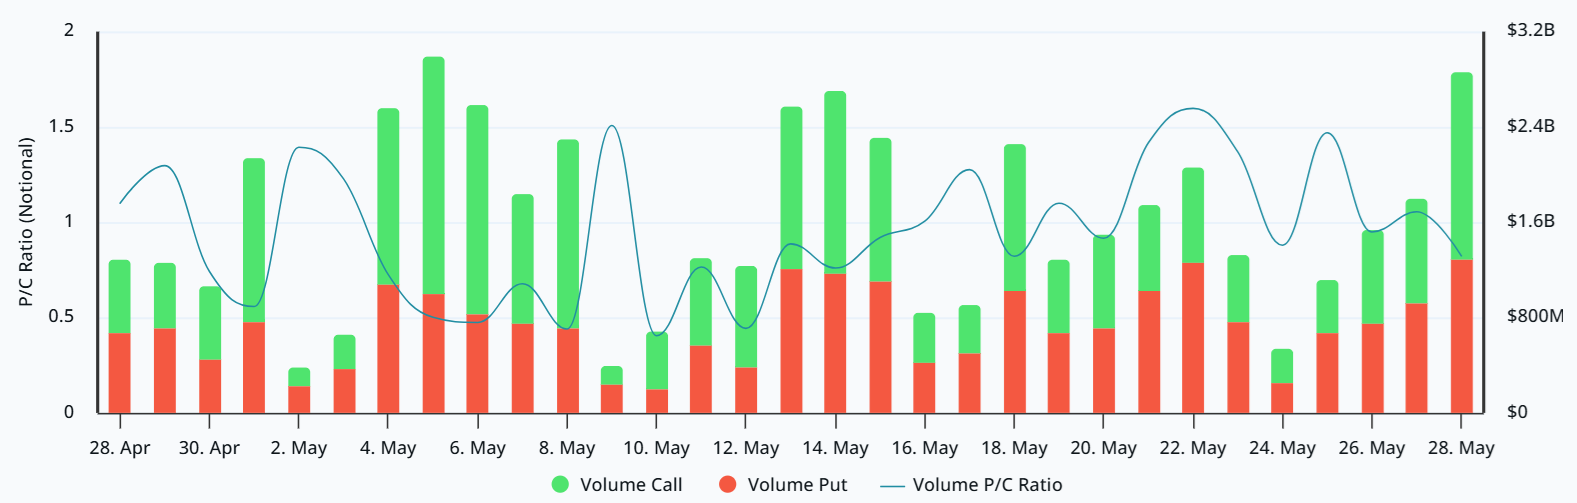
Bitcoin options put-to-call volume ratio, USD. Source: Laevitas

The Bitcoin options put-to-call volume ratio stood at 0.8 on Thursday, reflecting $1.57 billion traded in calls versus $1.29 billion in puts. This neutral setup represents an improvement from the prior week, which was marked by heavy demand for defensive, neutral-to-bearish options strategies.

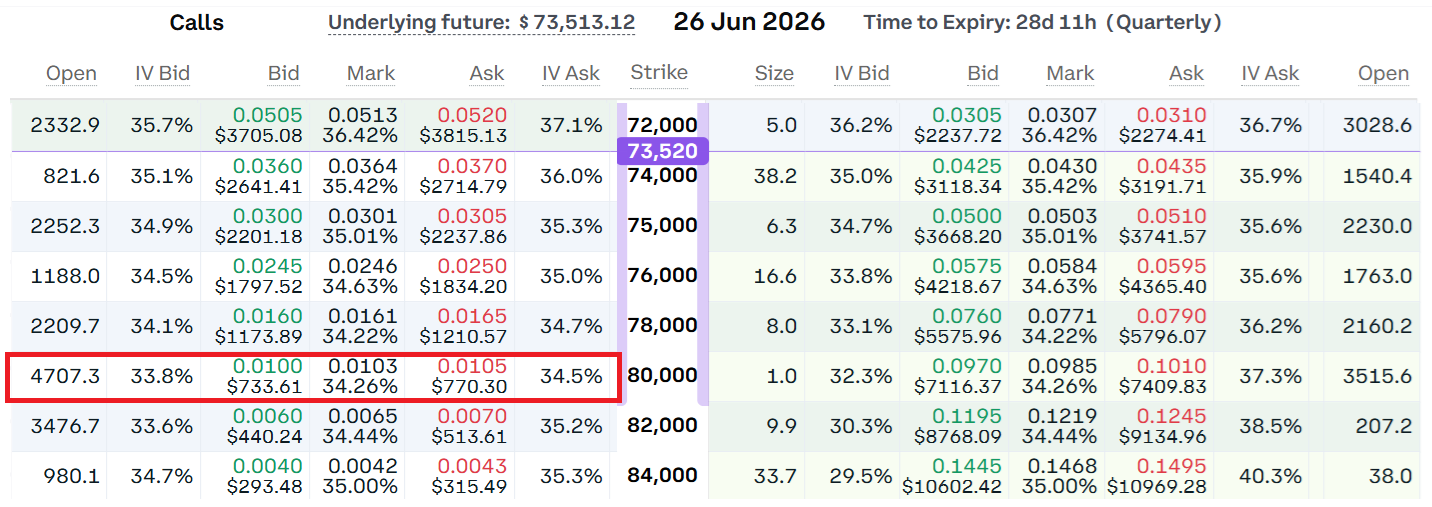
Bitcoin only has an 18% chance of reaching $80,000 by June 26

The June 26 expiry shows traders are generally uninspired by Bitcoin’s short-term price prospects.

Deribit June 26 Bitcoin options pricing. Source: Deribit

The $80,000 June call option traded at 0.0103 BTC on Thursday, equivalent to $757. Given the 28 days remaining until expiry, the implied odds of Bitcoin trading above that level sit at 18%. This widespread pessimism can be partly attributed to the $1.07 billion in net outflows from US-listed spot Bitcoin ETFs over two days.

Related: Bitcoin falls further as BTC miners pivot to AI, pro-crypto legislation stalls

On Thursday, Paris-based semiconductor developer Sequans Communications (SQNS) announced plans to fully liquidate its Bitcoin holdings, abandoning its previous accumulation strategy. Publicly traded mining firms, as well as Trump Media and Technology Group (DJT), have also recently scaled back their Bitcoin exposure.

While it is impossible to predict whether a correction to $70,000 is the most probable scenario based solely on Bitcoin options flows and positioning, bears clearly hold the upper hand heading into the upcoming Friday expiry at 8:00 am UTC. Lingering fear and market uncertainty should prevail, significantly weakening the odds of any sustained bullish momentum in the short term.

Trump Claims he can ‘Future Proof’ Crypto Regulation with CLARITY Act

US President Donald Trump said Wednesday that he intended to codify a “future-proof digital asset market structure,” likely referring to the Digital Asset Market Clarity Act (CLARITY) under consideration in the US Senate.

In a post to his Truth Social platform for the second time this week on policy claims potentially affecting the cryptocurrency industry, Trump said the law would prevent “crypto haters” in future administrations from rolling back regulations affecting digital assets.

Source: Donald Trump

Since its passage by the US House of Representatives in July 2025, the CLARITY Act has faced months of delays in the Senate amid government shutdowns, pushback from crypto and banking industry representatives and concerns over conflicts of interest, including those involving the Trump family. The president or his sons are tied to memecoin projects, the platform World Liberty Financial, that platform’s USD1 stablecoin and a Bitcoin mining company.

Although lawmakers on the Senate Agriculture Committee and Senate Banking Committee have already advanced the CLARITY Act following respective markups in January and May, the bill faces other hurdles before a potential vote in the full chamber. Republicans hold a slim majority in the Senate and will need Democratic votes to pass the bill, but some lawmakers have signaled they will withhold support without provisions on ethics.

Related: US CLARITY Act will be a ‘boon for domestic innovation’: A16z

The price of Bitcoin dropped under $73,000 from more than $74,000 in the hours following Trump’s pledge to “never let crypto down.” At the time of publication, the price of the biggest cryptocurrency by market cap was $73,467.

Trump’s remarks echoed those of his hand-picked chair of the US Securities and Exchange Commission (SEC), Paul Atkins, who in October said the agency would work to future-proof “future potential changes,” including those affecting crypto.

DeFi Technologies President Andrew Forson told Cointelegraph at the time that it would be difficult for a future SEC chair to “fully reverse” previously enacted policies, but they could be made overly burdensome for regulators.

Trump weighs in on prediction market legal battle

Wednesday’s Truth Social post followed Trump’s comments that reiterated claims made by Commodity Futures Trading Commission (CFTC) Chair Michael Selig — also the president’s pick to head the agency — that the regulator had “exclusive jurisdiction” over prediction markets like Kalshi and Polymarket. Trump’s son, Donald Trump Jr., is an adviser to Kalshi and Polymarket.

Several state authorities have filed lawsuits against prediction markets, alleging that the companies offer illegal bets on sporting events without a license. The CFTC has responded with its own countersuits.

Magazine: Big Questions: Do we really only need 2–5 cryptocurrencies?
Hacker Mints 5.4 Trillion Tokens in StakeDAO Exploit, Nets $91K

0

A compromised private key let an attacker forge a cross-chain message on Arbitrum, triggering cascading warnings across Curve Finance and Beefy Finance.

A hacker compromised StakeDAO’s deployer private key on Wednesday, minting 5.4 trillion vsdCRV tokens on Arbitrum and swapping a portion for roughly $91,000 worth of ETH, an attack that rippled into Curve Finance’s lending market and forced yield optimizer Beefy Finance to pause an affected vault.

StakeDAO, a DeFi protocol with $131 million in total value locked that allows users to earn boosted yields on Curve Finance liquidity pools through locked CRV positions, warned users to stop interacting with vsdCRV immediately following the incident. The protocol has not disclosed the total value of assets at risk or a timeline for remediation.

StakeDAO’s SDT governance token fell approximately 6.6% in the 24 hours surrounding the incident, according to CoinMarketCap data, with trading volume in SDT spiking more than 400%, per CoinGecko.

SDT Price. Source: CoinGecko

Attack Mechanics

According to web3 security firm Blockaid, which first flagged the attack, the attacker used a stolen key to tamper with StakeDAO’s vsdCRV token contract, which relies on LayerZero to validate mint instructions. By replacing the legitimate authorized address with one they controlled, the attacker could issue their own mint commands.

The attacker used the stolen key to replace the legitimate authorized address on StakeDAO’s vsdCRV contract with one they controlled, then sent a forged instruction that minted 5,446,744,073,709 vsdCRV on Arbitrum, tokens backed by nothing.

Blockchain security firm PeckShield reported the exploiter converted part of those tokens into 43.78 ETH, worth approximately $91,170 at the time of the exploit, and bridged the proceeds to Ethereum address 0xeF3C…aa25.

Same LayerZero Playbook

The attack follows a pattern that’s become common in recent months: attackers abusing LayerZero’s Omnichain Fungible Token (OFT) cross-chain token standard by manipulating peer configurations to forge mint events on destination chains.

In April, a similar architectural weakness in Kelp DAO’s LayerZero bridge allowed attackers to drain $290 million in rsETH. In that case, LayerZero later acknowledged it had made a mistake in its verifier configuration.

In the StakeDAO case, Blockaid said the suspected root cause was a compromised private key rather than a verifier configuration flaw, but the exploit path also consisted of forging a trusted cross-chain message and triggering an unbacked mint.

The LayerZero OFT standard allows tokens to move across blockchains by burning on one chain and minting on another. The system relies on peer configurations — trusted addresses registered on each chain — to validate whether a mint instruction is legitimate. If a deployer key controlling those configurations is compromised, an attacker can silently swap in a malicious peer and instruct it to authorize an unlimited mint.

Curve and Beefy

The fallout extended beyond StakeDAO. Curve Finance warned users with deposits or loans in the asdCRV LlamaLend market on Arbitrum to exit immediately. While the market itself remained functional, Curve said the vsdCRV exploit could destabilize its price oracle and trigger unexpected liquidations.

Beefy Finance, a multichain yield optimizer, separately disclosed that its Arbitrum Convex CRV/csdCRV/asdCRV vault was hit. Beefy said it paused the vault and was coordinating with StakeDAO, Curve, and Convex on potential recovery plans.

What Comes Next

The on-chain forensics are documented publicly: Blockaid has published the malicious peer deployment transaction, the cross-chain mint transaction, the setPeer transaction on Arbitrum, and the mint transaction on Arbitrum. StakeDAO has not confirmed whether the compromised deployer key has been rotated or when affected contracts will be redeployed.

April was already DeFi’s worst month on record for exploits, with $635 million stolen across 28 incidents. The StakeDAO hack adds to a growing string of attacks targeting cross-chain infrastructure in 2026.

Bitcoin’s record holder supply hides a buyer drought, CryptoQuant says

0

Bitcoin traded around $73,500 Friday morning Hong Kong time, according to CoinDesk market data, roughly 10% below the low-$80,000 levels reached earlier this month, as new data from CryptoQuant suggests one of the market’s most widely cited bullish indicators may instead reflect a shortage of buyers.

A record 15.8 million BTC is now classified as long-term holder supply, but CryptoQuant says the figure says less about investor conviction than it does about market turnover. As whale accumulation stalls and demand from ETFs and other large holders slows, fewer coins are changing hands and more are aging into long-term status.

Record long-term holder supply is typically viewed as bullish because it suggests investors are accumulating bitcoin and removing coins from active circulation.

During healthy bull markets, new buyers absorb selling from existing holders, then hold those coins long enough to join the long-term holder cohort themselves. The result is shrinking available supply alongside growing demand, a combination that has historically supported higher prices.

CryptoQuant’s thesis is that record dormant supply layered over declining activity creates a thinner market beneath the surface, one where relatively small shifts in buying or selling can have an outsized impact on price.

The firm estimated short-term holder supply has fallen by roughly 2.2 million BTC since December. About 900,000 BTC of that decline came from Coinbase reserves aging beyond the 155-day threshold used to classify long-term holders. The reclassification is technically an accounting event, but it is indicative of the report’s central argument: a growing share of bitcoin is simply not moving.

With fewer new buyers entering the market, coins remain in the hands of existing holders for longer periods, gradually migrating into the long-term holder category. CryptoQuant argues the resulting record in long-term holder supply should be interpreted as evidence that market participation has slowed.

Whale balances, defined as wallets holding between 1,000 and 10,000 BTC, are contracting year-over-year at the fastest pace of 2026, while monthly balance growth has remained near zero since February.

At the same time, annual growth in dolphin balances, wallets holding between 100 and 1,000 BTC, has slowed sharply after peaking at 970,000 BTC in October 2025 (just as monthly inflows into BTC ETFs hit $3.4 billion). CryptoQuant notes that the dolphin cohort is dominated by spot ETFs and corporate treasury buyers, making it one of the clearest gauges of institutional demand.

Other market indicators point in the same direction.

Glassnode said in a recent report that spot demand has weakened, ETF inflows have faded from earlier highs, and capital flows remain too modest to support a sustained move above key cost-basis levels near $78,000. The firm’s Realized Profit/Loss Ratio currently sits at 1.56, below the 2 to 5 range typically associated with the early stages of persistent bull markets.

Prediction markets are also leaning toward stagnation rather than breakout. A Polymarket contract tracking BTC’s May 30 closing range assigns roughly 84% odds to BTC finishing between $72,000 and $76,000.

The common thread across on-chain data, ETF activity, and prediction markets is not outright bearishness but a lack of participation. Bitcoin is still holding above $70,000, yet the ownership structure beneath the market increasingly reflects investors sitting on existing positions rather than new buyers stepping in.

Sequans (SQNS) Completes Bitcoin Unwind, Exits Digital Asset Strategy After Less Than A Year

0

Sequans Communications (NYSE: SQNS), the Paris-based cellular IoT semiconductor company, has completed the full redemption of its remaining convertible debt, funded by the sale of a portion of its Bitcoin holdings — bringing a short-lived and costly digital asset treasury experiment to a close.

The company now holds approximately 658 BTC, described as “fully unencumbered,” following the retirement of all convertible notes issued in July 2025. Sequans said it plans to monetize the remaining Bitcoin over time, though it did not specify a timeline or method.

Sequans’ bitcoin bet that backfired

The retreat caps a strategy that began in June 2025, when Sequans announced plans to raise $385 million through debt and equity to start a Bitcoin treasury. 

By late July, CEO Georges Karam described Bitcoin as a “long-term store of value for our shareholders,” with a target of accumulating 3,000 BTC within weeks. The company crossed that threshold by month’s end.

The unwind began in November 2025 after Bitcoin fell from an all-time high above $126,000 to roughly $80,000. Sequans sold 970 BTC that month, followed by 125 BTC in February 2026, and another 1,025 BTC during the first quarter — reducing holdings to 1,114 BTC as of April 30. Thursday’s announcement confirmed a further reduction to 658 BTC, reflecting total sales of more than 80% of peak holdings.

Investors who bought shares at the height of Bitcoin enthusiasm last July are sitting on losses of more than 90%. SQNS shares rose 10% on Thursday following the announcement.

With the debt retired, Sequans transitions to what it calls a “near debt-free balance sheet,” giving the company greater financial flexibility heading into the second half of 2026. The move eliminates collateral obligations tied to Bitcoin’s price volatility, a risk that management had flagged in prior filings.

“We have strengthened our balance sheet, simplified our capital structure, and are now fully focused on scaling our IoT semiconductor business,” Karam said in Thursday’s statement.

Sequans’ renewed focus centers on its 4G LTE-M and Cat-1bis chipsets, which serve markets including smart metering, asset tracking, telematics, security, and industrial IoT. The company is also advancing its 5G eRedCap platform — a next-generation cellular IoT standard — as a long-term growth driver.

Karam framed Thursday’s announcement as the start of a focused operational phase. “Execute on our growing 4G and RF transceiver product portfolio, accelerate our path to profitability, and advance our 5G roadmap,” he said.

Grayscale IPO delayed as crypto firms reassess public market plans

0

Asset management giant Grayscale is the latest crypto firm to delay its plans to go public due to market conditions, according to a person with knowledge of the matter.

The Stamford-based investment firm has paused its IPO preparations, and is unlikely to restart the process until the fourth quarter at the earliest, the person said, who spoke on condition of anonymity as the matter is private.

DCG subsidiary Grayscale, one of the world’s largest crypto asset managers and the firm behind the Bitcoin Trust ETF (GBTC), filed confidentially for a U.S. IPO in November last year.

“Due to the SEC-mandated quiet period, we are unable to comment at this time,” a Grayscale spokesperson said in emailed comments.

Grayscale is a leading digital asset investment platform that provides investors with secure and regulated exposure to the cryptocurrency market. Through its suite of single-asset, diversified, and thematic investment products, the firm enables institutional and retail investors to access digital assets without the operational complexities of directly buying, storing, or managing crypto. Since its founding in 2013, the firm has played a central role in bridging traditional finance and the evolving digital asset ecosystem.

Crypto firms entered 2026 anticipating a breakout year for IPOs after successful public listings from companies such as Circle (CRCL) and Bullish (BLSH), the parent company of CoinDesk, helped revive investor interest in digital-asset businesses last year. Since then, however, worsening market conditions, softer trading activity and underwhelming post-listing performance from newly public firms, including BitGo (BTGO), have tempered enthusiasm for additional digital asset IPOs.

As a result, several major crypto firms, including Payward, the parent company of Kraken; Ethereum software developer Consensys; and hardware wallet manufacturer Ledger, have delayed their IPO plans as they wait for market conditions to stabilize.

Still, some firms are moving ahead with their listing plans. Blockchain.com said last week that it had confidentially filed for a U.S. IPO with the SEC.

Grayscale’s Ethereum Staking Mini exchange-traded fund (ETF) ranked as the top-performing U.S. ETP for Ethereum in the first quarter of 2026, drawing $337 million in inflows as of March 31, according to Bloomberg data. Despite a broader downturn in crypto markets, the firm has moved to convert or uplist 10 digital asset investment products into exchange-traded products since the fall of 2025.

Ethereum Metrics Strong, Price Lags

0

Standard Chartered says Ethereum’s network activity remains close to record levels even as Ether (ETH) trades far below last year’s highs, arguing that the gap between usage and price could eventually narrow.

Ethereum’s internal metrics, including transaction counts and total value locked in ETH terms, remain close to record levels, according to a Thursday report from Standard Chartered’s digital assets research team. ETH has fallen about 57% from its August 2025 peak of above $4,800 to under $2,000 at the time of writing, according to Coingecko data.

StanChart’s global head of digital assets research, Geoff Kendrick, reaffirmed its price targets of $4,000 by the end of 2026 and $40,000 by 2030, implying a return of the ETH/BTC ratio to its 2021 highs around 0.08.

The call comes as investors debate whether Ethereum’s growing dominance in stablecoins and tokenized real-world assets will eventually translate into stronger returns for ETH itself, despite persistent ETF outflows and weak price performance.

Kendrick likened the current disconnect to Amazon during the dot-com bust, arguing that “everything inside the company was going the right way” even as the stock price slumped.

ETH price over the last year. Source: Coingecko

Max Shannon, senior research associate Europe at Bitwise, agreed with Standard Chartered’s Amazon analogy, telling Cointelegraph it relates to Ethereum’s “lack of narrative” and “lack of value accrual from cheap layer-1 and layer-2 transactions.”

He said value accrual can improve as onchain assets and their velocity grow and as users pay higher gas fees for premium services such as zero-knowledge transactions, pre-confirmations, maximal extractable value, and large institutional trades.

Ethereum main settlement layer for stablecoins and RWAs

The report highlights Ethereum’s role as the main settlement layer for stablecoins and tokenized real-world assets, projecting that stablecoin market capitalization will grow sixfold to about $2 trillion by 2028 and tokenized non-stablecoin assets will expand 50-fold to a similar size, with Ethereum currently hosting roughly half to two-thirds of each market.

Related: Ethereum treasury firms lean on staking as ETF pressure builds: Report

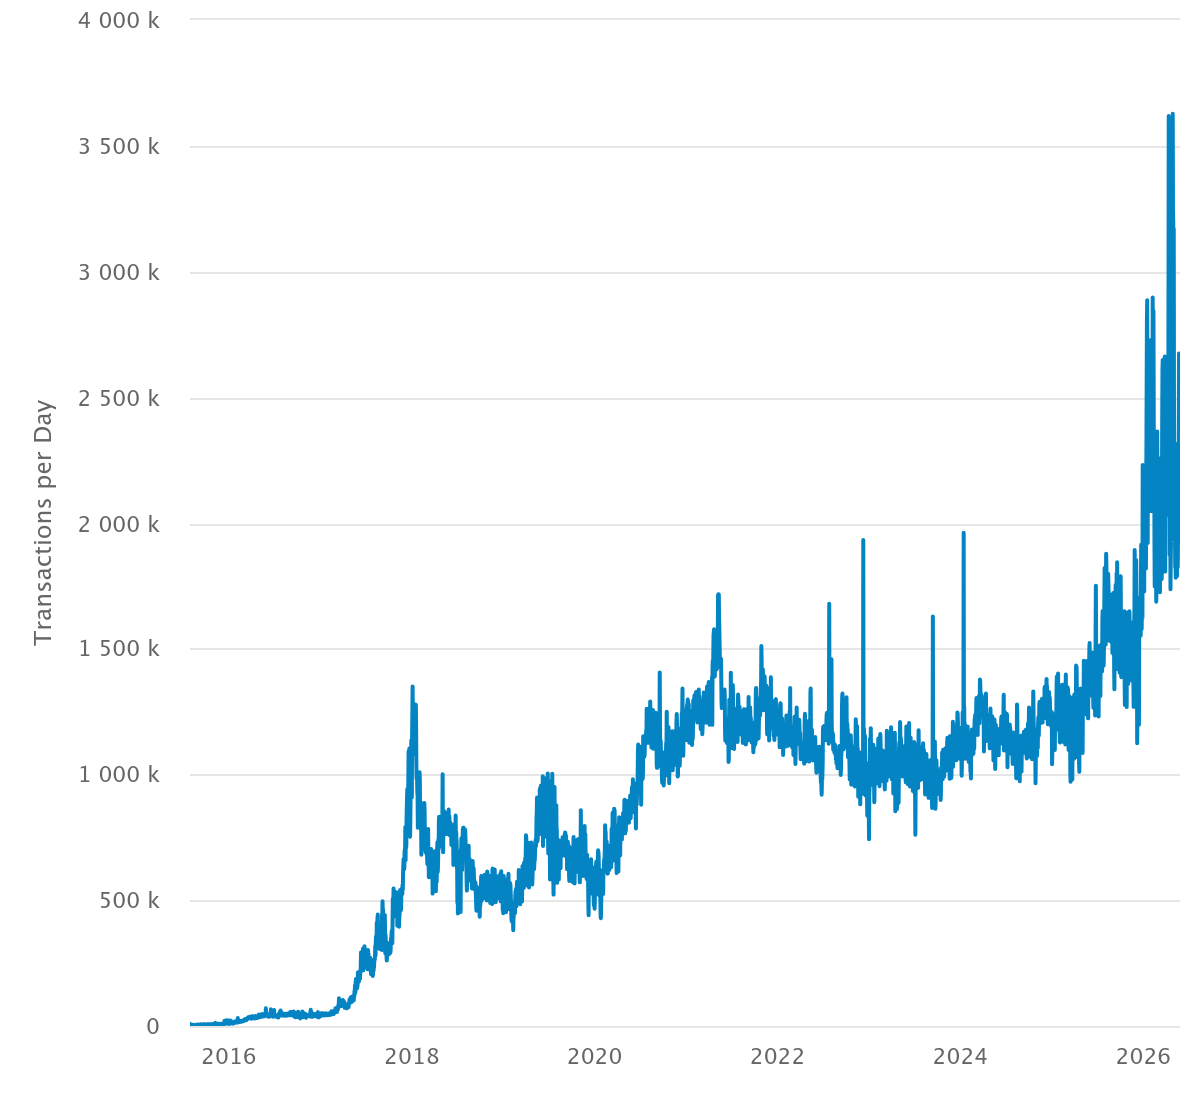
Transactions on Ethereum reached an all-time high of more than 3.6 million on April 28 and have since dropped to around 2.2 million on Thursday, according to Etherscan. Total value locked in decentralized finance has dropped from around $97 billion in August to $41.65 billion on May 27, according to data from DeFiLlama.

Ethereum transactions per day, all time. Source: Etherscan

Justin d’Anethan, head of research at Arctic Digital, a crypto private markets advisory firm, told Cointelegraph that it is “heartwarming to see a traditional bank stick to their thesis,” despite overall disappointing market sentiment. He said that, in crypto, price is “often its own narrative,” and fundamental value is “an afterthought.”

Mixed signals across the market

Other market signals are more nuanced. Bitmine Immersion Technologies, the largest public buyer of ETH by far, currently owning over 5,300,000 ETH, doubled down on its expectations of a supercycle this week, citing Wall Street’s interest in tokenization and artificial intelligence-powered agents.

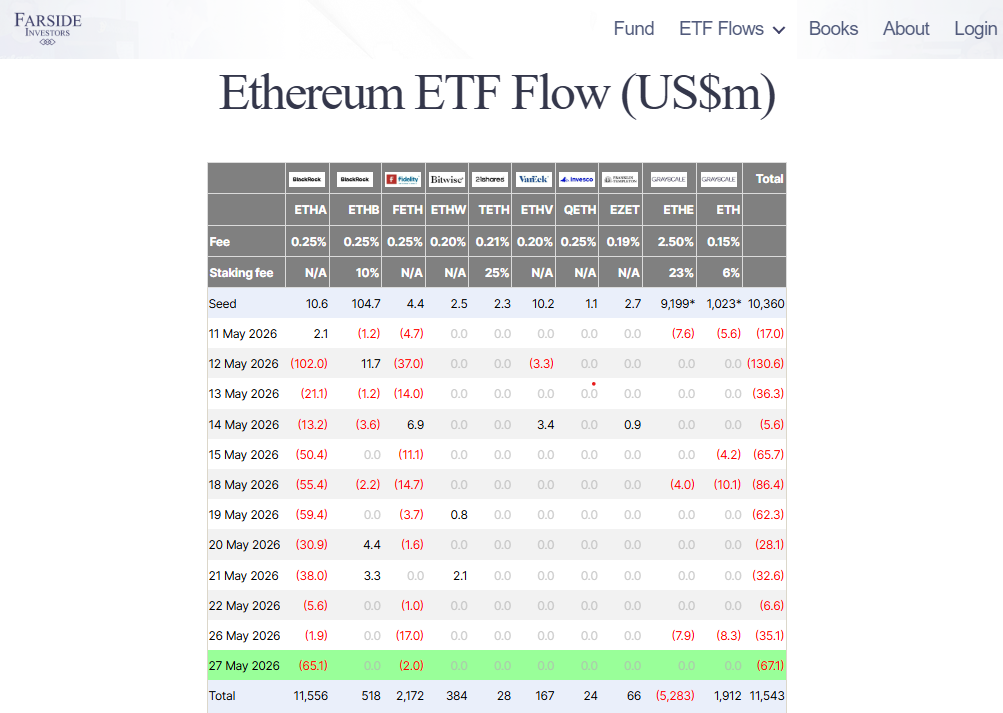
ETH ETF outflows hit 11th consecutive day. Source: Farside Investors

That optimism contrasts with a wave of departures from the Ethereum Foundation and public skepticism from some long-time Ethereum commentators over how much of the network’s growth will ultimately accrue to ETH itself.

US spot ETH exchange-traded funds add another layer to the picture. Farside ETH ETF data shows the products posted a $67.1 million net outflow on May 27, marking 11 consecutive days of withdrawals, even after seeing stronger inflow sessions earlier in the year.

D’Anethan said the question remains whether Ethereum’s tailwinds will outpace Bitcoin’s in the long term, pointing out that previous cycles in which altcoins outperformed BTC no longer hold. “It’ll be interesting to see where large trading firms, institutions, sovereign funds and nation-states ultimately place their bets,” he said.

Shannon said that Biwise’s Factor Model shows the momentum has mostly been driven by Bitcoin and that approximately 80% of ETH price variation can be explained by BTC. “Macro, equities and fundamental drivers such as active addresses have all taken a back seat,” he said.

Market Moves: Why is Ethereum Foundation selling? BTC futures warning signs

JPMorgan says debasement trade has fallen out of favor

0

The “debasement trade” that drove strong demand for bitcoin and gold during recent geopolitical tensions is beginning to lose momentum, according to JPMorgan analysts led by Nikolaos Panigirtzoglou.

In a report on Thursday, the bank argued investors have started pulling capital from both bitcoin and gold exchange-traded funds (ETFs) at the same time as institutions reduced exposure in futures markets tied to both assets.

That shift signals a broader retreat from macro hedge trades that became popular earlier this year amid fears of inflation and global instability stemming from tensions in the Middle East.

Bitcoin ETFs have seen significant outflows over the past two weeks, according to data from Farside Investors, in line with gold ETFs, while positions in CME bitcoin and gold futures have weakened over the same period.

Panigirtzoglou argued that the move does not appear to reflect investors rotating from bitcoin into gold, but rather that both assets are seeing softer demand at the same time.

“Bitcoin had been the main manifestation of the debasement trade since the start of the Iran conflict,” the report said.

The debasement trade refers to investor positioning in assets viewed as stores of value during periods of inflation fears or currency weakness. Bitcoin and gold often benefit when traders expect governments and central banks to increase spending, expand debt or keep monetary policy loose.

Those concerns intensified earlier this year after renewed conflict in the Middle East pushed oil prices higher and heightened worries about inflationary pressures returning.

JPMorgan said the recent pullback may reflect growing expectations that tensions between the United States and Iran could ease.

The report suggested investors may be positioning ahead of a possible diplomatic agreement between the two countries, reducing the need for inflation and geopolitical hedges that had supported bitcoin and gold.

Disciplined AI agents are the disruptor needed to break the exchange churn model

0

All within a matter of weeks, Anthropic unveiled new agents for finance, Circle launched nanopayments, MoonPay launched a debit card for agents and Gemini launched agentic trading, signaling the agentic finance fight is here. Whilst the products are new, the underlying business model remains the same. Every exchange and brokerage earns more when customers trade more, and the data on what that does for customer portfolios is unambiguous. Ultimately, agentic rails have arrived faster than incentives have changed.

The perverse incentives exchanges hope you miss

The conflict is structural to the industry. Brokerages and exchanges don’t need customers to win, they need them to keep trading. Crypto exchanges and neobrokers made trading faster, cheaper and frankly, more addictive. The commercial reality is that banks profit when you stay, exchanges profit when you trade, and AI models profit when you prompt. The agent you can trust with your hard-earned capital sits outside all three. An independent agent paid only when the customer’s portfolio wins threatens the current incentive structure of brokerages and exchanges.

The truth is, zero-commission trading isn’t free. In 2025, U.S. market makers paid more than $4.9 billion for order flow in U.S. equity and options, up from approximately $3.8 billion in 2021 across the 12 largest U.S. brokerages. The same principle applies to crypto. The derivatives volume from Q1 of 2026 reached about $18.6 trillion, 70% of global crypto trading, with perpetuals dominating spot trading. Exchange economics reward trading velocity over disciplined decision-making.

At peak, Robinhood relied on more than 75 percent of its revenue from payment for order flow (PFOF), the hidden backbone of “free” trading, in which market makers pay brokers to route customer orders. Every broker using this incentive model needs customers to trade often, even though frequent trading works against long-term returns.

Advisory isn’t better. Robo-advisors charge 0.25 percent of assets a year, whether the account is up or down. Human advisors charge around 1 percent, billed against the principal even in down years. The extraction is built into the model by design: the advisor gets paid even when the customer loses.

Less exchange friction makes bad trades easier to repeat

The harsh truth is that exchanges need customers to trade more, not win. When retail investors lose, the exchanges still get paid. PiP World research found 74% to 89% of retail users lose money trading. Platforms charge at every step, and an AI-enabled exchange could just route you back to the same losing trade faster.

The April 14 SEC approval of FINRA’s elimination of the Pattern Day Trader rule removed the $25,000 minimum-equity friction. Removing the friction results in more trades, which creates more order flow. More order flow means more money for the broker, whether the customer’s profit and loss (P&L) is up or down.

Enter AI agents, paid to improve customer P&Ls

The disruptor to this vicious cycle for retail traders is the agent built to do what the existing exchange model avoids: trade less, size down, wait and protect customers from their worst impulses. In volatile markets, the best move is often refusing the bad trade, cutting exposure before emotion takes over. Ultimately, holding discipline when the market wants a reaction. Discipline is hard to sell for an exchange because it shrinks order flow. An agent that earns by protecting customer P&Ls breaks the current incentive model.

The next battleground is who profits from the agents’ order flow

Regulators are squeezing the old “free trading” model. The EU’s PFOF ban takes effect June 30, 2026, removing the revenue line behind “free” trades for German and Austrian neobrokers. Trade Republic, a European savings platform, has already found another route to secure a BaFin license to internalize order flow.

Whilst TradFi scrambles to patch the leaks, crypto builders are racing to rebuild onchain rails for AI agents. In markets with tiny spreads, fragmented liquidity and millisecond execution, agents transact via nanopayment infrastructure like Circle’s protocol. Gas-free trading on perpetual DEX Hyperliquid cuts friction, but maker-taker fees still apply. The real fight ahead isn’t who removes friction, but who profits when agents start hammering these frictionless rails with high-frequency trading.

Independent programmable agents are better middlemen

The exchanges and brokers have spent years making money from customers trading more, understanding less and absorbing tiny costs they barely notice. Every agent built by an exchange will inherit the exchange’s incentives. Would an exchange build an agent that sends trades through a cheaper competitor’s rails? Not voluntarily.

Whereas an independent agent has one job: grow and protect the customer’s portfolio, routing trades where they work hardest for the customer. Programmable incentives encoded into smart contracts tie the agent’s incentives to portfolio gains. The customer can see where the money goes, verify what the agent gets paid, when and why. With independent agents, the customer keeps more of the value that used to leak to the exchange through order flow, spread markups and idle-cash interest onto the exchange.

The agent is rewarded for disciplined trading, not constant trading. It can trade often when the signal is strong, cut exposure when risk rises and sit out when the market is just noise. The first agentic platform that proves this alignment onchain will give retail investors a fairer counterparty, whose economics finally move in the same direction as theirs.