Home Blog Page 236

Bitmine (BMNR) slows purchase pace, buying $53 million in ETH

0

Bitmine Immersion (BMNR), the largest publicly-traded Ethereum treasury firm, bought 26,497 ether (ETH) last week, sharply reducing the pace of accumulation after making its largest purchase of 2026 just a week earlier.

The latest acquisition, worth roughly $53 million at current ETH prices, lifted Bitmine’s holdings to nearly 5.42 million tokens, or approximately 4.49% of ether’s circulating supply, according to a Monday company update.

The purchase was down more than 75% from the prior week’s 120,000 ETH haul.

The slowdown comes after Thomas “Tom” Lee, chairman of Bitmine, said in May at Consensus 2026 that the company planned to moderate accumulation as it was rapidly approaching its long-term goal of owning 5% of ETH’s supply.

Despite the slower pace, Bitmine remains one of the few large digital asset treasury firms still actively adding to its crypto holdings. Even Michael Saylor’s bitcoin juggernaut Strategy (MSTR) sold $2.5 million bitcoin last week. Bitmine has acquired more than 1 million ETH since the start of the year and now sits about 90% of the way toward its stated goal of controlling 5% of the network’s supply.

“ETH prices are not reflecting the strengthening of Ethereum fundamentals,” Lee said in Monday’s statement. “But then again, this is not surprising given we are in the early stages of crypto spring.”

Bitmine’s total crypto and cash holdings stood at $11.6 billion as of May 31. In addition to its ETH treasury, the company held 203 bitcoin, $446 million in cash, and stakes in Beast Industries and Eightco Holdings.

The firm has increasingly focused on generating income from its holdings through staking. The company estimates its staking operations generate roughly $258 million in annualized revenue, with projected rewards approaching $300 million annually through its MAVAN staking platform.

Japan’s ruling party supports crypto ETF trading, yen-based stablecoins

0

Japan should create a legal framework for trading cryptocurrency exchange-traded funds (ETFs), the ruling Liberal Democratic Party (LDP) said, according to a Reuters report on Monday.

A party panel on promoting blockchain technology submitted the proposal to Finance Minister Satsuki Katayama, also saying the state should promote usage of yen-based stablecoins.

“Crypto-ETFs would provide investors with easy-to-understand ways of investment,” the proposal said, according to Reuters’ report.

The country’s cabinet approved a draft amendment to classify crypto as a financial product in April, having previously treated it as a payment tool.

Japan would be joining other major markets such as the U.S. and Hong Kong in offering ETFs as a means to gain exposure to the crypto market without having to buy and store the underlying assets themselves.

Attempts are already underway to develop and promote yen-based stablecoins, which are digital tokens pegged to the value of a traditional financial asset, such as a fiat currency.

The $315 billion market is dominated by tokens pegged to the dollar, prompting concerns by policymakers in countries outside the U.S. that dollar dominance could circumvent their own banking and payments systems.

Strategy’s bitcoin sale triggers fierce debate over Michael Saylor’s true commitment

0

For years, Strategy (MSTR) Executive Chairman Michael Saylor insisted he would never sell bitcoin .

Yet on Monday, the largest company disclosed that it sold 32 bitcoin last week, its first sale in four years. The announcement prompted questions about whether one of bitcoin’s most prominent corporate advocates was changing course.

Most analysts don’t think so. While the transaction sparked debate among investors, they largely agree that the sale was too small to alter Strategy’s long-term bitcoin accumulation strategy.

The company on Monday said that it sold 32 bitcoin between May 26 and May 31 at an average price of $77,135, generating roughly $2.5 million to help fund dividend payments on STRC, its high-yielding perpetual preferred stock known as Stretch. Strategy still held more than 843,700 BTC at the end of May, meaning the sale represented about 0.004% of its total holdings.

While the announcement initially fueled concerns that Executive Chairman Michael Saylor was backing away from his long-held commitment to accumulating bitcoin, several analysts argued that the interpretation misses the bigger picture.

‘Economically immaterial’

TD Cowen analyst Lance Vitanza said reports suggesting Strategy had become a meaningful seller of bitcoin were overblown.

“Headlines suggesting that Strategy has meaningfully reduced its bitcoin position are, in our view, misleading,” Vitanza wrote in a research note. “The transaction was economically immaterial and does not alter the core accumulation thesis.”

Vitanza noted that management has discussed the possibility of limited bitcoin sales on several recent occasions as part of a broader financing strategy. He added that TD Cowen’s model already anticipated small tactical sales and therefore made no changes to its bitcoin accumulation assumptions or its $400 price target on the stock.

The analyst also pointed to signs that Strategy is rebuilding its cash position. The company also sold 801,944 shares of common stock and used part of the proceeds to replenish cash reserves after repurchasing $1.5 billion of convertible debt at a discount.

‘Viable backstop’

Benchmark analyst Mark Palmer reached a similar conclusion about the significance of the sale itself, saying he does not expect bitcoin disposals to become a primary source of funding for dividends.

“We do not expect Strategy to use bitcoin sales as a primary means of funding dividends on STRC and its other perpetual preferred stock issues,” Palmer said. “It is far more likely that the company will continue to replenish its cash reserve through equity issuance and then use reserve funds to pay dividends.”

Palmer, however, argued that the sale could change how investors view Strategy’s bitcoin holdings. “Now, investors should view Strategy’s bitcoin holdings as providing a viable backstop for the funding of preferred dividends,” he said.

Supporting shareholders

Others viewed the transaction as a more meaningful signal.

Risk Dimensions CIO Mark Connors said the move demonstrates that Strategy is willing to prioritize the health of its capital structure over maintaining a strict no-sale stance on bitcoin.

“By selling bitcoin, Saylor has stated two things,” Connors said. “First, we will support our shareholders and creditors in every way… including by selling bitcoin.” “Second, Saylor and Strategy have prioritized the health and perception of health of the MSTR capital structure over being a diamond-handed OG.”

The differing interpretations highlight the key question now facing investors.

Analysts broadly agree that the 32-BTC sale was immaterial. What remains up for debate is whether it was simply a routine treasury decision or an early signal that Strategy’s approach to managing its vast bitcoin reserves is becoming more flexible.

Strategy is lower by 5% on Monday, while bitcoin has fallen back to a near two-month low of $71,000.

Ethereum’s Vitalik Buterin is rethinking how DeFi handles market crashes

0

Ethereum co-founder Vitalik Buterin is exploring a new way to build crypto investment products that could reduce one of decentralized finance’s biggest risks: sudden liquidations.

In a research post published Monday, Buterin proposed creating index-tracking assets using options contracts rather than the debt-based structures that underpin much of DeFi today. The idea is to allow users to gain exposure to a basket of crypto assets, similar to an index fund, without relying on collateralized debt positions (CDPs), which can be wiped out when markets move sharply.

“What if we use options as the base of DeFi, instead of CDPs and liquidations?” Buterin wrote in a post shared on X.

Under today’s DeFi model, users typically borrow against crypto collateral to create synthetic assets or stablecoins. If the value of that collateral falls too quickly, positions can be automatically liquidated, often triggering cascades of forced selling during periods of market stress.

Buterin argued an options-based system could replace that abrupt “you get liquidated” dynamic with a smoother process. Rather than instantly losing a position when prices move against a trader, exposure would gradually diverge from a target allocation, potentially making the system more resilient during periods of volatility.

A key advantage, according to Buterin, is that the design could function using slower-moving price oracles, the data feeds that tell DeFi protocols what assets are worth. Most DeFi applications today rely on near real-time oracle updates, which can become targets for manipulation during periods of market turbulence.

By contrast, Buterin said an options-based framework could work with “slow oracles” similar to those used by prediction markets. That could reduce the risk of protocols acting on incorrect price data and lessen the need for split-second automated liquidations.

The proposal is particularly relevant to algorithmic stablecoins, which have historically depended on oracle systems and collateral mechanisms that can fail under stress. Buterin said he would feel “much safer” holding algorithmic stablecoins built on an options-based structure than one that depends on real-time oracle feeds that could potentially be manipulated.

The idea comes with tradeoffs. Buterin acknowledged that such a system would require regular portfolio rebalancing and that it remains unclear whether those adjustments can be made cheaply and efficiently enough to avoid excessive trading costs or slippage.

The concept remains theoretical and has not been implemented on Ethereum. Still, it reflects a broader effort by Buterin to rethink the foundations of DeFi and develop systems that prioritize robustness over leverage.

Read more: Buterin says Ethereum Foundation will shrink, sell less ETH, and focus on ‘CROPS’

Vitalik Buterin Proposes Options-Based DeFi to Replace Liquidation-Driven Debt Model

0

Ethereum co-founder Vitalik Buterin proposed splitting 1 ETH into two paired option assets that always sum back to 1 ETH, eliminating forced liquidations and letting synthetics rely on slow, prediction-market-style oracles.

Ethereum co-founder Vitalik Buterin on Monday proposed rebuilding decentralized finance on options contracts instead of collateralized debt, a shift that would eliminate forced liquidations and let synthetic assets run on slow, prediction-market-style oracles rather than the real-time price feeds driving most of DeFi today.

The proposal, Building index-tracking assets on top of options instead of debt, published on the Ethereum Research forum, defines two assets P and N with strike price S and maturity date M. A (P, N) pair is minted from one ETH and can be redeemed for one ETH at any time. At maturity, an oracle resolves the index to x; P receives `min(1, S/x)` ETH and N receives `max(0, 1 – S/x)` ETH. Because the two payoffs always sum to 1, “there is no possibility of liquidation,” Buterin wrote. The post credits feedback from Lighter founder Vladimir Novakovski and developers of the Curve decentralized exchange.

Liquidation cascades have been DeFi’s dominant failure mode for half a decade. On March 12, 2020, ether fell roughly 43% in hours, MakerDAO keeper bots failed to bid, and a single bot walked off with $8.32 million of ETH for zero DAI. Maker took on a $6.65 million Dai shortfall and later paid $1.16 million to settle a class action from vault owners. Every CDP-based protocol since has been tuned to the assumption that bidders show up; Buterin’s design removes the auction entirely.

What the Mechanism Changes

“The problem with relying on liquidations is that liquidations depend on real-time oracles,” the post argues. “You cannot use what is by far the most effective technique to make a safe and cheap oracle: put a prediction market in front of a safe but expensive oracle, and only use that oracle in case of serious disagreement.”

Splitting one ETH into a P/N pair fixes that — the system is solvent by construction, so the oracle can resolve at maturity instead of every block. Buterin equates the design to scalar prediction markets on platforms like Seer, letting the instrument share oracle infrastructure with markets that have run for years.

Where Options-DeFi Already Exists

The primitive is not net-new. Panoptic runs perpetual, oracle-free options on Ethereum mainnet by tokenizing Uniswap v3 LP positions. Opyn’s Squeeth wraps a power-perp on ETH-squared exposure. Premia operates an options AMM with portfolio margin. What Vitalik proposes sits one layer higher: a synthetic that tracks a price index by stacking options rather than borrowing against collateral.

The user playbook is to hold deep in-the-money options and rotate them into lower strikes as the price gets close. Rebalancing could run through an automated DAO wrapper or through a local daemon — the latter, Buterin notes, “reduce[s] the user’s MEV risks, because the transaction is not visible ahead of time.”

The 2% Tax

The cost is drift. Holders of P don’t get a clean dollar peg; they get a quadratic deviation from their target exposure that grows with the gap between current price and strike. Buterin pegs the realistic range at “standev ~1-4% per year” and reframes it as a feature. The design is “unusable as an ‘accounting stablecoin'” — a counterparty or tax authority won’t treat one P as one dollar — but works “in the context of ‘I want price stability’,” meaning pre-funding a known share of future expenses.

The bigger competitive risk, Buterin warned, is rebalancing itself. “It is very easy to lose 2% per year or more from multiple rounds of slippage, and this is the largest risk by which this whole scheme might become uncompetitive.” His proposed mitigation exploits the fact that rebalancing users have very low time preference — they don’t care whether they trade today or three days from now — to build “an ideal market structure that minimizes slippage far more than traditional AMMs do.”

The post is research-grade rather than a deployment plan, and no protocol has yet committed to building on the spec.

Bitcoin Derivatives Show Bulls Making Moves Despite $70K Sell-off

0

Key takeaways:

  • Whale’s bullish positioning in the Bitcoin derivatives market is failing to counter the heavy spot selling pressure. 
  • The slight discount on USDT indicates capital is exiting to fiat, exposing the Bitcoin futures leverage risks.

Bitcoin (BTC) dropped below $71,000 on Monday for the first time in seven weeks, liquidating $276 million in leveraged bullish positions as traders reduced their positions amid renewed military action between the US and Iran. Despite this heightened risk aversion, whales and market makers increased their bullish exposure in the Bitcoin derivatives markets.

Bitcoin top traders’ long-to-short position at Binance & OKX. Source: CoinGlass

At Binance, the long-to-short ratio among top traders surged to 1.4x from 1.1x one week prior. These institutional players have gradually accumulated long positions since Bitcoin broke below $76,500 on Tuesday. Meanwhile, top traders at OKX initially expanded their short positions between Thursday and Sunday, but reversed course on Monday as their long-to-short ratio jumped to 1.9x.

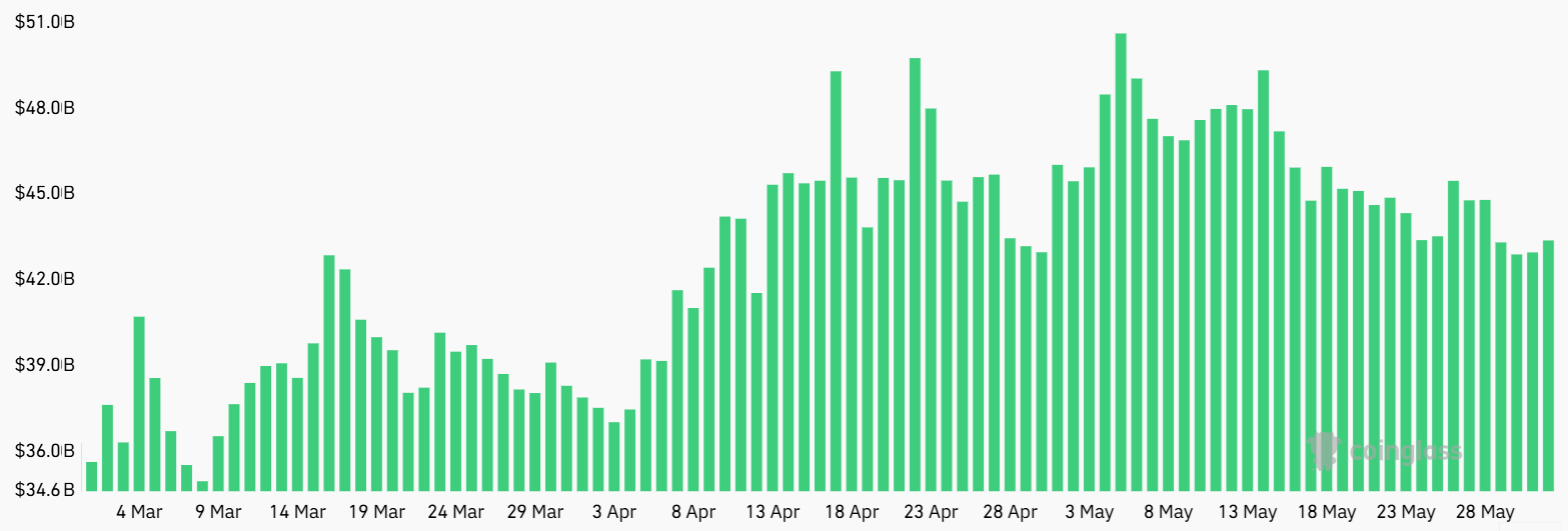
Bitcoin futures aggregate open interest at major exchanges, USD. Source: CoinGlass

Aggregate open interest for Bitcoin futures across major exchanges stood at $43.5 billion on Monday, remaining flat compared to the previous week. Despite the forced liquidations, traders did not rush to close their positions at a loss. Nonetheless, further analysis is required to determine whether bullish traders are relying excessively on leverage to sustain their current positions.

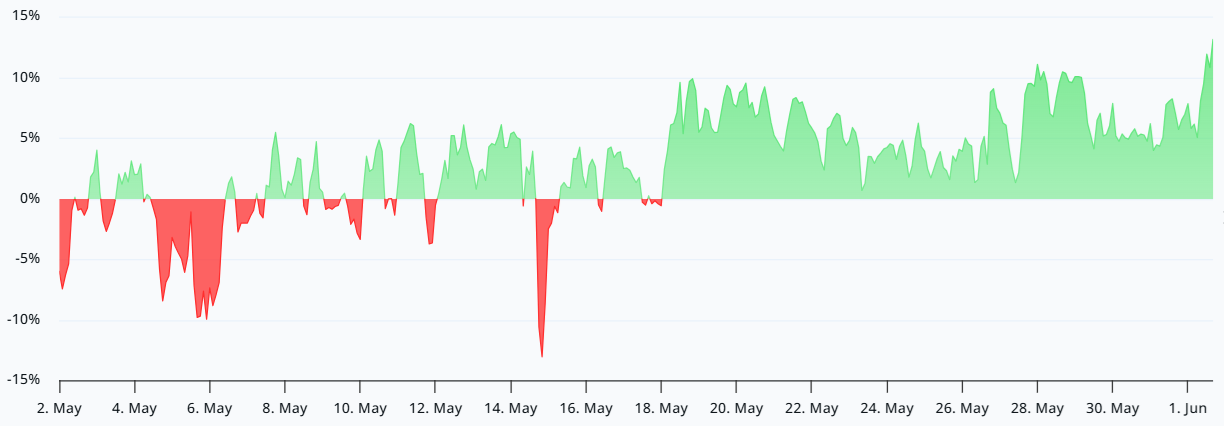
Bitcoin perpetual futures annualized funding rate. Source: Laevitas

The annualized funding rate for Bitcoin perpetual futures jumped above the neutral 6% to 12% range for the first time in over six months. This data hints at growing confidence among bulls, but it also heightens the risk of cascading liquidations should Bitcoin’s price fall further. Nonetheless, a modest 13% funding rate remains far from signaling market desperation.

Bitcoin spot ETF outflows contrast with AI bulls

While the weakness in Bitcoin’s price can be partially attributed to rising oil prices, the tech-heavy Nasdaq Composite Index managed a 0.5% gain on Monday. Brent crude oil jumped to $95 per barrel after US officials stated that Iran had fired two ballistic missiles overnight. Additionally, Israel carried out a military incursion into southern Lebanon over the weekend.

Investors’ intense focus on the AI sector has also contributed to capital outflows from the cryptocurrency market. On Monday, Anthropic, the developer of Claude AI, announced that it had confidentially filed its initial public offering (IPO) prospectus. Separately, Elon Musk’s SpaceX officially filed its own IPO prospectus.

Related: Bitcoin dip buyers place $500M in bids as $70K retest looms

USDT stablecoin / USD at major exchanges. Source: TradingView and Cointelegraph

Tether’s USDT stablecoin traded at a slight 0.10% discount over the past week, signaling capital outflows into traditional fiat currency. This data aligns with the $3.46 billion in net outflows from US-listed spot Bitcoin ETFs since May 13. Ultimately, heavy selling pressure in spot markets is likely the driver behind Bitcoin’s recent price correction.

It is still too early to claim that pro traders are flipping bullish based purely on the long-to-short ratio, especially following the recent spike in the perpetual futures funding rate. With no clear evidence that cryptocurrency market outflows are slowing, traders may remain skeptical of a sustainable short-term bull run, despite the relative strength in Bitcoin derivatives data.

Strategy’s $2.5 million BTC sale and lessons from the first time MSTR sold in December 2022

0

When Strategy (MSTR) disclosed that it sold 32 bitcoin in May, memories were jogged of the company’s first-ever bitcoin sale in December 2022.

Both events generated headlines questioning whether Michael Saylor’s company was backing away from its long-standing bitcoin accumulation strategy. Both prompted scrutiny of the firm’s finances. Both represented extraordinarily rare moments in the history of the world’s largest corporate bitcoin holder.

Yet the more useful lesson from the 2022 sale may be that investors should be cautious about reading too much into any single disposal.

Late 2022 was one of the most tumultuous periods in cryptocurrency’s history, the culmination of the “crypto winter” that unfolded that year which came to a head with the collapse of exchange FTX in early November.

From a high of around $69,000 a year earlier, bitcoin had fallen over 75% to below $16,000.

“Of course bitcoin isn’t going to zero,” geopolitical strategist Peter Zeihan wrote on X on Nov. 12. “We have carbon taxes in some places. Bitcoin is going negative.”

The following month, MicroStrategy as it was then known, sold 704 BTC for roughly $11.8 million as bitcoin traded near $16,500. The company said the transaction was designed to harvest tax losses that could offset future gains.

Michael Saylor’s firm then bought 810 BTC two days later, leaving its overall bitcoin position larger than before.

At the time, however, many critics saw something more consequential.

Gold advocate Peter Schiff argued the sale exposed cracks in Saylor’s unwavering commitment to bitcoin and suggested it could be the first step toward a broader liquidation.

“Shares of MicroStrategy just made a new 52-week low, down 90% from the record-high in Feb. 2021,” he wrote in a separate post. “Don’t make the mistake of thinking 90% off is a good buy. This isn’t just a sale, it’s a going-out-of-business sale.”

History unfolded differently. Rather than marking the beginning of a selling cycle, the December 2022 transaction occurred near the bottom of the bear market. Over the following years, bitcoin rebounded to record highs while Strategy dramatically expanded its holdings. The company’s stash has since grown from roughly 132,500 BTC at the end of 2022 to more than 843,000 BTC today.

That experience could tempt investors to dismiss the latest sale as equally irrelevant. But doing so risks overlooking how much the company itself has changed.

The Strategy of 2022 was largely a leveraged bitcoin holder. The Strategy of 2026 is a far more complex financial vehicle built around bitcoin ownership. The company now manages a capital structure that includes convertible debt, common-equity issuance programs and multiple preferred-stock offerings designed to attract different classes of investors.

Against that backdrop, selling 32 BTC, worth roughly $2.5 million and representing less than 0.004% of its holdings, is financially insignificant. But the transaction may reflect a broader reality: bitcoin sales are no longer unthinkable within Strategy’s operating model.

“This may just be the beginning of much larger sales to come,” Schiff wrote on X following news of Strategy’s second sale. “Plus, if MSTR just stops buying more bitcoin that’s a huge problem for bitcoin.”

That does not mean the company is abandoning accumulation. Strategy continues to buy bitcoin aggressively and raise capital to fund additional purchases. But unlike in 2022, the question is no longer whether Strategy will ever sell bitcoin.

The more relevant question is whether future sales remain rare exceptions or become another routine tool in the management of an increasingly sophisticated bitcoin treasury empire.

Bitcoin Volatility Drops 56% As Analysts Watch For 20% Price Move

0

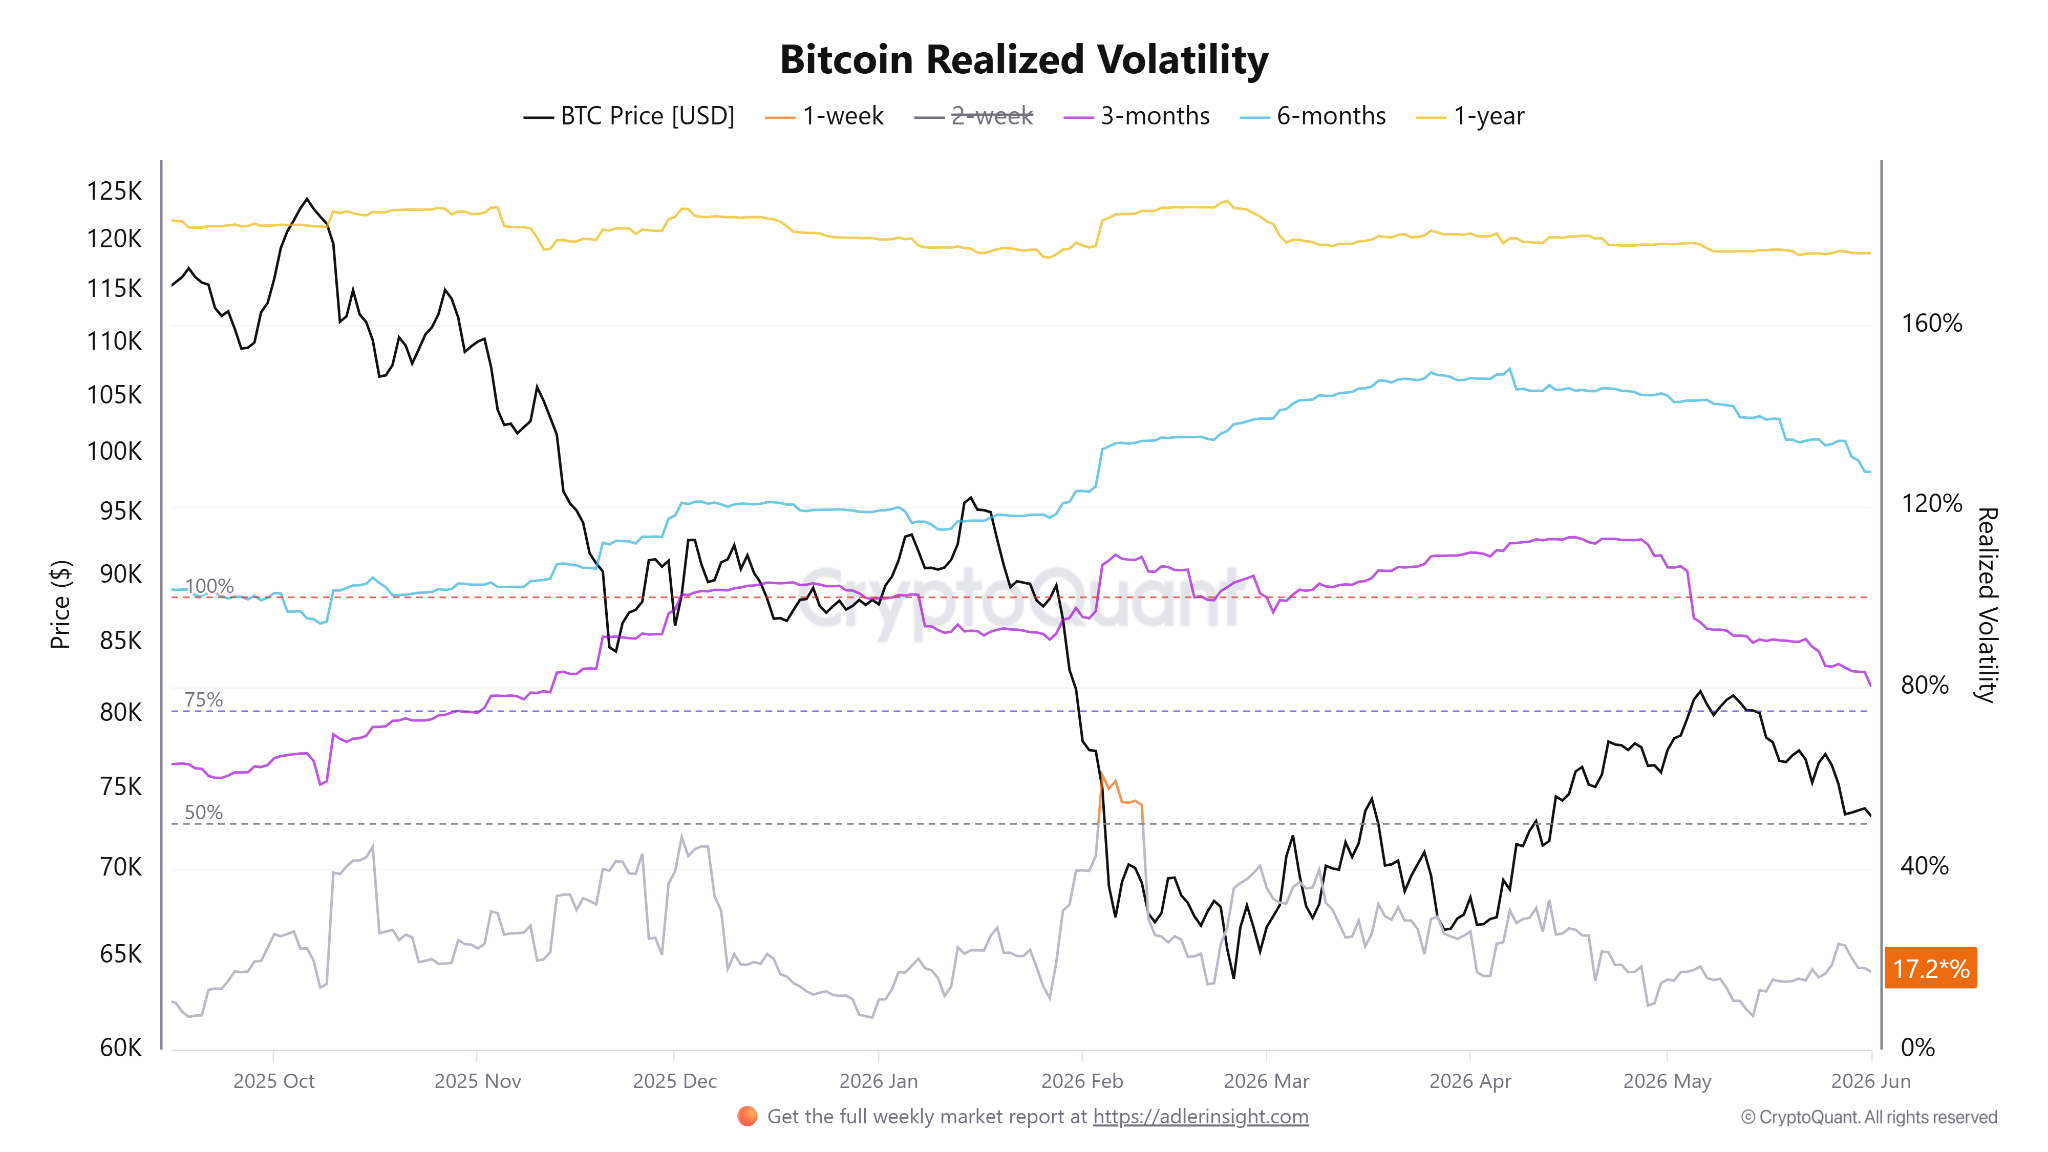
Bitcoin’s realized volatility has fallen to 17.2%, one of its lowest levels in recent months. Multiple Bitcoin analysts have said that long periods of price compression, alongside declining volatility, have historically preceded double-digit rallies. 

Bitcoin realized volatility is down 56% in Q2

Bitcoin researcher Axel Adler Jr. said that BTC’s one-week realized volatility, smoothed over a 30-day period, has fallen to 17.2% from 39% this quarter, a 56% decline.

Bitcoin realized volatility (one-week). Source: CryptoQuant 

The realized volatility, which measures how much the price has actually moved over a given period, sits well below its long-term median of 40%. Adler explained that such volatility compression may lead to a major price move. 

However, the metric does not indicate direction. Instead, it measures how much momentum is building while the price movement slows.

The long-term volatility gauges tell a similar story. Three-month realized volatility has fallen to 80% from 109% since early April, while six-month realized volatility declined to 127% from 148%. 

The drop across multi-time-frame volatility measures indicates that price movement has become compressed, a condition that may precede larger market moves. 

Bitcoin three- and six-month realized volatility. Source: CryptoQuant

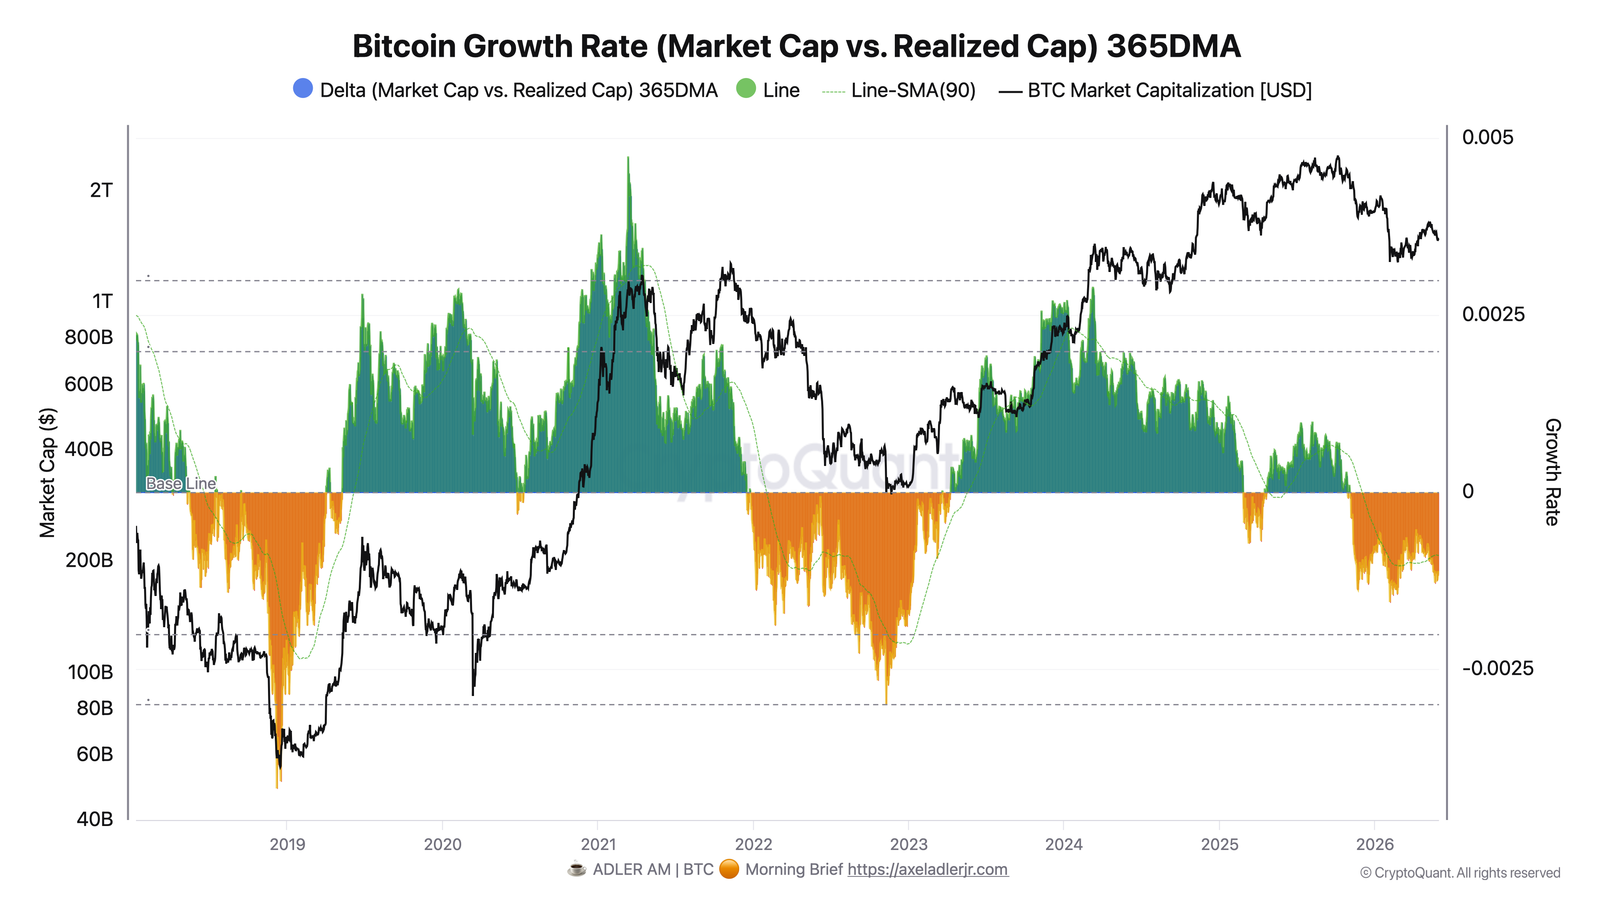
The network valuation data adds another layer. The Bitcoin growth rate metric, which compares market capitalization growth to realized capitalization, has remained negative for more than six months. The delta, or 365-day moving average, recently slipped to -0.0013, indicating that BTC’s market value is growing more slowly than its realized value.

Adler said that the data points to a cooling market. Bitcoin’s price is not rising as quickly as the capital flowing into the network, suggesting investors are becoming more cautious amid reduced market volatility. 

Bitcoin growth rate based on market cap and realized cap. Source: CryptoQuant

Related: Bitcoin price targets $78K as BTC holders defend ‘strongest near-term support’

Bitcoin enters a “tug-of-war” phase, says analyst

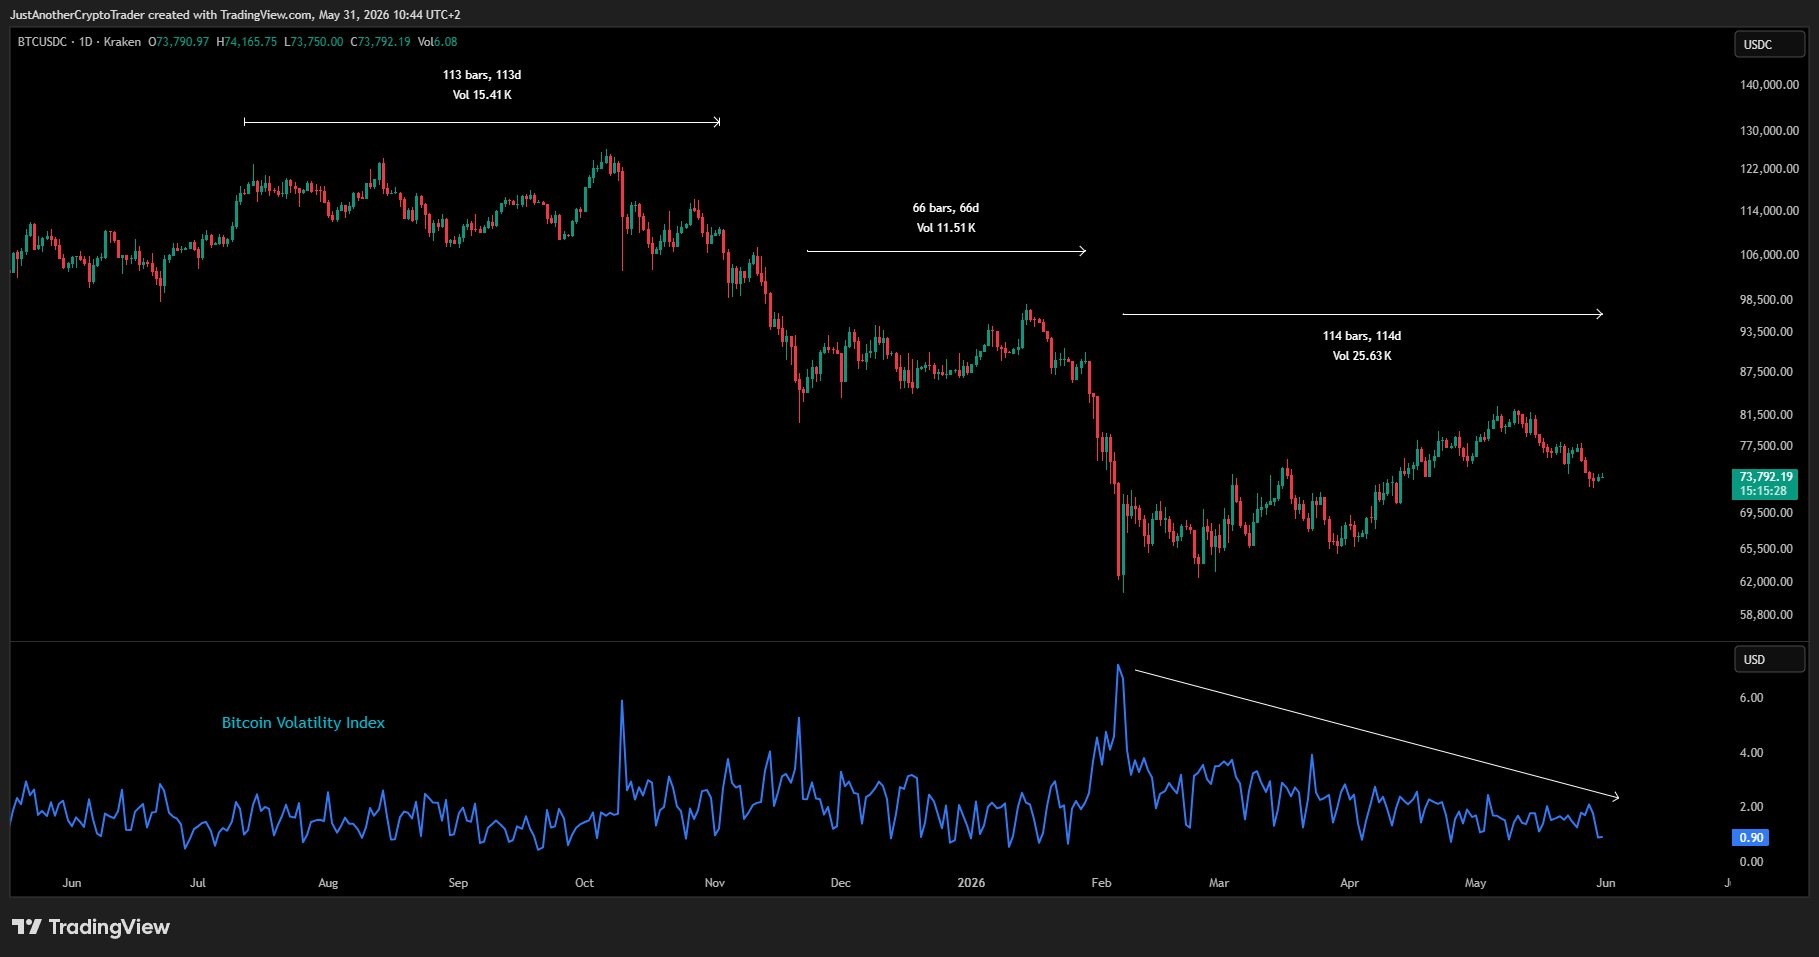
CryptoQuant analyst Maartunn said Bitcoin has spent 114 days trading within a broad range of $60,000 and $80,000, while the Bitcoin volatility index has dropped toward multi-month lows near 0.90.

According to Maartunn, similar periods of compression have historically preceded 10% to 20% moves once the price range breaks.

BTC price and volatility index analysis by Maartunn. Source: X

MN Capital founder Michael van de Poppe remained bullish on BTC, stating the current area as a key support zone. Van de Poppe said, 

“If history repeats itself, that means that we’re going to see two great weeks of upwards momentum for Bitcoin and the end of this correction. It’s a crucial support zone for Bitcoin, which needs to hold in order to prevent a test at $61,000 to happen.”

Meanwhile, CryptoQuant analyst Amr Taha pointed to a growing split in market behavior. Binance’s 30-day Bitcoin inflows rose by roughly $5.6 billion since April across both retail and whale cohorts. Retail inflows increased by $3.6 billion, surpassing the $2 billion rise from whale wallets.

At the same time, wallets holding between 1,000 and 10,000 BTC accumulated 55,450 BTC on May 30, marking their strongest accumulation activity since February. Taha added, 

“For Bitcoin, this points to a tug-of-war phase. Exchange inflows are increasing, which may create near-term selling pressure, but large wallet accumulation is also returning, which could provide underlying support if demand remains strong.”

Related: Trump says Iran will ‘work out well’: Five things to know in Bitcoin this week

Saylor’s Strategy (MSTR) sold bitcoin (BTC). These crypto treasuries are still buying

0

Strategy (MSTR), the company whose bitcoin accumulation strategy inspired a new generation of so-called digital asset treasury firms, sold BTC for the first time since December 2022, offloading roughly $2.5 million worth of tokens.

The move came as the scheme has faced major headwinds since gaining popularity last year.

Dozens of companies raised capital through stock and debt offerings to buy bitcoin, ether (ETH) and other cryptocurrencies, aiming to replicate Michael Saylor’s playbook. The model worked for a while last year as crypto prices surged and treasury stocks traded at premiums to their underlying values.

However, that all changed as crypto markets peaked in October. As token prices fell and treasury stocks slipped below net asset value, many firms lost the ability to raise capital on attractive terms, and some stocks fell more than 90% from their peak. Some stopped buying, while others turned into sellers.

Through all that, Strategy held strong and kept buying as its Executive Chairman, Michael Saylor, continued to advocate for buying and holding.

But that didn’t hold for long. Strategy first alluded to a potential sale earlier in May and then finally reported the first sale on Monday, June 1. With Strategy breaking its accumulation streak and many peers stepping aside, some might think it’s the final nail in the coffin for the treasury firms, as the list of active buyers has now narrowed considerably.

Still buying

However, a few remaining companies continue to buy. Among them is Bitmine (BMNR), Tom Lee’s Ethereum treasury company.

The company purchased roughly $53 million worth of ETH last week and accumulated over 338,000 tokens through May, worth roughly $665 million at current prices. It holds more than 5.4 million ETH, making it the largest corporate holder of the token.

However, Tom Lee said the firm plans to slow its accumulation pace as it approaches its goal of owning 5% of the ETH supply.

Another Ethereum-centric Bit Digital (BTBT) returned to the market in May, buying $20 million worth of ETH. That was the company’s first purchase since October.

Some bitcoin-focused firms are still buying.

Strive (ASST) disclosed acquiring roughly 1,944 BTC in May, spread across multiple purchases, at a cost of about $150 million. Japan’s Metaplanet also reported a purchase in early April, when it acquired 5,075 BTC.

Hyperliquid Strategies (PURR), the treasury firm focused on buying HYPE, the native token of red-hot Hyperliquid blockchain-based exchange and its ecosystem, said it spent $216 million to buy 7.3 million tokens between early December and the end of April. Given HYPE’s surge to record highs, the return on that investment has more than doubled since then.

Despite last week’s sale, Strategy remained one of the largest sources of bitcoin demand through May, purchasing more than 25,000 BTC for over $2 billion.

The sellers

On the other hand, several firms have been reducing crypto holdings recently.

Nakamoto Holdings (NAKA), the bitcoin treasury company led by David Bailey, sold 284 BTC in March, about 5% of its holdings. Empery Digital sold 370 BTC in April to repay a term loan. Genius Group (GNS) said in April it liquidated its remaining 84 BTC to pay down $8.5 million of debt.

Meanwhile, others have abandoned the treasury model entirely.

Forum Markets, formerly known as ETHZilla, shifted its focus to tokenization earlier this year after selling roughly $114 million worth of ether.

VivoPower, which had planned to build an XRP-focused treasury, pivoted to data center and AI infrastructure in February, divesting its Ripple-related investments and XRP holdings.

Read more: Digital asset treasuries must now earn their keep
Digital asset firm Keyrock plans to acquire BlockFills out of bankruptcy

0

Keyrock, a Brussels-based digital asset services firm, is in the process of acquiring bankrupt crypto trading and lending firm Blockfills, according to two people with knowledge of the matter.

A Keyrock spokesperson told CoinDesk that the acquisition is subject to court approval. According to a bankruptcy filing, Keyrock agreed to a purchase price of $3.25 million, and will assume “substantially all” of BlockFills’ assets, certain liabilities, some of its equity interests, customer lists and its proprietary technology and intellectual property.

“We can confirm that, as set out in the official Bankruptcy Court document filed on 26 May 2026, Keyrock SA has been declared the ‘Successful Bidder’ for certain assets of Reliz Technology Group Holdings Inc. and its affiliated debtors,” a Keyrock spokesperson said in a statement.

“A hearing to consider approval of the sale is currently scheduled for June [16,] 2026. In the meantime, parties continue to collaborate on the administrative process to complete the transaction. Furthermore, final completion of the transaction remains subject to final court approval and the appropriate regulatory approvals referenced in Keyrock’s bid,” they added.

BlockFills provides institutional clients with liquidity, financing and risk-management services, including crypto lending and borrowing, derivatives trading, and over-the-counter (OTC) execution. Its customer base includes hedge funds, asset managers, market makers and mining companies. Keyrock is a Brussels-based digital asset services firm that provides market making, liquidity, OTC trading and infrastructure solutions to crypto exchanges, institutions and token issuers.

Representatives for BlockFills did not return a request for comment by press time.

On March 15, Reliz Ltd., the operator of BlockFills, and three affiliated entities filed voluntary Chapter 11 petitions in the U.S. Bankruptcy Court for the District of Delaware. The court filing showed Reliz reporting assets between $50 million and $100 million against liabilities of $100 million to $500 million.

The firm decided to file for bankruptcy after consulting all stakeholders, it said in an official statement at the time.

“After extensive discussions with investors, clients, creditors, and other stakeholders, BlockFills has determined that a voluntary chapter 11 filing is the most responsible path forward in order to preserve the value of the business and maximize recoveries for stakeholders. This filing will allow the firm to implement an orderly restructuring while maintaining transparency and oversight through the court-supervised process,” it said.

CoinDesk reported in February that the Chicago-based firm had suffered losses of roughly $75 million and was seeking either a buyer or emergency financing.

Earlier that the month the company announced that it was suspending customer withdrawals and deposits, citing challenging market and financial conditions. At the time, BlockFills said it was working with investors and clients to restore liquidity and reach a resolution.

According to Blockfills, trading volume exceeded $60 billion in 2025, a 28% increase from the previous year. The firm said it served approximately 2,000 institutional clients and ranked among the more active desks in the institutional crypto lending and borrowing market.

The acquisition comes months after Keyrock raised a Series C round led by SC Ventures, Standard Chartered’s venture capital arm, at a $1.1 billion valuation.

It acquired Turing Capital, a fund manager based in Luxembourg, last fall, in a push to expand into asset and wealth management, it announced in September.

Read more: Crypto trading firm BlockFills files for bankruptcy