Home Blog Page 205

Bitcoin Price Drops Follow BOJ Rate Hikes: Is Another Crash Developing?

0

Since 2024, Bitcoin (BTC) has posted four major corrections after interest rate hikes by the Bank of Japan (BOJ), with declines ranging from 18% to 28%. This dynamic places renewed attention on the BOJ’s June 16 policy decision. 

Data currently point to a variety of pressures on BTC, with BTC whale distribution and exchange inflows possibly carrying more weight than Japanese monetary policy.  

BOJ hikes and Bitcoin drawdowns: Will history repeat?

The relationship between BOJ policy and Bitcoin has gained attention because each rate increase since Japan ended its negative interest rate policy has been followed by a sizable correction. 

Following the March 19, 2024, hike, Bitcoin corrected by 18%. The July 31, 2024, increase preceded a 18.5% decline. 

After the Jan. 24, 2025, hike, Bitcoin fell nearly 25%, while the Dec. 19, 2025, decision was followed by a 28% drawdown. 

Across the four events, Bitcoin’s average decline was 22.4%. 

BTC/USD, one-week chart. Source: Cointelegraph/TradingView

The sell-offs did not occur under identical conditions. The March 2024 correction followed Bitcoin’s breakout to new all-time highs during the spot Bitcoin exchange-traded fund (ETF) cycle. The July 2024 decline followed months of consolidation below peak levels and coincided with the sharp unwind of the yen carry trade, which affected global markets. 

The January and December 2025 drawdowns followed extended rallies and periods of contraction for both BTC spot and futures 30-day demand. 
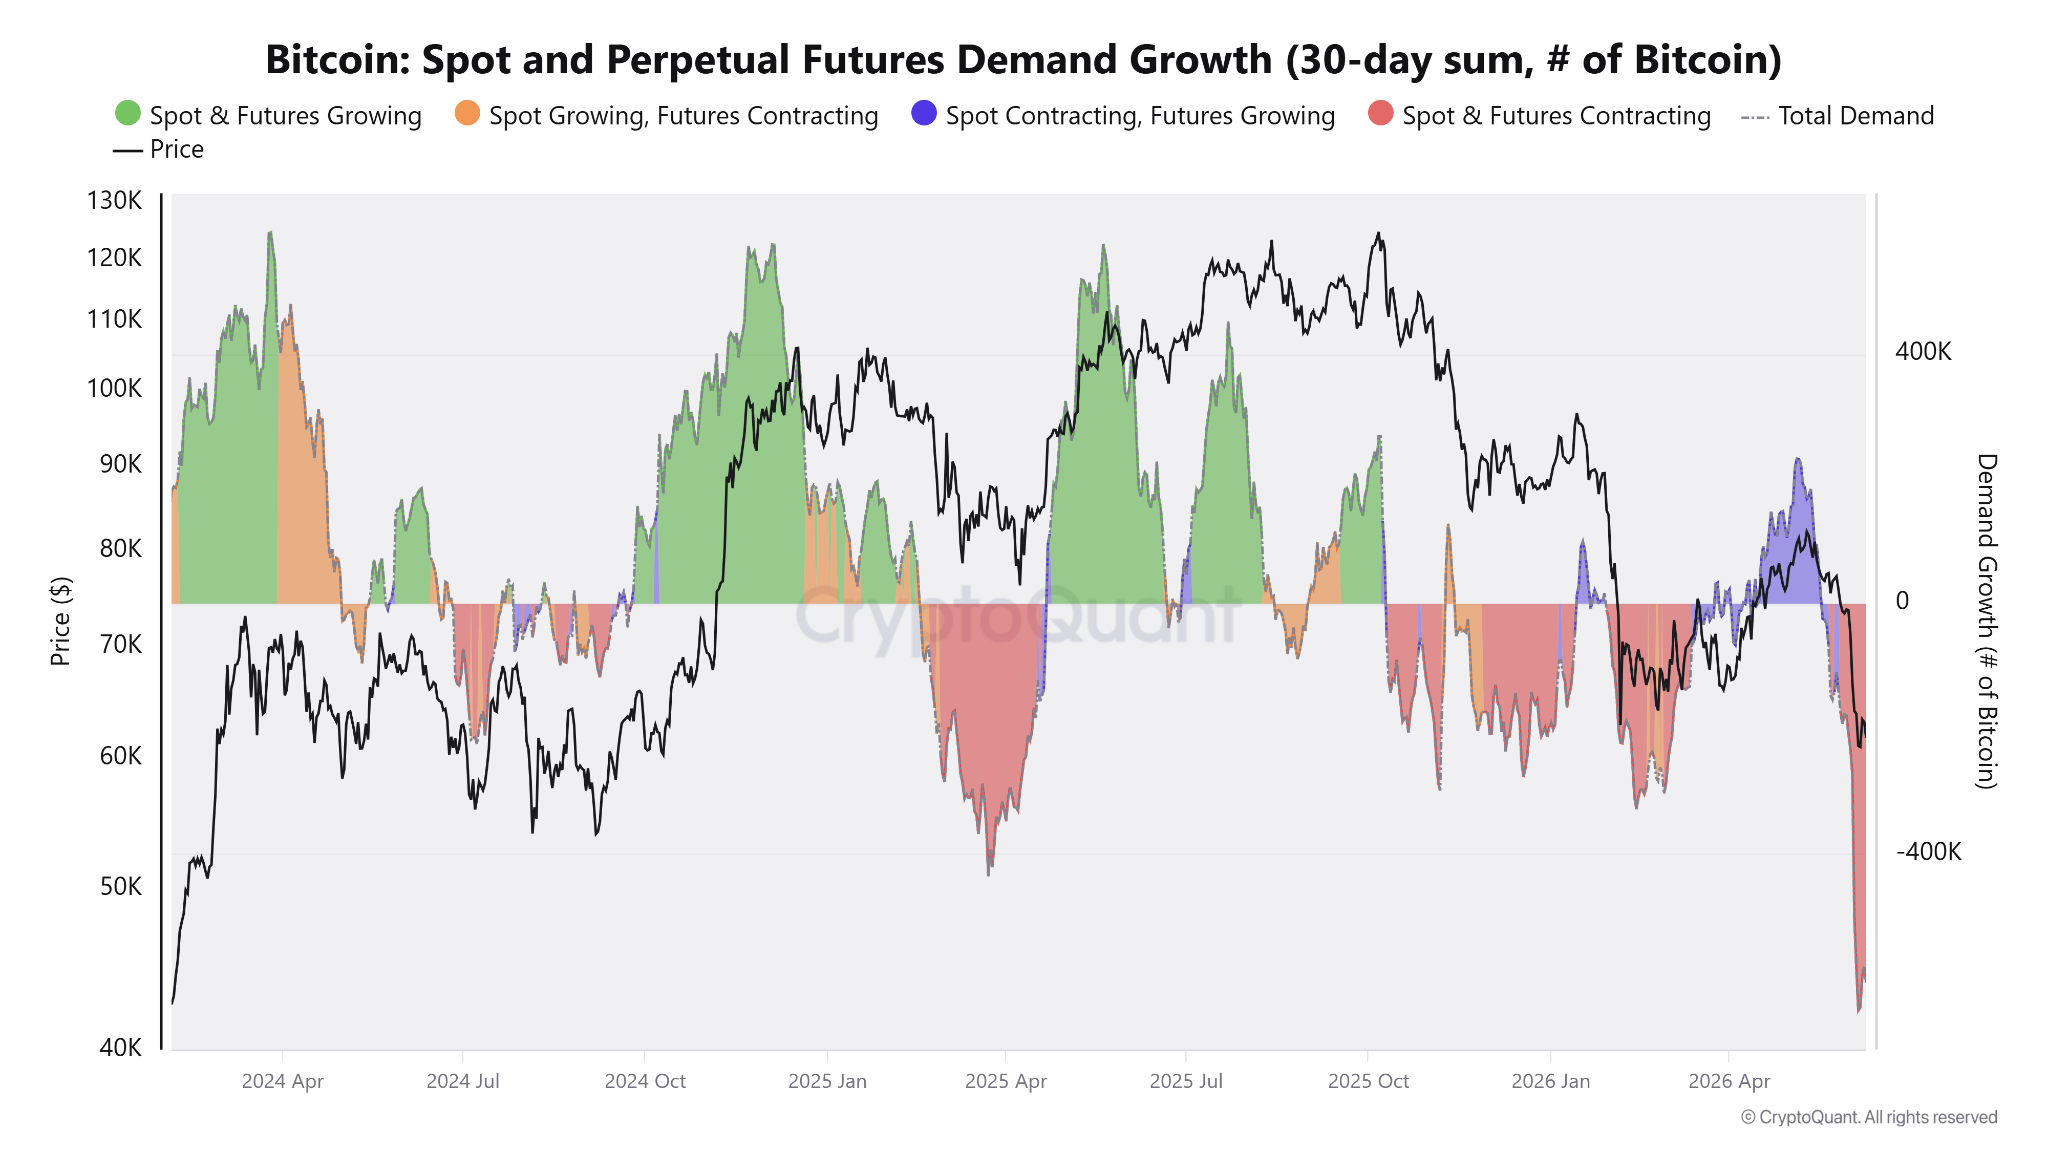
BTC: spot and perpetual futures demand growth contraction. Source: CryptoQuant

The relationship between BOJ policy and Bitcoin is often linked to the yen carry trade. For years, investors borrowed yen at low rates and deployed that capital into higher-yielding assets, including stocks and cryptocurrencies. 

When the BOJ raises rates, some of those positions can be reduced, weighing on risk assets. The July 2024 hike coincided with one of the largest carry-trade unwinds in recent years and a sharp sell-off across global markets, not only BTC. 

The influence of that particular condition appears smaller today. The BOJ has already raised rates to 0.75% from -0.1% in March 2024, while Japan’s 10-year government bond yield climbed to 2.68% from 0.63% over the same period. 
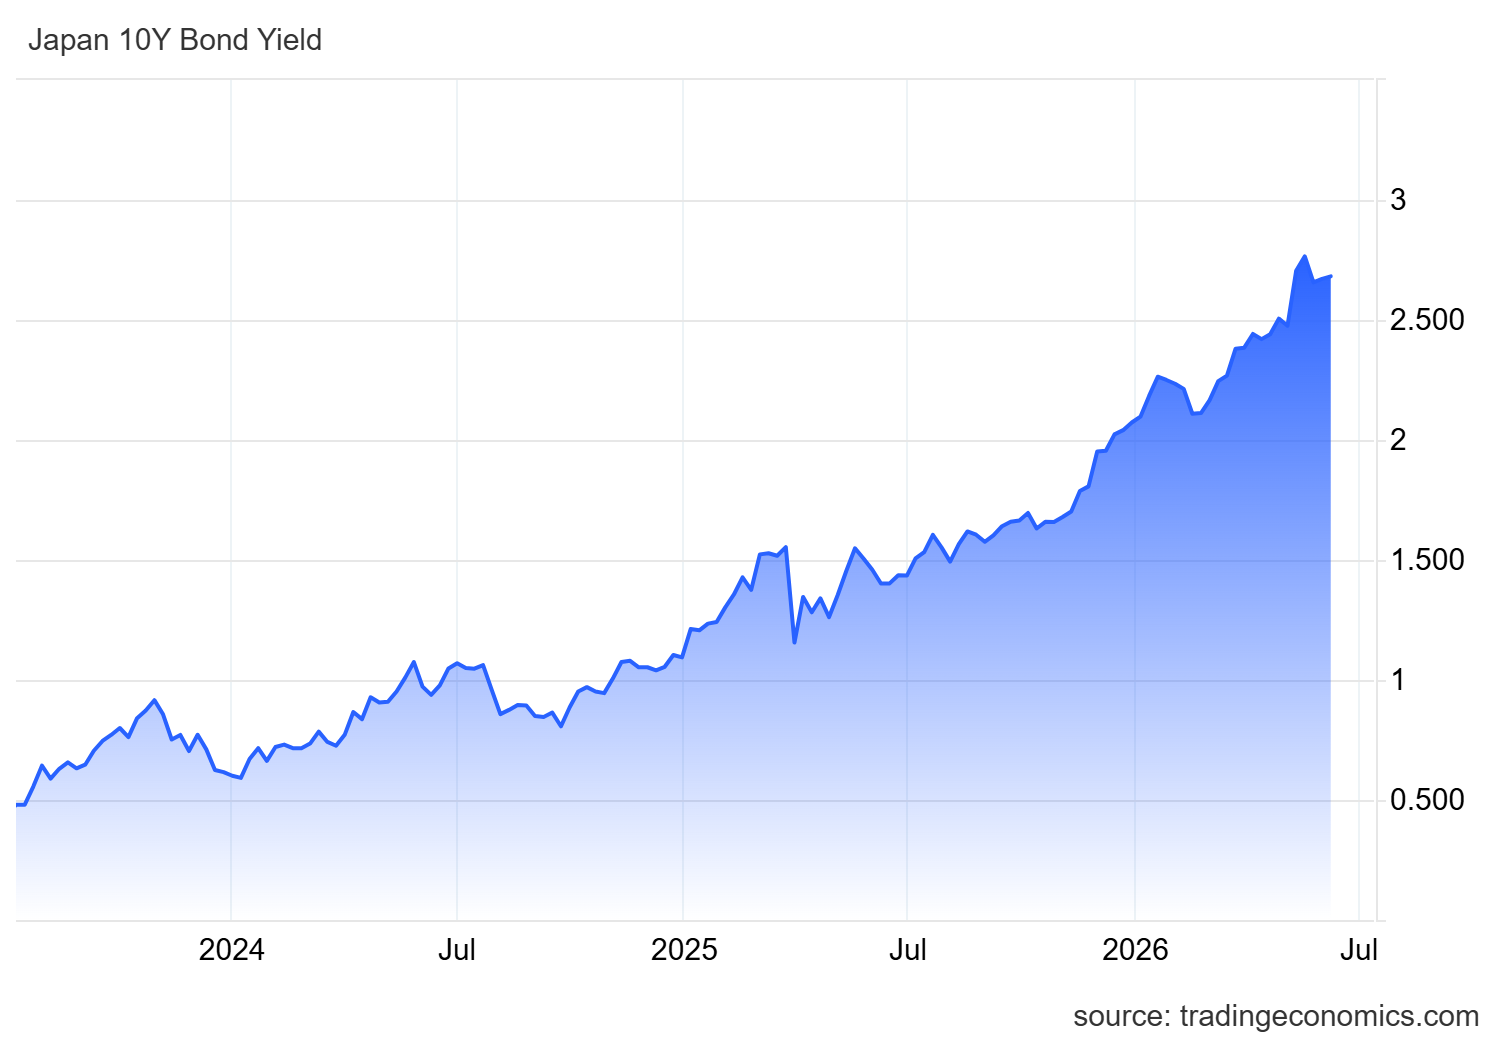
Japan’s 10-year bond yield increase since 2024. Source: TradingEconomics

With Japan’s borrowing costs already higher than during the negative-rate era, each additional hike represents a smaller policy shift than the BOJ’s initial move away from ultra-loose monetary policy. The June 16 meeting would extend an existing tightening cycle rather than introduce a new one. 

Likewise, market analyst Cryptic Trades noted that concerns about a renewed yen carry-trade unwind are overblown, arguing that Japan has effectively moved away from its deflationary policy framework in 2024. The analyst added,

“The Yen Carry Trade has been dead ever since 2024. It is also a BIG nothing burger for the markets.”

Related: Bitcoin price may slide toward $30K as institutions dump 450% of daily BTC supply

BTC whales add to the pressure

While the BOJ meeting is a macro event that traders may monitor, onchain data points to a more immediate source of pressure.

Crypto analyst MorenoDV noted that Binance has recorded rising BTC inflows from wallets holding 100–1,000 BTC and 1,000–10,000 BTC since the sell-off began in early June. As a result, the exchange’s 30-day whale inflow sum has climbed to $6.6 billion. 
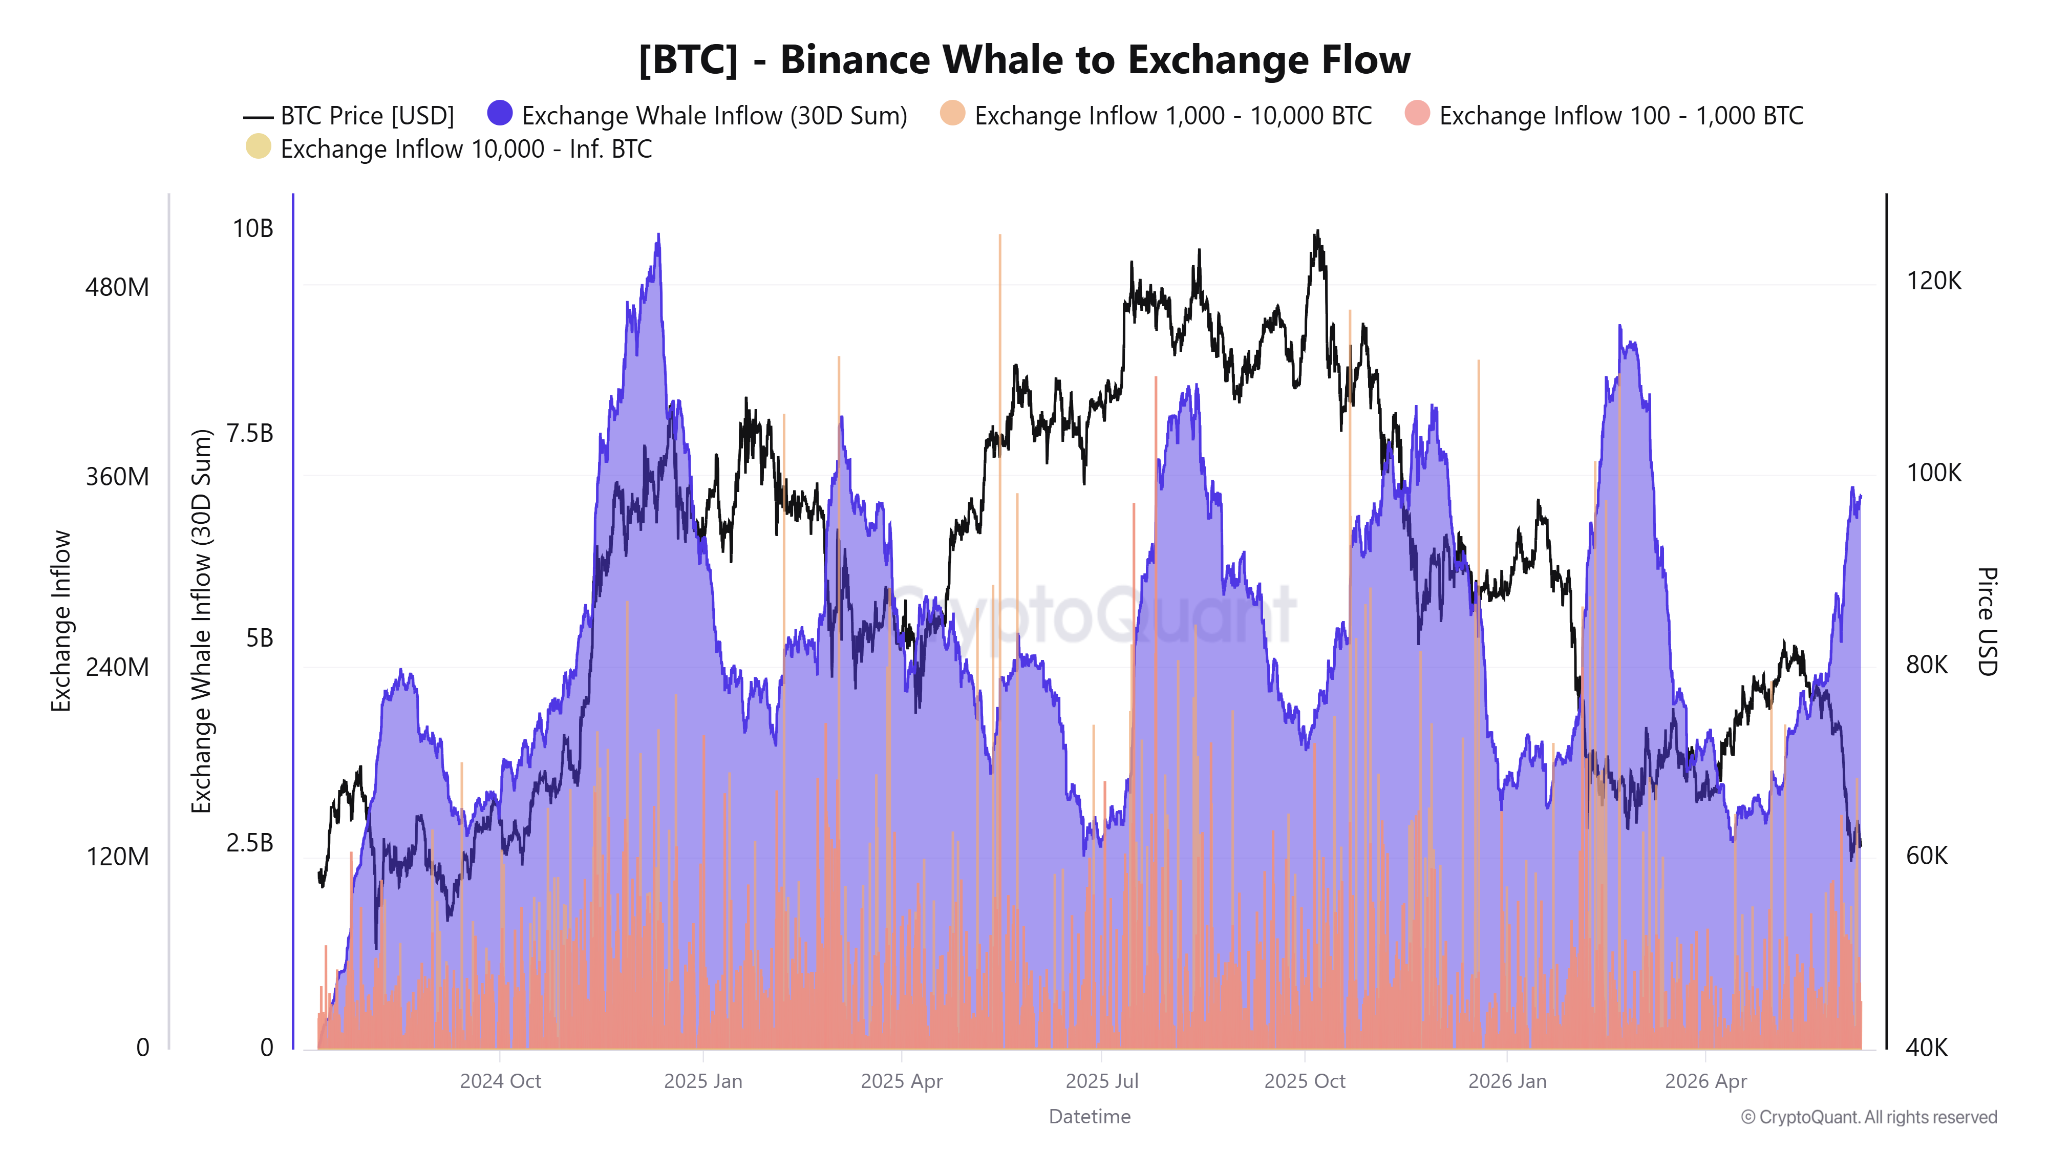
Bitcoin whale to exchange flow. Source: CryptoQuant

The pressure is already visible in realized activity. Short- and long-term whales have collectively locked in more than $2.5 billion in losses during the decline, indicating that some large holders have actively reduced exposure.

Short-term whales appear particularly vulnerable. The cohort is carrying roughly $16 billion in unrealized losses after briefly returning to profit for around 10 days in early May. Those positions now sit close to break-even levels, creating a potential source of supply during rebounds. MorenoDV said, 

“Taken together, these three readings describe the stress profile of a late-stage bear market: capitulating whales, distribution into weakness, and a fragile short-term cohort with its finger on the trigger.”

Related: Bitcoin may act as a ‘canary in the coal mine’ as risk-off pressure spreads: Bitwise
AI Deepfake Election Ad Raises Transparency Concerns

0

The election season is ramping up in the United States, meaning that airwaves and social media are flooded with campaign ads.

Candidates, in addition to the political action committees (PACs) supporting and opposing them, are projected to spend a record-breaking $10 billion in ads this cycle. Some of that is going into AI deepfakes. 

At least 15 AI-generated campaign ads have run since November, according to NBC News. Some have used deepfakes to portray a candidate doing or saying things that compromise their campaign’s image.

Transparency advocates say the ads, which are illegal in some states, could harm the integrity of American elections.

Ad runs afoul of local election laws

In the context of campaign ads, AI is mostly governed at the state level. Some 28 states have disclosure laws, while in two states, it is prohibited, though not totally. 

In Minnesota, one ad campaign has already bumped up against local legislation. Minnesota Lt. Governor Penny Flanagan posted on BlueSky on June 3 “you might see a TV ad starring something that… kind of looks like me.”

Flanagan was referring to an ad run by a PAC supporting her opponent in the Senate primary race, fellow Democrat and US Representative Angie Craig. The ad shows Flanagan standing atop a large pile of cash, and criticizes her alleged ties to special interest groups.

“My opponent’s super PAC is using an AI deepfake of me to mislead voters. They can’t win with the truth – so they’re resorting to lies.”

“It’s disgusting. Minnesotans deserve better.”

The ad may run afoul of Minnesota campaign laws. In 2023, Democratic State Representative Maye Quade introduced a bill that bans AI deepfakes. It was passed into law, and “anyone who widely shares a deep fake within 90 days of an election” is guilty of a crime. This, provided that the person also:

  • Knows or should have known the ad was a deepfake and made without the consent of the depicted person
  • Acted with the intent to harm a candidate’s reputation to influence an election

The ads ran after the DFL, Minnesota’s Democratic party, nominated Flanagan, so technically it may have not violated the law. Still, Flanagan’s campaign is reportedly consulting lawyers.

Quade told local media that the ad violated the spirit of the law, and that people in general don’t like AI being used this way. “People don’t like this, broadly […] What campaign on either side of the aisle is going to help voters feel good about their candidate using this?”

Related: Prediction markets legal battles heat up in Minnesota, Rhode Island

On the Democratic side of the aisle, 40 DFL state legislators signed a letter condemning the use of AI deepfakes in campaign materials. They noted that, in 2023, “lawmakers voted nearly unanimously to ban the use of deceptive AI-generated deepfakes in elections, recognizing the threat manipulated AI content poses to voters and public trust.”

“Regardless of party, the use of AI-generated deepfakes in campaign advertising is unacceptable.”

Mark Jablonowski, the CEO of advertising firm DSPolitical, told NBC that he thinks most politicians will rise above it. “I think most campaigns on both sides of the aisle probably want to do the right thing […] There, of course, are going to be examples that you can point to where people are going about it the wrong way.”

The PAC that issued the ad, North Star Dawn PAC, did not respond to Cointelegraph’s request for comment. 

What do election laws say about AI deepfakes?

As noted above, some 30 states have laws on the books regarding AI use in elections. The vast majority of these relate to simple disclosure, with many states only having civil penalties for infractions. 

The Federal Elections Commission (FEC), the regulator responsible for creating funding, disclosure and other rules concerning elections. Regarding ads, the FEC told Cointelegraph:

“Commission regulations require clear and conspicuous disclaimers to appear on certain campaign advertisements, including public communications that are distributed by a federal candidate’s campaign committee.There is also a prohibition against ‘fraudulent misrepresentation.’”

Public Citizen, a consumer advocacy group, submitted a petition for rulemaking before the FEC in 2023, asking the commission to issue rules for AI. Instead, the body “decided not to initiate a rulemaking.”

“The Commission determined that the statute’s fraudulent misrepresentation ban is technology neutral, applying to all means of the specified fraud, including AI-assisted media.”

One may not expect quick action from the federal government, at least not from Congress, on AI. In 2023, Senator Amy Klobuchar and Representative Yvette Clarke, both Democrats, introduced the REAL Political Advertisements Act in their respective chambers. However, the bill failed to pass in either house. 

If anything, the US Congress shows a total unwillingness to meaningfully regulate AI. Nearly one year ago, President Donald Trump signed the One Big Beautiful Bill Act into law. The final version narrowly avoided including a 10-year ban on any state and local regulation of AI, giving the industry carte blanche for anything from building data centers to how AI would be used in popular media. 

Now, two Congressmen are back at it. Democrat Lori Trahan and Republican Jay Obernolte on June 4 introduced a bill that, if passed, would ban states from passing laws “targeting artificial intelligence model development.”

According to the American Civil Liberties Union (ACLU) “This could include anything from privacy regulations to antidiscrimination requirements to AI safety laws.”

The ACLU noted that the aforementioned 10-year ban was stripped from the Senate file in a near-unanimous 99-1 vote.

Jina John, senior policy counsel for AI, privacy and technology at the ACLU, said, “This draft bill fails to learn from Congress’s previous attempts to block state AI regulations. States must be able to protect their own residents from harm, hold tech companies accountable, and ensure that AI is safe and trustworthy.”

Magazine: Korea probes Polymarket users, crypto PACs sweep primaries: Hodler’s Digest, May 31- June 6

BlackRock and Fidelity are quietly turning bitcoin ETFs into a two-firm market

0

When U.S. spot bitcoin exchange-traded funds (ETFs) launched in January 2024, investors had more than a dozen funds to choose from. BlackRock, Fidelity, Ark Invest, Bitwise, VanEck, Franklin Templeton and several others entered what many expected would become a fiercely competitive market.

Eighteen months later, the battle increasingly looks like a two-player race.

Data shows that BlackRock’s iShares Bitcoin Trust (IBIT) and Fidelity’s Wise Origin Bitcoin Fund (FBTC) are doing most of the heavy lifting when it comes to attracting new institutional capital, while smaller funds have become largely irrelevant in determining the direction of the overall market.

The trend was evident throughout the first half of 2026.

On January 14, bitcoin ETFs recorded net inflows of $840.6 million, according to data from Farside Investors. IBIT alone accounted for $648.4 million of that total, while FBTC added another $125.4 million. Together, the two funds represented more than 90% of all inflows that day.

A similar pattern appeared on April 17, when total inflows reached $663.9 million. IBIT brought in $284 million and FBTC added $163.4 million, accounting for roughly two-thirds of all new money entering the sector.

Even during periods of weaker sentiment, the dominance of the two largest funds remained apparent. On May 1, total inflows reached $629.8 million, with IBIT contributing $284.4 million and FBTC adding $213.4 million. Combined, the pair attracted nearly $500 million of the day’s total. The pattern repeated throughout much of 2026, with the two funds frequently accounting for the majority of net inflows on the largest allocation days and often offsetting weakness elsewhere in the ETF market.

The concentration has emerged during a difficult year for bitcoin and the broader crypto ETF market. Bitcoin is down roughly 29% year-to-date, a decline that has tested institutional conviction and triggered several waves of ETF redemptions. Between mid-May and early June alone, spot bitcoin ETFs recorded multiple days of heavy outflows. The selling marks a sharp contrast to earlier periods when investors often viewed bitcoin pullbacks as buying opportunities.

But the data highlights a broader shift taking place in the bitcoin ETF market in which investors increasingly appear to be concentrating their allocations in the largest and most liquid vehicles.

That trend has particularly benefited BlackRock.

IBIT has emerged as the flagship product of the entire spot bitcoin ETF sector, regularly posting the largest inflows and often acting as a stabilizing force during periods of market stress. On several days when the broader ETF complex experienced heavy outflows, IBIT either remained positive or saw far smaller redemptions than its competitors.

The dominance is not entirely surprising. Many of the largest buyers of bitcoin ETFs are financial advisers, registered investment advisers, hedge funds, family offices, pension consultants and institutional asset allocators. For those investors, liquidity, trading volume and issuer reputation often matter as much as the underlying bitcoin exposure itself.

BlackRock manages more than $10 trillion in assets globally and maintains relationships with thousands of wealth-management platforms. Fidelity, one of the largest retirement and brokerage providers in the U.S., brings similar advantages through its distribution network and long-standing presence among retail and institutional investors.

As a result, many allocators increasingly view IBIT and FBTC as the default options for gaining bitcoin exposure.

The flip side is that smaller issuers are struggling to remain relevant.

Funds such as Franklin Templeton’s EZBC, VanEck’s HODL, Valkyrie’s BRRR and WisdomTree’s BTCW frequently record daily flows measured in single-digit millions of dollars.

On many trading days, their contributions are so small that they have little impact on the overall direction of the market.

Even funds that were once viewed as major competitors, including Bitwise’s BITB and Ark’s ARKB, now play a secondary role compared with the industry’s two largest products. Earlier this year, Trump Media & Technology Group withdrew plans for a proposed spot bitcoin ETF, abandoning an effort to enter the increasingly crowded market that is now dominated by products from BlackRock and Fidelity.

The concentration has become particularly noticeable during periods of volatility. When investors buy bitcoin ETFs aggressively, most of the money flows into BlackRock and Fidelity.

When investors sell, the behavior of those two funds often determines whether the sector posts net inflows or outflows.

That dynamic suggests the bitcoin ETF market is entering a new phase. Rather than a broad competition among a dozen issuers, the industry increasingly resembles a winner-take-most business where scale, liquidity and distribution drive investor decisions.

Ethereum (ETH) developers are exploring new token standards as privacy returns to focus

0

For years, privacy in transacting was one of crypto’s most ambitious promises. Then it took a back seat as other trends took off.

As developers focused on scaling blockchains and regulators scrutinized privacy tools such as Tornado Cash, much of the industry’s attention shifted elsewhere. But a new Ethereum proposal and a growing number of privacy-focused products suggest the topic is making a comeback.

The latest example is pERC-20, a proposed Ethereum token standard that would allow users to hold and transfer tokens without publicly revealing their balances, transaction amounts or counterparties. The proposal has sparked renewed discussion around whether public blockchains should expose every financial interaction by default.

Unlike traditional ERC-20 tokens, which is the default token standard on Ethereum today that displays balances and transaction histories onchain for anyone to inspect, pERC-20 keeps sensitive details private.

Today, most Ethereum tokens function like public bank accounts. Anyone can look up a wallet address and see how many tokens it owns, where they came from and where they were sent. Under pERC-20, tokens would instead exist as encrypted cryptographic “notes,” similar to digital cash.

The result is a system where transactions remain private while still allowing the network to verify that no changes to the transactions occurred.

Importantly, the proposal does not hide everything.

The total supply of a token would remain publicly visible, allowing anyone to verify that new tokens are not being secretly created. The proposal also includes a compliance mechanism that would allow issuers to freeze specific notes through a cryptographic blacklist without exposing ordinary users’ balances or transaction histories.

The design reflects a broader shift in how privacy is being discussed across crypto.

Rather than treating privacy and compliance as mutually exclusive, many newer projects are attempting to build systems that offer both.

But some developers argue that private payments are only part of the challenge.

Earlier this week, Starknet went live with STRK20, a privacy-focused token framework designed to extend confidentiality beyond simple token transfers and into decentralized finance applications such as lending, staking and token swaps.

According to Eli Ben-Sasson, the co-founder of StarkWare, the main developer firm behind Starknet, the biggest obstacle facing privacy technologies today is not cryptography. “The big problem of dealing with privacy is UX,” Ben-Sasson told CoinDesk.

Historically, privacy-focused cryptocurrencies have struggled with usability. Users often faced slow wallet synchronization, cumbersome transaction flows and limited compatibility with the broader crypto ecosystem. Those limitations made privacy tools difficult to use and, in some cases, undermined the privacy they were designed to provide.

Privacy systems rely on large groups of users participating together. If only a small number of people use a privacy network, it becomes easier to identify individual participants.

“If the UX is bad, very few users are going to be using it,” Ben-Sasson said. “If very few users are going to be using it, and only for a very small number of things, they don’t really get a lot of anonymity.”

Ben-Sasson said pERC-20 appears to be largely focused on private token transfers and draws on ideas pioneered by privacy-focused projects such as Zcash. While he described that as an important capability, he argued that the next stage of privacy infrastructure will need to support a much broader set of financial activities.

“Today we can do more,” he said, referring to privacy-preserving DeFi applications.

The STRK20 framework was built with that goal in mind. Rather than shielding a single token, the framework allows users to manage multiple assets under a unified privacy layer and interact with decentralized applications while maintaining confidentiality. According to Ben-Sasson, users can access services such as swapping, borrowing and staking without sacrificing privacy.

The framework also uses post-quantum secure cryptography, which Ben-Sasson argued will become increasingly important as blockchain developers begin preparing for future advances in quantum computing.

The contrast between pERC-20 and STRK20 highlights an emerging debate about what privacy in crypto should actually look like.

One vision focuses on making payments private while preserving transparency elsewhere. Another seeks to make privacy a foundational layer that extends across an entire ecosystem of financial applications.

Either way, the discussion itself marks a notable shift.

For much of the past several years, privacy occupied a relatively small corner of the crypto industry, often associated with niche privacy coins or controversial mixing services. Today, the conversation is increasingly centered on mainstream infrastructure, token standards and institutional use cases.

Whether pERC-20 ultimately becomes an Ethereum standard remains uncertain. Like all Ethereum Improvement Proposals, it must go through a lengthy review process before it could see widespread adoption. But its emergence, alongside projects such as STRK20, suggests that privacy is once again becoming a priority for blockchain developers.

Read more: Not all Ethereum layer 2s are dying, but many general-purpose chains no longer have a reason to exist

Morgan Stanley’s Bitcoin Executive Says Education — Not Products — Is Wall Street’s Real Obstacle

0

When Morgan Stanley created a firmwide Head of Digital Asset Strategy role in January 2026, it handed the job to Amy Oldenburg — a 26-year veteran of the bank who spent much of her career in emerging markets, trading foreign exchange and equities in places where formal banking infrastructure was either unreliable or absent. 

That background, she said in a recent interview on the Coin Stories podcast with Natalie Brunell, shapes everything she believes about where Bitcoin is headed.

“Where were the first users of a lot of this?” Oldenburg said, pointing to cross-border and international markets — regions where people were not rejecting the traditional banking system out of ideology, but because that system had already failed them. 

On the podcast, she described watching M-Pesa, Safaricom’s mobile money service, spread across East Africa in 2007, with women loading cash onto flip phones in villages with no reliable electricity and dirt roads. The parallel to Bitcoin’s decentralized value proposition was not lost on her.

Morgan Stanley’s entry into Bitcoin has been methodical, and Oldenburg explained why. The bank is a global systemically important bank, or G-SIB, and unlike BlackRock — an independent asset manager — Morgan Stanley is owned by a bank holding company governed by the Federal Reserve. 

That distinction meant the firm faced capital treatment requirements and regulatory constraints that independent asset managers did not, forcing it to watch peers roll out crypto products years before it could.

The regulatory environment was not the only obstacle. Morgan Stanley had built a plan years in advance to launch spot crypto trading on its E-Trade platform, but by 2024, several of the vendors the bank had shortlisted for partnerships had collapsed — a casualty of the same industry shakeout that took down FTX and a wave of smaller firms. The bank had to rebuild its strategy from the ground up.

When the firm finally launched the Morgan Stanley Bitcoin Trust — ticker MSBT — on April 7, 2026, it became the first spot Bitcoin ETF issued by a U.S. chartered bank. The debut was the strongest first-day ETF launch in Morgan Stanley’s history, taking in over $33.8 million and landing in the top 1% of all ETF debuts by volume, according to Bloomberg senior ETF analyst Eric Balchunas. 

The fund carries an expense ratio of 0.14%, making it the cheapest Bitcoin ETF in the U.S. market — undercutting BlackRock’s IBIT by 11 basis points.

The use gap between the products and advisors

The product exists. The challenge now, Oldenburg said, is getting the people inside Morgan Stanley’s own wealth machine to use it. 

The firm manages roughly $9.3 trillion in client assets, and in October 2025 its Global Investment Committee formally recommended a 2% to 4% crypto allocation for moderate to aggressive growth portfolios, describing Bitcoin as a scarce asset comparable to digital gold. Yet advisor uptake has been slow.

Oldenburg attributed this directly to an education gap. Many financial advisors still cannot cleanly distinguish Bitcoin from the broader crypto category — let alone explain the structural differences between Bitcoin, Ethereum, and Solana to a client who just wants to know if it belongs in their retirement account.

The problem runs in both directions: clients who came of age watching crypto exchanges collapse understandably associate all digital assets with FTX-era chaos, while advisors with fiduciary responsibility are reluctant to recommend an asset that still moves in lockstep with risk equities rather than as an independent inflation hedge.

“It’s not all fitting together yet,” Oldenburg said, comparing the current moment to the early days of the BlackBerry — a technology where she knew something was there, but the use case had not crystallized for most people.

This sentiment echoes Oldenburg’s comments at The Bitcoin Conference, where she argued that bitcoin remains widely misunderstood and that investor education is the key obstacle to broader adoption. She said the firm is training advisors, expanding crypto access, and believes regulatory progress could eventually make bank-held bitcoin “not out of the question.”

What would move Bitcoin higher

On the question of what would push Bitcoin toward a more decisive breakout, Oldenburg gave an answer that reflected her experience watching systems under stress. She suggested it may take a crisis — not necessarily a dramatic one, but a slow grind that breaks confidence in traditional financial infrastructure and makes Bitcoin’s properties as a decentralized, borderless store of value viscerally clear. 

She has seen that dynamic play out in emerging markets, in Russia and Ukraine, where people she knew personally lost access to their banking assets overnight.

For U.S. banks to hold Bitcoin on their balance sheets, she said the path runs through capital treatment reform — specifically the removal of the punitive regulatory burden that makes Bitcoin less efficient to hold than other assets from a balance sheet perspective.

The bank is pursuing an OCC digital trust charter that would let Morgan Stanley custody crypto directly, a step that would bring its digital asset ambitions further in-house.

Anchorage Requests Treasury Clarification on GENIUS Act AML Rules

0

Anchorage Digital, a federally chartered crypto bank and stablecoin infrastructure provider, has submitted a public comment letter supporting the US Treasury Department’s proposed Anti-Money Laundering (AML) and sanctions framework for the GENIUS Act, arguing that the rules largely strike the right balance between compliance and innovation.

In a letter published Wednesday, Anchorage said the proposed framework appropriately places AML obligations on regulated stablecoin issuers while urging Treasury to clarify secondary-market sanctions liability, enterprise-wide AML programs and correspondent account requirements.

Specifically, Anchorage argued that issuers should not face strict liability for failing to independently identify sanctioned users who transact on secondary markets through their smart contracts.

“A final rule that is clear and workable gives regulated institutions the certainty they need to build, and strengthens U.S. leadership in the next generation of payments and settlement infrastructure,” Anchorage said.

Source: Kevin Wysocki

The comments address Treasury rules proposed in April that would classify payment stablecoin issuers as financial institutions under the Bank Secrecy Act, subjecting them to AML, customer due diligence and suspicious activity reporting requirements.

The proposal, jointly issued by the Financial Crimes Enforcement Network (FinCEN) and Treasury’s Office of Foreign Assets Control (OFAC), would align stablecoin issuers with existing US anti-money laundering and sanctions compliance standards while imposing enhanced monitoring and recordkeeping obligations.

Related: Solana Institute CEO says CLARITY Act must shield open-source developers

Industry groups push for broader sanctions carveouts

Support for the proposed rulemaking has not been uniform across the crypto industry.

The lobbying arms of crypto derivatives exchange Hyperliquid and venture capital firm Paradigm recently submitted their own comment letter seeking greater clarity on secondary-market obligations, echoing Anchorage’s concerns but taking a more critical view of the proposal overall.

Source: Stefan Schropp

The groups argued that the current framework could impose sanctions obligations on issuers even when they lack a direct relationship with or visibility into users transacting on secondary markets.

“OFAC sweeps secondary market activity into the issuer’s compliance perimeter, treating smart contract interactions as an ongoing “provision of services” that carries sanctions liability regardless of whether the issuer has any relationship with, or visibility into, the transacting parties,” they said.

Related: SEC’s Peirce argues publishing DeFi code is protected speech

Fold Holdings Dumps $45M In Bitcoin To Wipe Out Debt, Stock Briefly Pumps Over 130%

0

Fold Holdings, Inc. (NASDAQ: FLD), the bitcoin financial services company behind a suite of consumer rewards products, announced a series of capital transactions designed to eliminate secured debt, strengthen its balance sheet, and fund the next phase of its growth strategy.

The company monetized approximately $45 million in bitcoin at an average price of around $71,000 per coin, used $20 million of those proceeds to retire bitcoin-collateralized debt, and directed the remaining $25 million toward growth initiatives across its consumer and enterprise platforms. 

The moves leave Fold debt-free on the secured side while preserving a bitcoin treasury of approximately 1,492 BTC — worth roughly $95 million at current prices.

Fold’s stock ripped to $1.50 in early trading, up over 130% on the day. Since then, the stock has fallen to under $1, up only 30% on the day. 

The headline transaction is tied to a broader debt restructuring. Fold repaid approximately $66.3 million in convertible notes, a position it originally built in March 2025 when the company added 475 BTC to its treasury through those same instruments. Retiring the debt released 521 BTC that had been locked up as collateral, giving management more flexibility over the company’s bitcoin holdings going forward.

“We have reduced financing risk, strengthened our balance sheet, and ensured that short-term market volatility cannot stand in the way of executing our roadmap,” said Will Reeves, Chairman and Chief Executive Officer. “As we approach several product launches, we believe Fold is entering one of the most important growth periods in the company’s history.”

Fold’s credit card and new products

Fold’s flagship product, its Bitcoin Rewards Credit Card, sits at the center of management’s growth thesis. 

The debt elimination removes monthly cash interest payments from the expense base and, in Reeves’ framing, gives the company the financing flexibility to support a larger cardholder base and pursue funding relationships that participate in the card program’s economics as it scales.

The company also has a $45 million revolving credit facility backed by bitcoin collateral and a $250 million equity purchase facility aimed at future bitcoin accumulation — instruments that reflect the corporate treasury playbook Fold has committed to since going public on February 19, 2025, through a SPAC merger with FTAC Emerald Acquisition Corp.

The restructuring arrives against a backdrop of genuine business momentum. Fold’s fiscal year 2025 revenue reached $31.8 million, a 34% increase year-over-year, driven by transaction volume of nearly $960 million for the period. 

Since launching in 2019, the company has processed more than $2 billion in total transactions and distributed over $45 million in bitcoin rewards to users, the company said. 

The combination of a debt-free balance sheet, a functioning revenue engine, and a treasury that retains exposure to bitcoin appreciation gives Fold a capital structure that management argues is designed for the current environment — one where bitcoin-native financial products are gaining traction with both consumers and institutional financing partners.

“Over the past year, we’ve built one of the strongest product roadmaps in our history,” Reeves said. “Increased liquidity and lower debt ensure we have the resources and flexibility to execute our plans during this pivotal moment for Fold.”

Banks Get Direct Access to Ethereum, Solana Staking Through Taurus Custody

0

Swiss digital asset infrastructure firm Taurus has partnered with P2P.org to let banks and financial institutions access staking services directly through Taurus’ custody platform.

The integration will start with Ethereum.

Taurus said clients using Taurus-PROTECT, its custody platform for banks and regulated institutions, will be able to stake ETH through a native integration with Ethereum’s Beacon Chain deposit contract.

The partnership also gives clients access to validator operations across other proof-of-stake networks, including Solana, Polkadot, Cosmos, NEAR, Cardano and Tezos.

The move is aimed at banks that already custody digital assets but want to generate protocol rewards without moving assets into separate staking workflows.

Under the arrangement, clients retain control of their assets while delegating validator operations to P2P.org. Rewards are determined by the underlying blockchain protocol, rather than by Taurus or P2P.org.

“We are pleased to partner with P2P.org to provide institutional staking services through Taurus-PROTECT,” said Clémentine Drouot, Head of Taurus-NETWORK Partnerships at Taurus. “This collaboration reflects our commitment to providing financial institutions with secure, compliant, and scalable access to staking services, while supporting the operational and governance standards that banks require.”

P2P.org operates non-custodial validator infrastructure for institutional staking. It secures more than $10 billion in delegated assets across more than 50 proof-of-stake networks and has had no slashing incidents across 7 years of operations.

Staking allows holders of proof-of-stake assets to participate in network validation and earn rewards. On Ethereum, validators help store data, process transactions and add blocks to the chain after depositing ETH into the staking system.

But for regulated financial institutions, the technical process is only one part of the problem.

Banks also need custody controls, governance approvals, reporting, validator monitoring, risk management and regulatory clarity. A staking product that sits outside existing custody infrastructure can create operational friction and new compliance questions.

The Taurus-P2P.org partnership is designed to reduce that friction.

“Institutional adoption of staking depends on infrastructure that meets the operational, security, and governance requirements of regulated financial institutions,” Alexander Loktev, CRO of P2P.org, mentioned in a statement shared with AlexaBlockchain.

“By integrating with Taurus, we enable banks and financial institutions worldwide to access institutional-grade staking services directly within the digital asset platform they already use, reducing operational complexity and accelerating time-to-market,” Alexander added.

Taurus has become one of the more visible Swiss digital asset infrastructure providers for banks.

In 2023, Deutsche Bank partnered with Taurus to use its custody and tokenization technology for cryptocurrencies, tokenized assets and digital currencies.

In 2023, Taurus also raised $65 million in a Series B funding round led by Credit Suisse, with participation from Deutsche Bank, Pictet Group and Arab Bank Switzerland.

In 2024, State Street partnered with Taurus to offer digital asset services, including crypto custody and tokenization support for asset-management clients.

The new staking integration comes as banks and institutional custodians expand beyond basic storage.

Staking has increasingly become part of the institutional crypto stack, alongside custody, trading, settlement, tokenization and governance.

Coinbase Prime, for example, offers institutions custody, trading, financing and staking in one platform. Coinbase and Figment also expanded institutional staking access in 2025, allowing Prime clients to use Figment infrastructure without moving assets out of Coinbase custody.

Anchorage Digital has taken a similar route in the United States. The federally chartered crypto bank offers staking from custody and added institutional Solana staking through Marinade Finance in 2026.

BitGo has also marketed staking from qualified custody or self-custody, with integrated reporting and validator support.

The pattern is clear. Institutions do not want staking as a standalone crypto-native workflow. They want it embedded into regulated custody, with audit trails, permissioning, reporting and validator oversight.

The partnership also broadens Taurus’ staking options after its earlier institutional staking collaboration with Everstake. That deal gave Taurus clients access to staking across networks including Solana, NEAR, Cardano and Tezos.

The P2P.org integration adds another validator provider to Taurus’ institutional network and places Ethereum at the center of the offering.

The timing is also relevant for Europe.

The EU’s MiCA (Markets in Crypto-Assets Regulation) has created a more defined framework for crypto-asset service providers. The European Securities and Markets Authority has said staking services are linked to custody when client assets or private keys are held by the provider, meaning firms offering such services must be authorized for custody and administration of crypto-assets.

That makes custody-native staking more important for banks.

It does not eliminate risk. Staking can involve validator downtime, slashing, liquidity constraints, smart contract risk and changing protocol economics. Rewards also fluctuate based on network conditions and are not fixed yields.

Still, the integration shows where institutional digital asset infrastructure is moving.

Banks are no longer looking only for secure crypto storage. They increasingly want ways to put held assets to work while staying inside governance and compliance frameworks they already use.

The above article “Banks Get Direct Access to Ethereum, Solana Staking Through Taurus Custody” was first published on AlexaBlockchain. Read the complete article here: https://alexablockchain.com/banks-get-direct-access-to-ethereum-solana-staking-through-taurus-custody/

Read Also: 

Disclaimer: The information provided on AlexaBlockchain is for informational purposes only and does not constitute financial advice. Read complete disclaimer here.

it’s Bitcoin’s problem, not Ethereum’s

0

If bitcoin and Ethereum had been invented on the same day, nobody would have heard of bitcoin. I sold every bitcoin Bit Digital held and deployed the proceeds into Ethereum. I have built one of the largest corporate Ethereum treasury positions in the world and said, on the record, that we will never sell it. People have asked me to articulate the single strongest argument for that conviction. On March 30, 2026, that argument arrived. Last month, Citi confirmed it.

In a research note published on May 18, Citi analysts warned that quantum computing advances have shortened the timeline for practical attacks on digital assets, and reached a conclusion that should give every institutional bitcoin holder pause: bitcoin faces significantly greater quantum risk than Ethereum, and the gap between them comes down not just to technology but to governance.

That finding echoes the landmark paper released in late March by Google Quantum AI in collaboration with Stanford University and the Ethereum Foundation, which found that the computing resources required to break bitcoin’s foundational cryptography are approximately 20 times lower than previously estimated. A sufficiently advanced quantum computer, operating with fewer than 500,000 physical qubits, could derive a bitcoin private key from its public key in roughly nine minutes. That machine does not exist today. But the window to act responsibly is narrowing faster than most institutions realize. When Google raises the alarm, and Citi confirms it in the same quarter, this is no longer a fringe concern. This is the silver bullet. And it points directly at bitcoin.

Why bitcoin is exposed

Bitcoin’s security rests on elliptic curve digital signature algorithms. When you spend bitcoin, your public key is briefly exposed onchain. Under classical computing, reversing that to obtain a private key is infeasible. Quantum computers running Shor’s algorithm can, in principle, do exactly that during the brief window a transaction is broadcast. The Google paper doesn’t merely confirm this theoretically; it quantifies it with a precision that removes comfortable ambiguity.

Nic Carter, co-founder of Coin Metrics and one of the sharpest minds in digital assets, has been sounding this alarm for months. In a series of essays beginning in October 2025, Carter called quantum computing “the biggest long-term risk to bitcoin’s core cryptography” and accused developers of “sleepwalking towards collapse.” He estimates a quantum computer could meaningfully break elliptic curve cryptography as early as 2028. Approximately 6.9 million BTC could be vulnerable at a sufficient quantum scale, including legacy wallets and Taproot outputs, which already represented more than 21% of all bitcoin transactions in 2025.

Bitcoin’s governance problem

One might ask: can’t bitcoin simply upgrade? Yes, in theory. In practice, this is where the risk compounds.

Bitcoin’s governance is intentionally conservative and consensus-driven, which makes it extraordinarily slow. SegWit took roughly 8.5 years from conception to widespread adoption. Taproot took approximately 7.5 years. The current quantum proposals, BIP-360 and BIP-361, are still at the draft or early testnet stage as of 2026. A full base-layer transition to post-quantum signatures would be the most contentious change bitcoin has ever attempted. As Carter documented, most bitcoin Core developers have expressed limited concern about urgency, a disposition that is, at minimum, a serious governance liability for any institution holding bitcoin in treasury. A quantum breakthrough does not politely wait for committee consensus.

Ethereum has already acted

This is where the picture diverges sharply. Ethereum’s approach to quantum resistance is not a reactive scramble. It is a structured road map already in execution, built on the NIST post-quantum cryptography standards finalized in August 2024.

The Pectra upgrade, which shipped on Ethereum mainnet in May 2025, introduced EIP-7702, a critical stepping stone toward full account abstraction. Rather than requiring a single network-wide hard fork, Ethereum’s architecture allows individual accounts to choose their own signature verification and switch to quantum-safe signatures voluntarily. The upcoming Hegotá hard fork, planned for the second half of 2026, embeds this further at the protocol level. The Ethereum Foundation has set structured milestones targeting completion of core post-quantum infrastructure by approximately 2029, with active interop devnets already running across multiple clients.

The contrast with bitcoin’s governance paralysis could not be more stark. Ethereum was designed, in ways bitcoin simply was not, to accommodate exactly this kind of foundational upgrade. That is not an accident. It is architecture.

The institutional calculus

For corporate treasurers and sovereign wealth managers, quantum risk is no longer a tail scenario to be footnoted and dismissed. Governments are already treating it as operational. U.S. federal agencies faced an April 2026 deadline to submit post-quantum cryptography transition plans under National Security Memorandum 10. The EU has set a 2030 quantum-resistance target for critical infrastructure. The G7 Cyber Expert Group published a coordinated financial sector road map in January 2026. This compliance architecture will, over time, extend to digital asset treasury holdings.

The question for any institution holding bitcoin is whether they are comfortable with an asset whose quantum-resistance road map is still in draft, whose governance moves at geological speed, and whose developer community is divided on whether urgency is even warranted.

The question for any institution considering Ethereum is whether they want the asset with a structured, transparent, and already in motion upgrade path.

Ethereum is the more adaptive, more capable, and more durable asset. I have put the balance sheet of a Nasdaq-listed company behind that conviction. The Google paper is what finally gives that conviction a single, undeniable, technically grounded answer to the hardest question in digital asset treasury strategy: which asset is built to last?

Ethereum is not a perfect asset. No asset is. But in the context of quantum risk, it is the asset whose architecture was built to survive what is coming. If Carter and Google are right, that distinction will matter enormously, and sooner than most people expect.

Bitcoin Price Risks Plunging to $30K as Institutions Dump 450% of Daily BTC Supply

0

Bitcoin (BTC) faced renewed risks of a breakdown toward $30,000, according to a new analysis, as institutional demand turned deeply negative.

Key takeaways:

  • Data shows institutions are offloading around 450% of the daily BTC supply.
  • Bitcoin risks slipping below $30,000 if supply absorption remains weak.

Institutions are selling almost 2,000 BTC per day

Capriole Investments’ institutional buying model, which tracks Bitcoin demand from ETFs, corporate treasuries, and miner issuance, shows net institutional selling at around 450% of daily mined supply, equivalent to about 2,000 BTC per day.

BTC/USD vs institutional buying market cap. Source: Capriole Investments

In other words, large holders are selling 4-5x more Bitcoin than is mined each day.

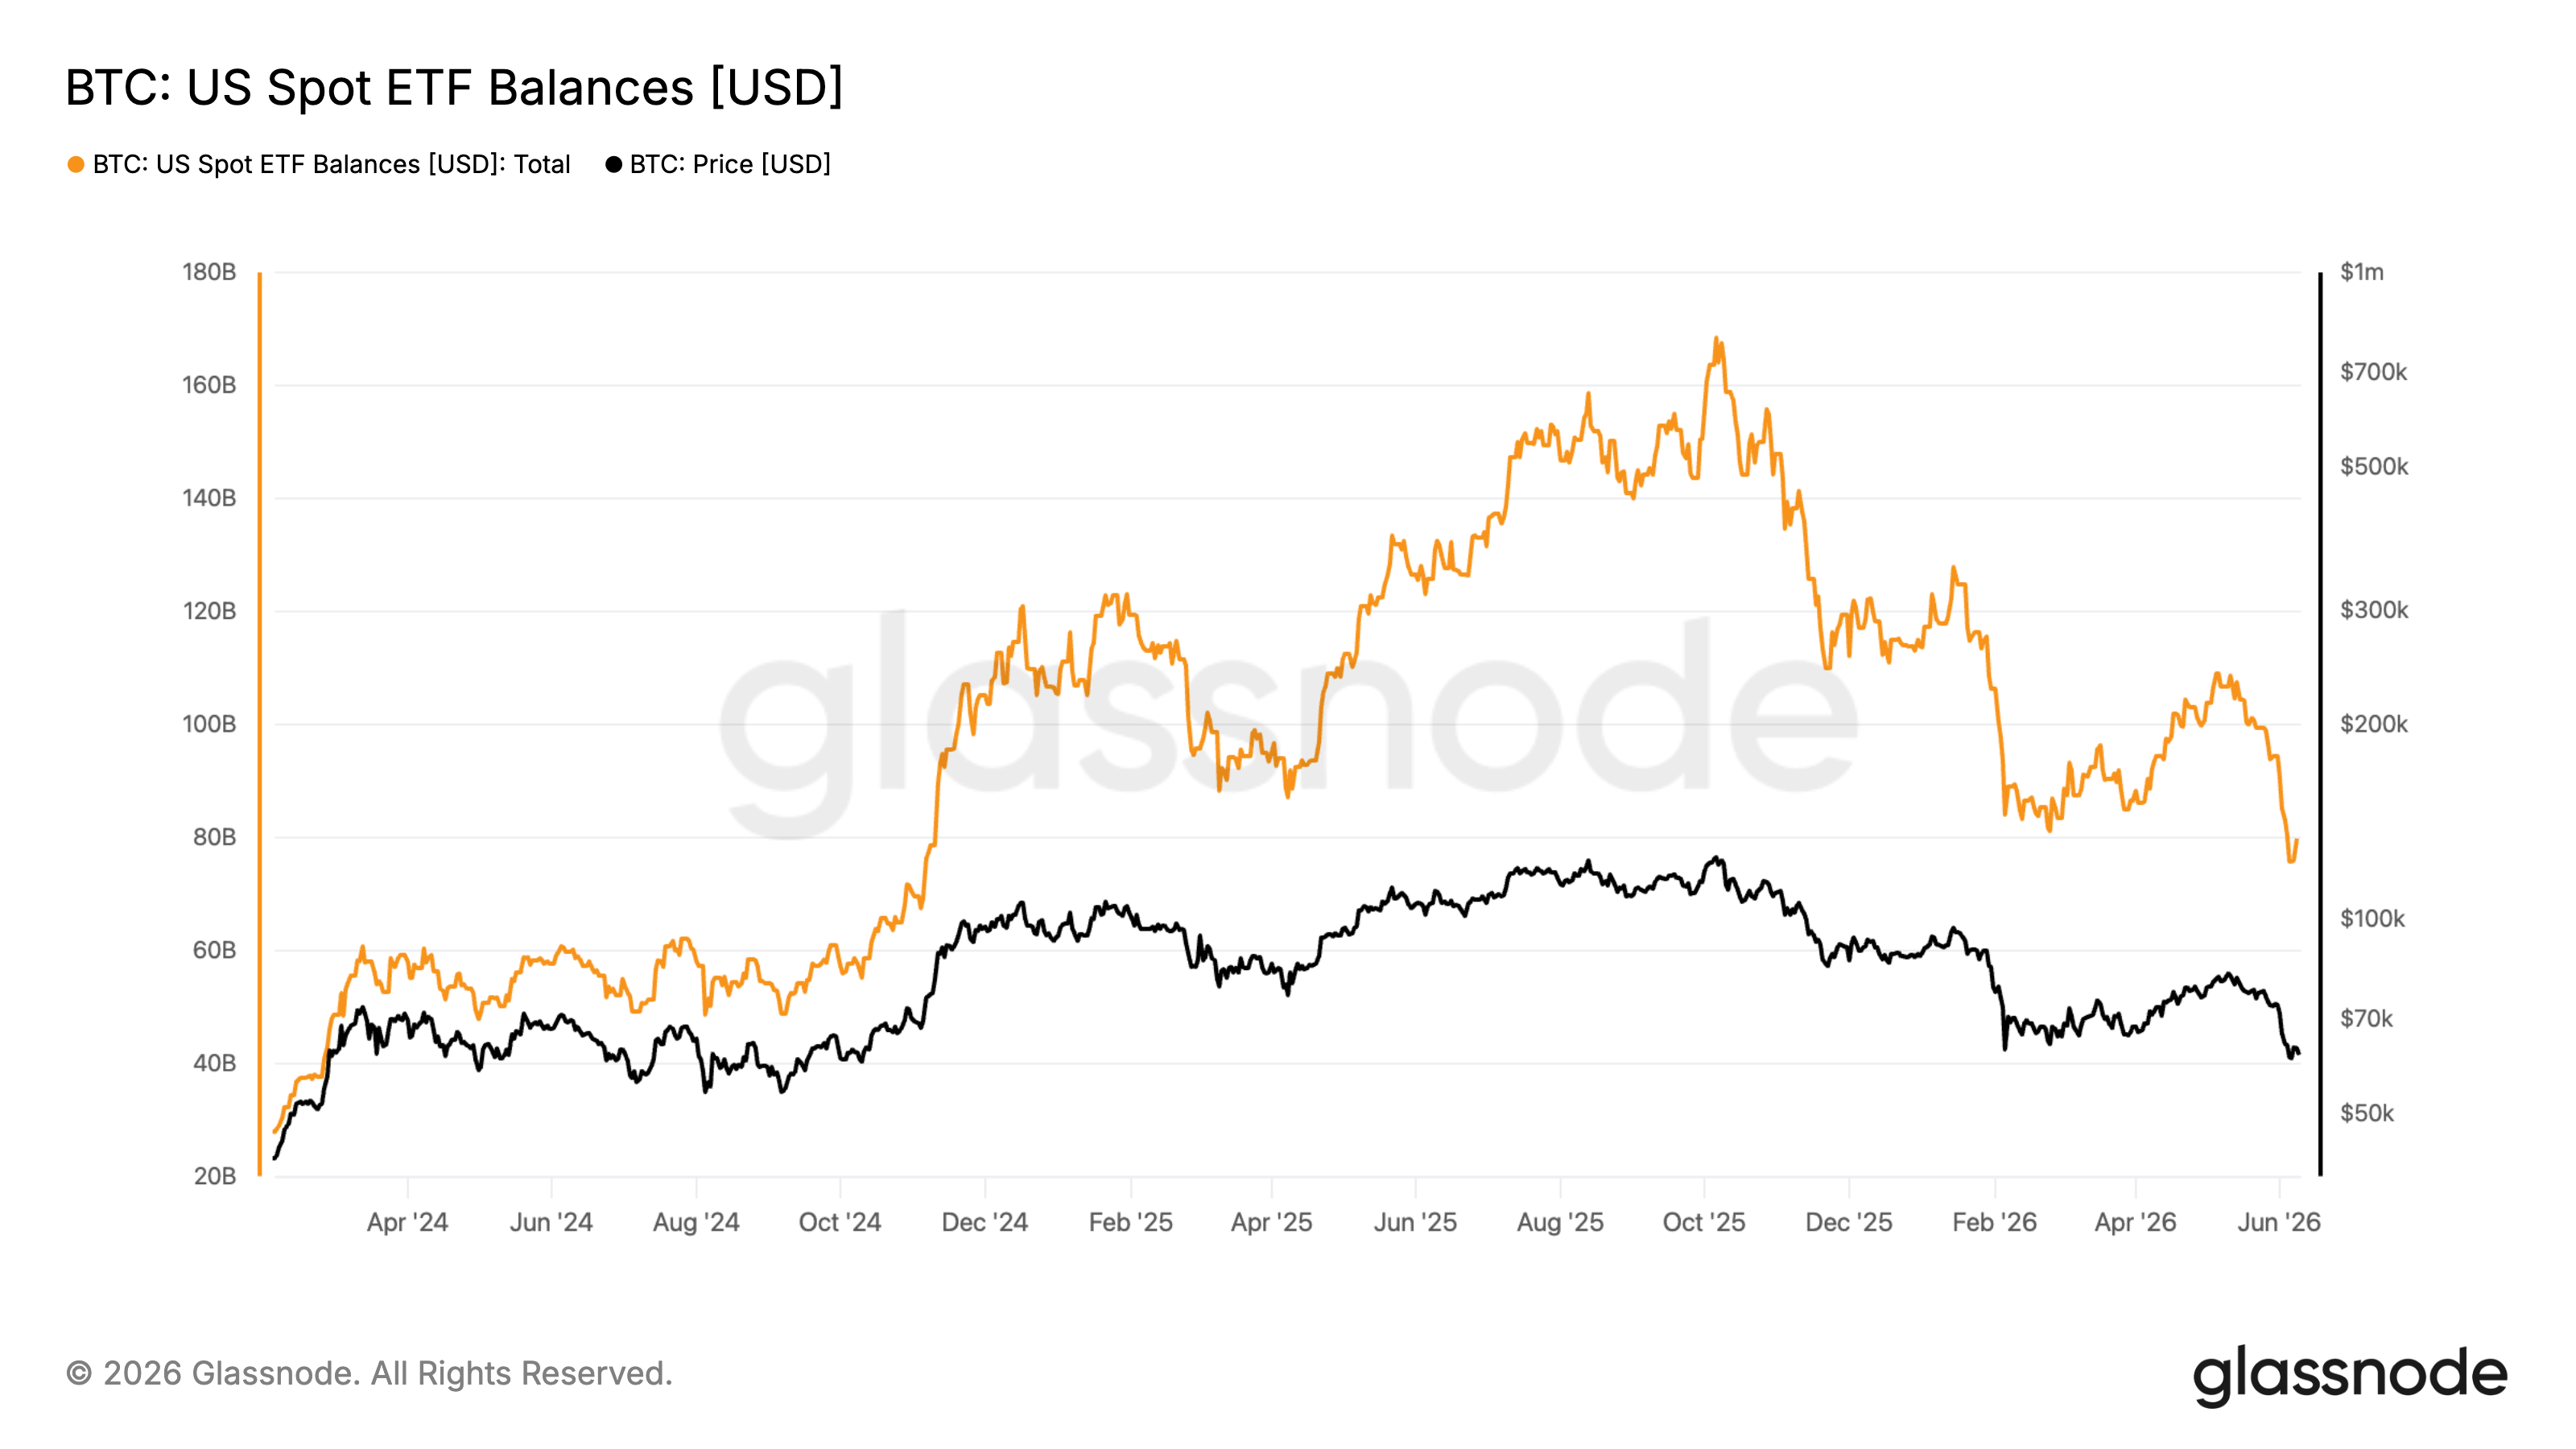
Spot Bitcoin ETFs appear to be the biggest drag. Their flow line has fallen sharply below zero, suggesting ETF outflows are now overwhelming other sources of demand.

In the past month, for instance, these funds have witnessed nearly $27 billion in withdrawals, according to data resource Glassnode.

US Bitcoin Spot ETFs net balances vs. BTC price. Source: Glassnode

That marks a sharp reversal from the 2024–2025 trend, when ETF inflows helped push Bitcoin toward record highs.

Strategy’s slowdown is a weak spot

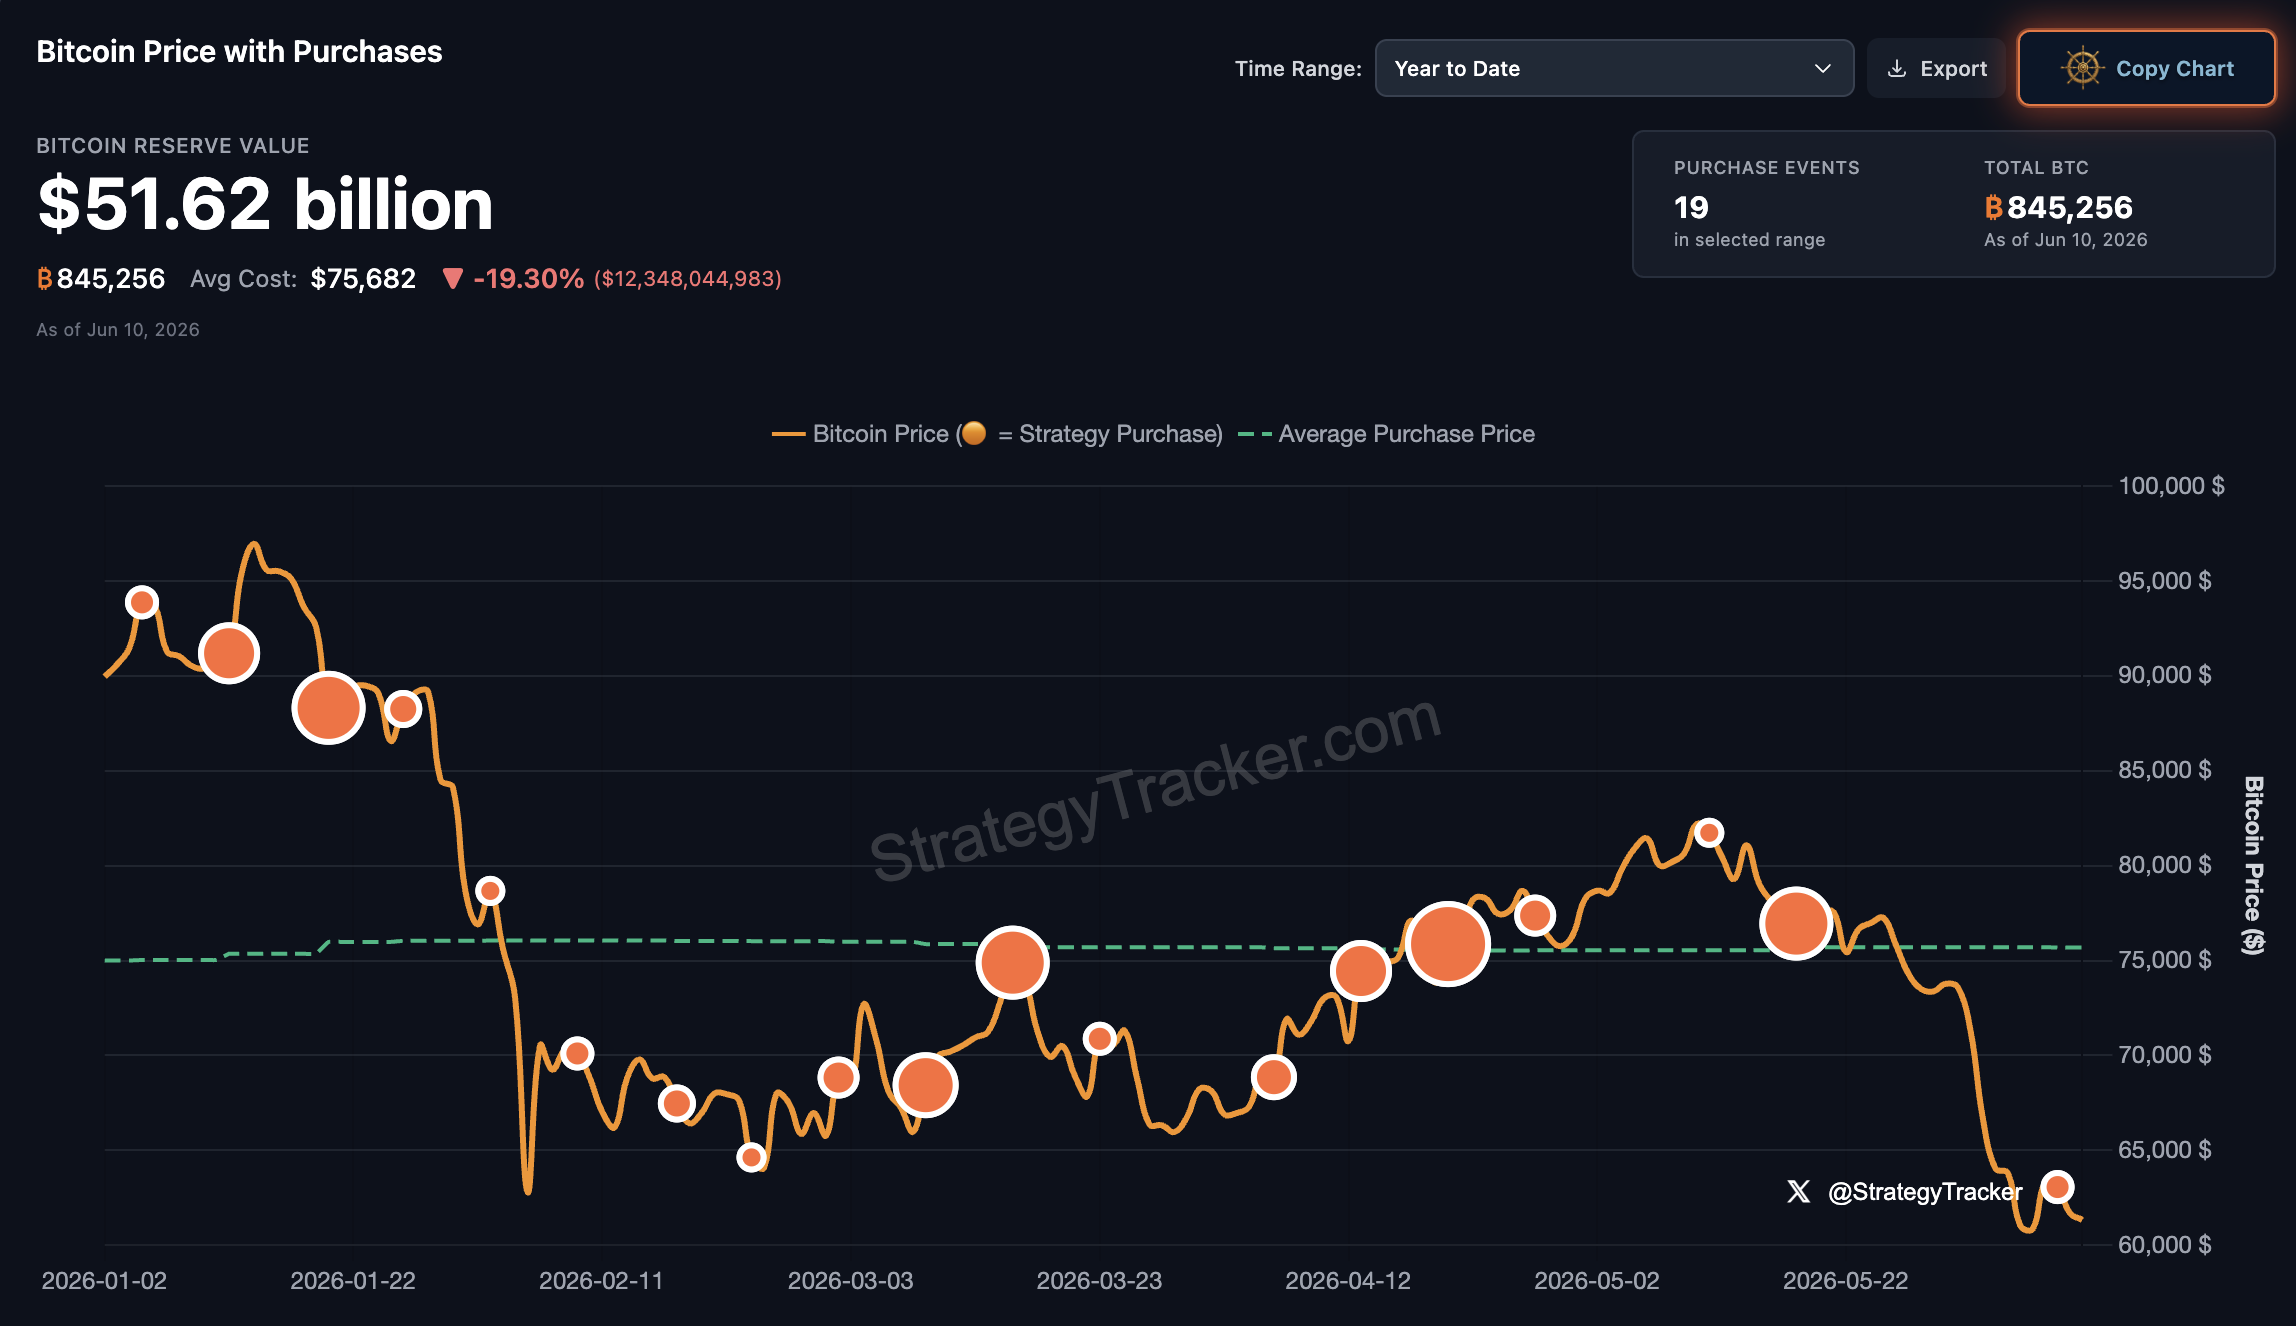
Michael Saylor’s Strategy helped anchor Bitcoin’s institutional demand earlier in 2026, buying 89,599 BTC in Q1 alone.

The company kept buying into Q2, adding roughly 62,300 BTC through late May, including a major 24,869 BTC purchase in mid-May. That lifted its holdings above 843,000 BTC.

Bitcoin price with Strategy purchases. Source: StrategyTracker.COM

The accumulation coincided with BTC’s roughly 40% rebound from its 2026 low of $59,930, reinforcing the view that corporate treasury demand remained one of the market’s strongest pillars during the recovery.

However, its latest buying has slowed sharply, with only a 1,550 BTC purchase in early June after a small 32 BTC sale to fund preferred-stock dividends.

Related: Why Strategy’s 32 Bitcoin sale became a bigger crypto debate

Strategy’s latest purchases are running well below its Q1 and early Q2 pace, and they barely cover ETF-led selling pressure, which Capriole’s model estimates at roughly 2,000 BTC per day.

Bitcoin may slip toward $30,000 or lower, analyst warns

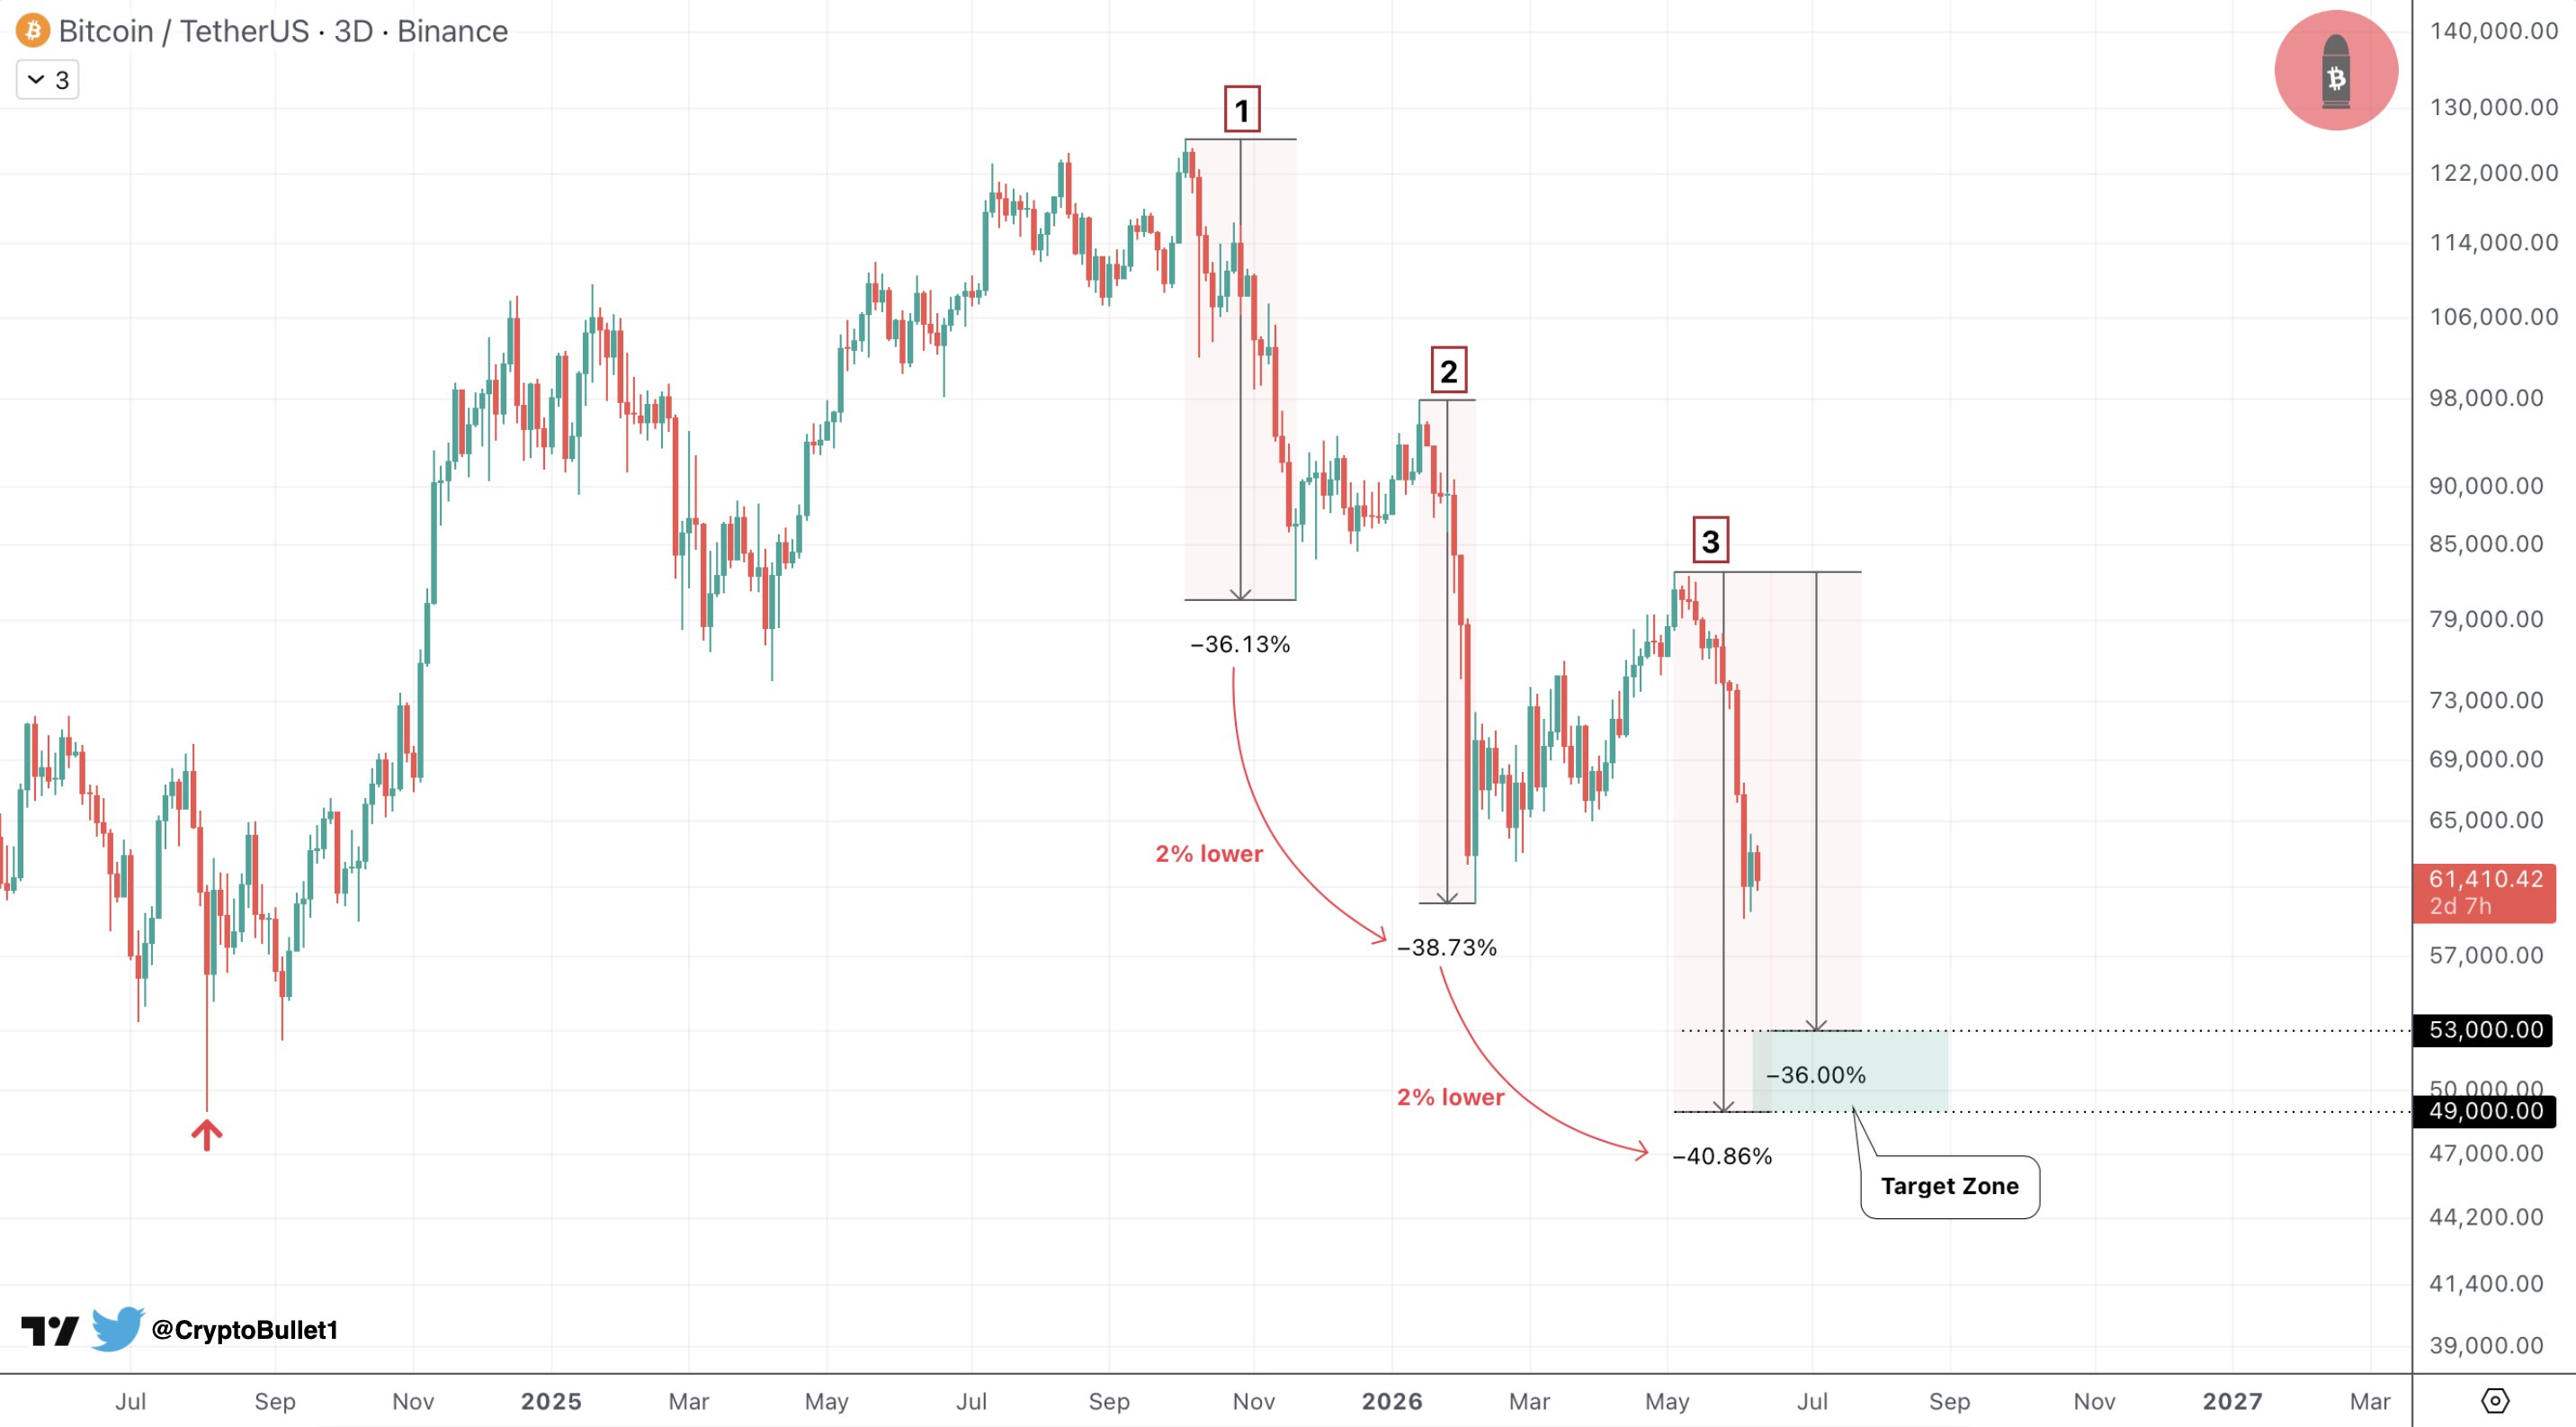
BTC’s latest leg down could match its previous 36%–39% declines, putting the next downside target in the $49,000–$53,000 range, according to analyst CryptoBullet.

BTC/USD three-day chart. Source: TradingView/CryptoBullet

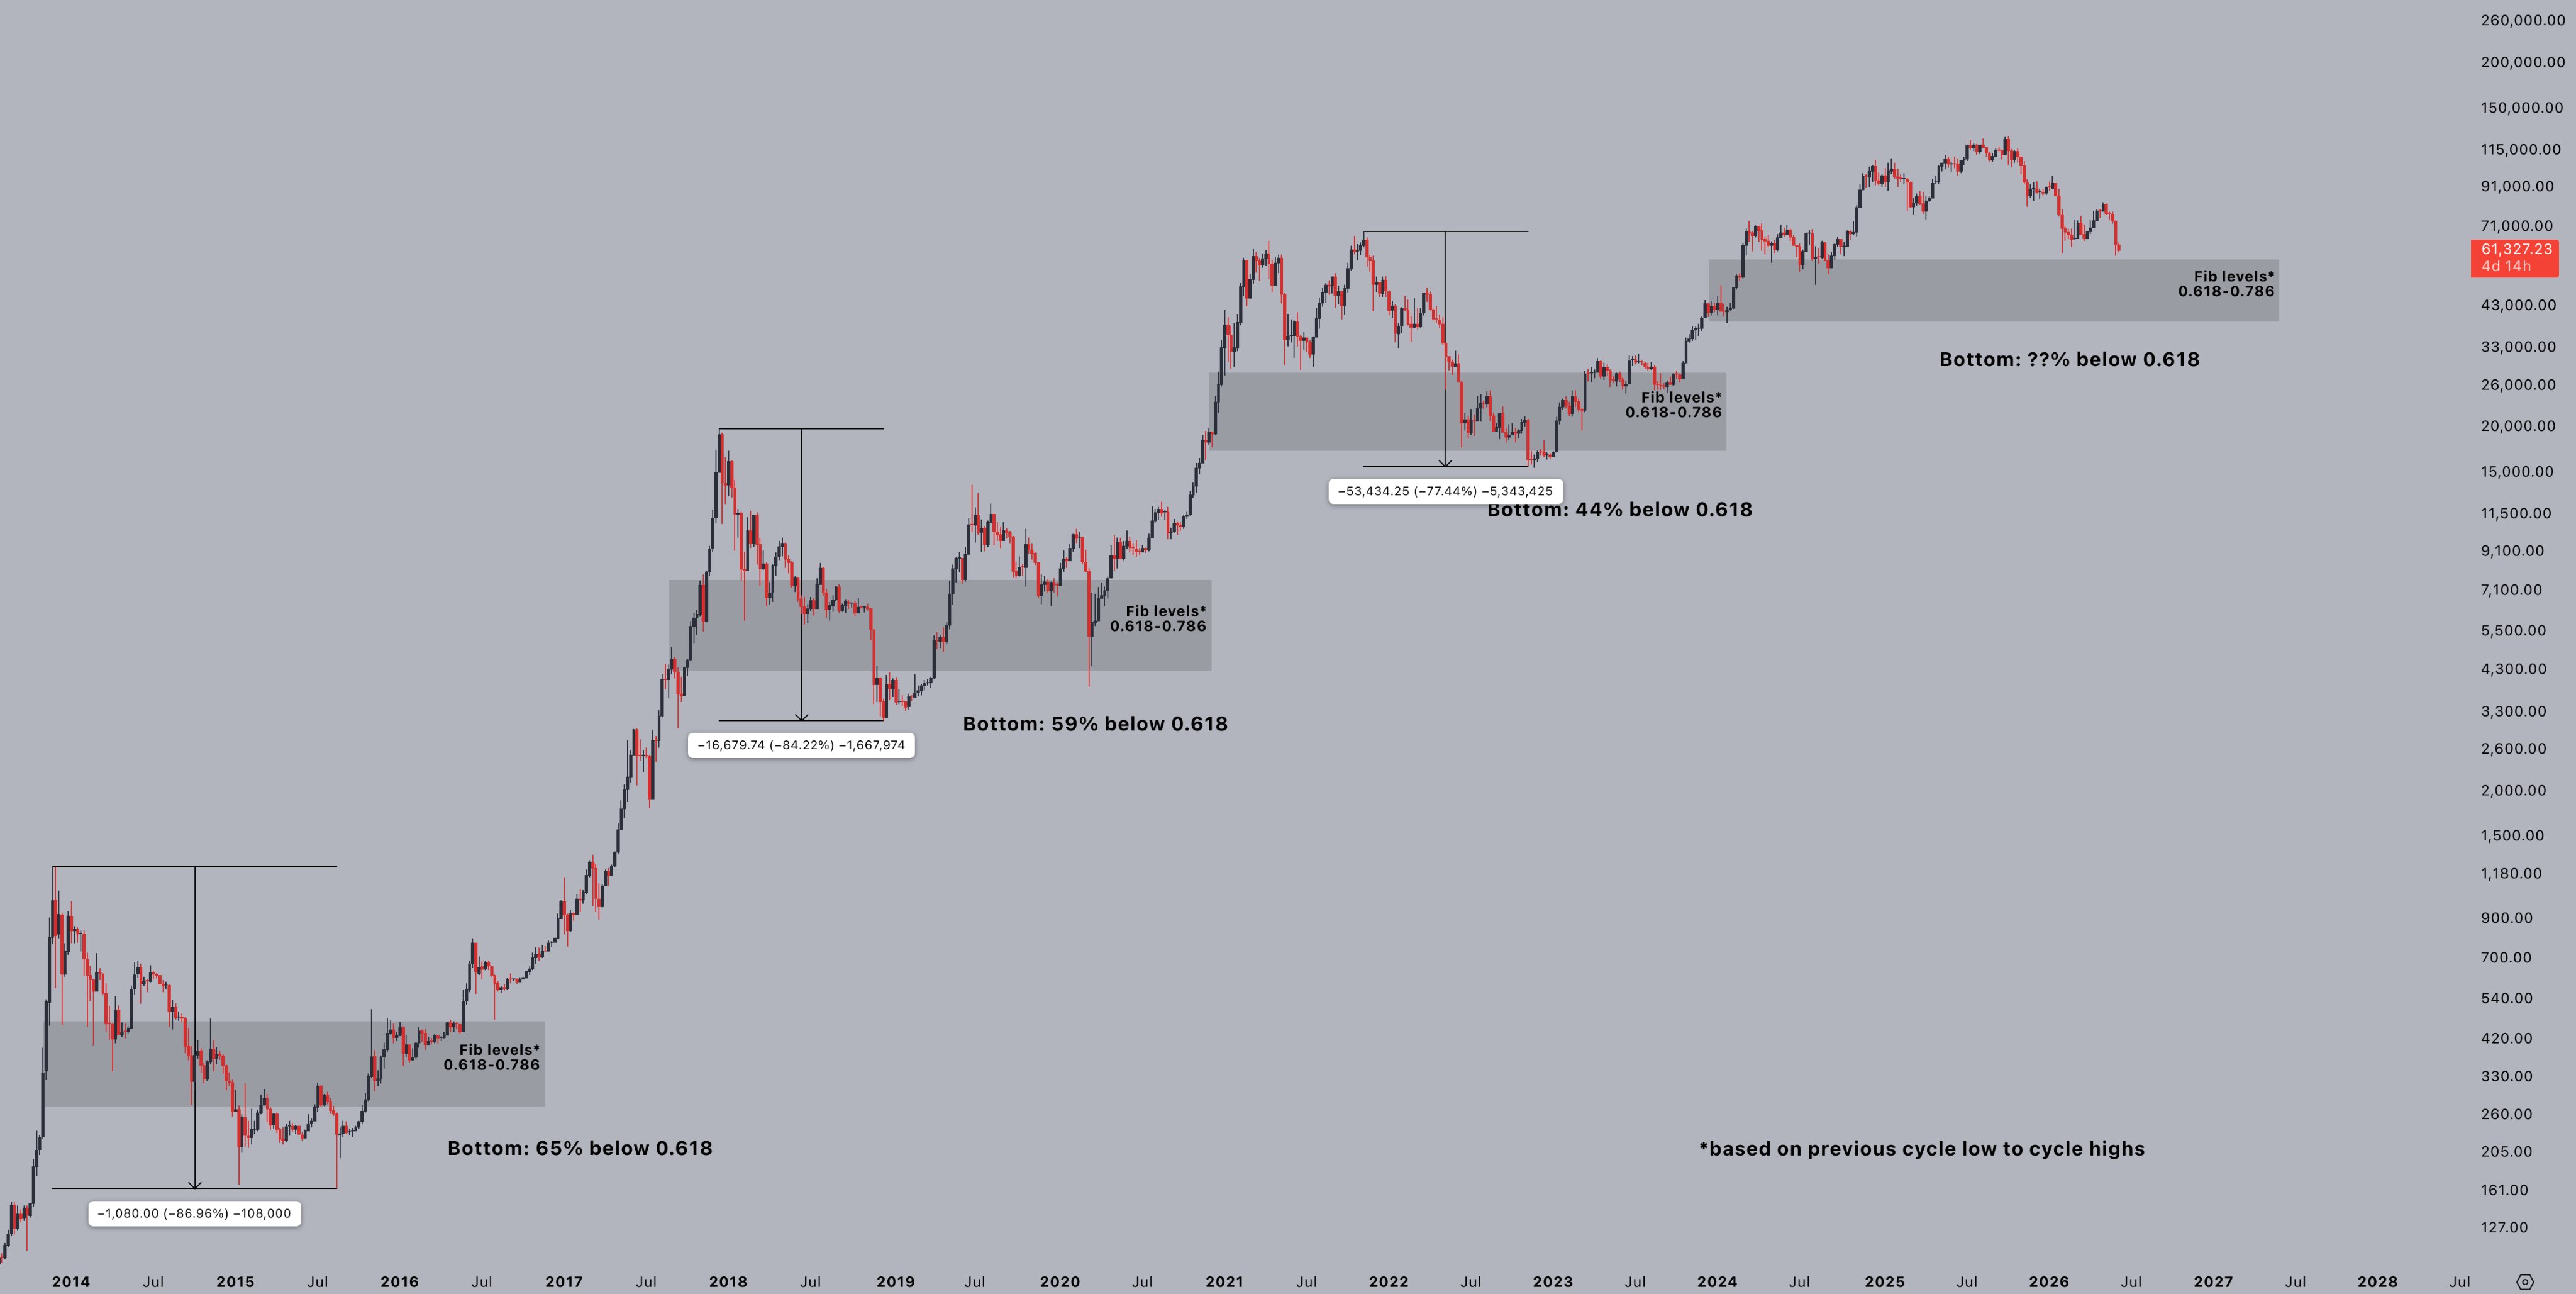
That zone may act as initial support, but analyst Jelle’s Fibonacci model suggests it may not mark the final bear-market floor.

In a Wednesday post, he noted that every BTC bear market has dropped well below its 0.618 Fibonacci retracement before bottoming. Previously, BTC fell 65% below the 0.618 level in 2014–2015, 59% in 2018 and 44% in 2022.

BTC/USD all-time performance chart. Source: TradingView/Jelle

With Bitcoin’s current 0.618 retracement near $57,000–$58,000, even a repeat of the shallower 2022 drawdown would imply a potential bottom near $32,000.

Deeper 2018-style and 2015-style drawdowns would point toward $23,000–$24,000 and $20,000, respectively.