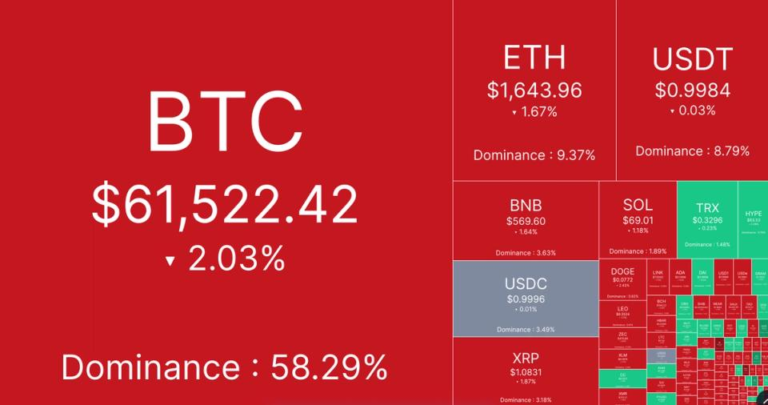
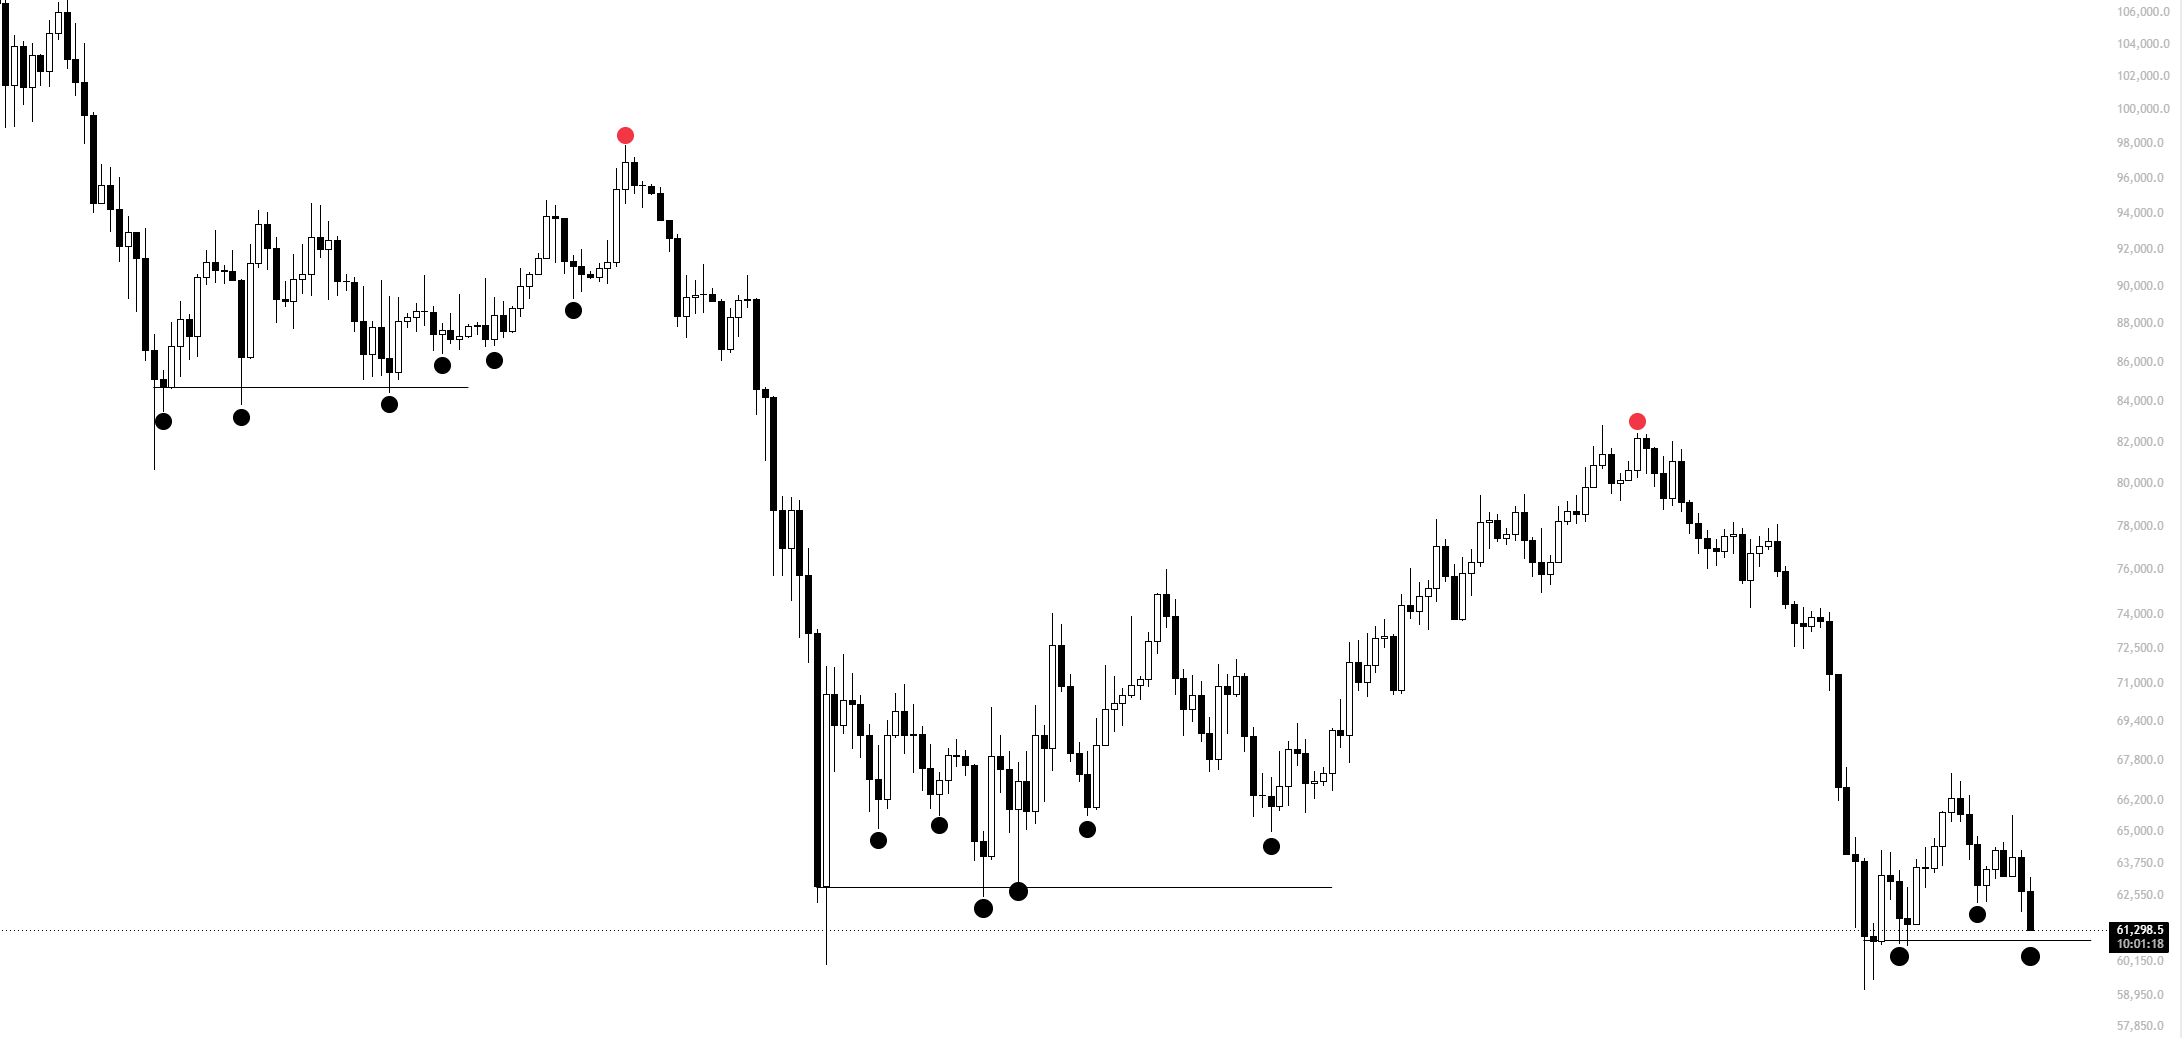
Bitcoin dropped to $59,175 overnight, its lowest point since early June, before recovering to about $61,500 by Thursday morning, per CoinDesk data. Nearly $1 billion worth of futures positions were liquidated across crypto majors, such as bitcoin, ether, solana, and others, to tokenized versions of stocks, such as Micron Technology Inc (MU) and Sandisk (SNDK).
The dip triggered roughly $430 million in long liquidations on bitcoin-tracked futures, or bets on higher prices that were automatically closed as the price fell.
No single catalyst drove the move. Bitcoin has lost about 10% since Monday’s peak near $65,500, pulled lower by the same forces that have dominated all week: a hawkish Fed, six straight weeks of ETF outflows, thinning summer liquidity, and a quarter-end options expiry on June 30 that traders say is keeping the market unstable.
Major market-maker Wintermute had flagged $59,000 as the bear-market low to watch in its Tuesday’s note.
The bounce came from outside crypto. Micron Technology reported quarterly earnings after the close that shattered analyst estimates, sending its shares sharply higher and lifting the broader memory chip complex.
SK Hynix separately disclosed plans for a U.S. stock listing seeking roughly $29 billion, one of the largest offerings ever. Samsung and Kioxia rallied in Asia Thursday morning.
The same AI chip trade that sent the Kospi down 10% on Monday on fears the spending boom was stalling is now the thing steadying crypto, with Micron’s results reading as confirmation that demand for AI memory is structural, not speculative.
The quarter-end remains the week’s live risk. Bitcoin’s $59,000 low held, but $1.6 billion in leveraged long positions sit clustered below $58,000, per CoinGlass, meaning a break there would accelerate the drop.
Thursday’s PCE inflation print, the Fed’s preferred price gauge, is the next data point that could move the market in either direction.
Shares of Strategy Inc. (NASDAQ: MSTR) crossed below $100 on Wednesday for the first time since March 2024, extending a collapse that has erased more than 80% of the stock’s value from its all-time high of approximately $474 reached in November 2024.
The breach of the $100 threshold carries weight beyond the number itself. Strategy, the Bitcoin treasury company led by Executive Chairman Michael Saylor, built its investment thesis around the premise that its leveraged exposure to Bitcoin would generate returns that outpace traditional assets.
That thesis is now under pressure as Bitcoin trades near $61,000 — well below the company’s average acquisition cost of roughly $75,656 per coin.
Strategy holds 847,363 BTC across its treasury, a position valued at approximately $53 billion at current prices. Against an average cost basis implying a total investment closer to $64 billion, the company is sitting on an unrealized paper loss of more than $11 billion. That gap between cost and market value has become a weight on the stock.
The decline accelerated through a series of events over the past six weeks. In May, Strategy used cash reserves to repurchase $1.5 billion in convertible bonds at a discount, cutting its dividend coverage buffer from a target of 24 months down to roughly six months at the low point.
On June 1, the company sold 32 BTC — its first Bitcoin sale since 2022 — to demonstrate that it could cover dividend obligations through asset liquidation if needed. MSTR shares fell nearly 6% on that news.
Strategy’s STRC is under pressure
The company’s preferred stock, STRC, has also come under pressure. The instrument fell to a record low of $83 in mid-June, far below its $100 par value. Strategy has since increased STRC dividend frequency to twice per month and rebuilt cash reserves to approximately $1.1 billion, but the market has not yet returned the preferred stock to par.
Speaking at The Bitcoin Conference, Saylor said Strategy’s STRC preferred stock has become one of the fastest-growing credit products globally, attracting billions in retail capital by offering an 11.5% dividend while leveraging Bitcoin as its underlying capital base.
He argued, at the time, that scaling Bitcoin-backed digital credit products like STRC could significantly expand Bitcoin adoption and drive future price appreciation.
Strategy has not stopped buying Bitcoin. The company added 1,587 BTC for $100 million earlier in June and 520 BTC for $35 million on June 22. But continued accumulation at prices above the current market value has done little to restore confidence among common shareholders.
Decentralized finance platform Abracadabra said Wednesday that it launched emergency measures after its crypto-collateralized stablecoin, Magic Internet Money (MIM), fell 50% below its $1 peg.
“We’re acutely aware of the MIM depeg and are taking emergency actions to remedy the situation,” the team said on Wednesday.
It said effective immediately, it will begin gradually “increasing interest rates across all Cauldrons, including deprecated markets, to encourage debt repayment and reduce the outstanding MIM supply.”
The MIM depeg is a stark reminder that even overcollateralized DeFi stablecoins can be fragile in thin-liquidity environments and bear markets, underscoring the persistent risks of crypto-backed money.
Abracadabra describes itself as an omnichain DeFi lending platform that utilizes interest-bearing tokens as collateral to mint MIM, a dollar-pegged stablecoin that launched in May 2021.
MIM’s troubles began in mid-June, when it slipped to 74 cents before a brief recovery to 89 cents, then plunged to 49 cents on Wednesday, according to CoinMarketCap. The current circulating supply of MIM is about $104 million.
MIM depeg exceeds 50%. Source: CoinMarketCap
“The current depeg creates a natural incentive for borrowers to repay debt at a discount, accelerating supply contraction and strengthening the path back to the peg,” the team said.
“Our priority is simple: restore confidence, improve market structure, and return MIM to a healthy (and liquid) peg.”
Related: DeFi TVL drops 39% in 2026 amid market downturn and record hack activity
By raising Cauldron interest rates, the protocol makes it more expensive for borrowers to maintain positions, encouraging repayment that burns MIM, contracts supply and helps restore the peg.
It comes less than 10 days after Abracadabra injected $100,000 into its primary liquidity pool on Curve Finance on June 15, when the stablecoin first slipped from its peg.
“This will serve as a base for liquidity to restore balance across Curve Pools after unexpected liquidity withdrawals due to recent DeFi incentive strategy changes,” it said at the time.
Cauldron liquidity is thin
The DeFi stablecoin is minted by borrowing against yield-bearing tokens in Abracadabra’s “Cauldrons,” but it relies on crypto collateral and deep liquidity pools, primarily on the Curve Finance platform, to maintain its $1 peg.
Thin and imbalanced liquidity in decentralized exchange pools is fueling selling pressure that makes the stablecoin vulnerable to further depegging, potentially amplified by broader market caution.
The broader crypto market has fallen about 3%, or roughly $60 billion, in the past 24 hours, with Bitcoin briefly dropping below $60,000.
Magazine: Japanese pension fund tips 1% in crypto, G7 urges action on NK hackers: Asia Express
Bitcoin’s BTC$61,650.42 price drop ahead of Friday’s quarterly options settlement has once again cast doubt on the popular “max pain theory.”
The max pain level for this expiry stands at $72,000, significantly above current spot prices of around $61,700. On Friday at 8:00 ET, options worth $10 billion will expire on Deribit, the world’s largest crypto options exchange.
Max pain, as the name suggests, refers to the price level where options buyers – those who purchased call and put contracts to hedge against volatility – would lose the most money on expiry. In that scenario, option buyers suffer maximum losses, while their counter parties who sold options (also known as writers) stand to benefit.
The theory suggests that ahead of expiry, these option writers actively try to push the spot price toward the max pain level, effectively pinning bitcoin there. Crypto social media has long embraced the idea, particularly after BTC appeared to gravitate toward the max pain point ahead of several monthly and quarterly settlements in 2020–2021. That pattern, even if partly coincidental and driven by other market forces, helped solidify belief in the theory.
A coalition of four major law enforcement organizations and a separate group of nearly 100 Catholic leaders sent letters Tuesday warning that a provision in the Digital Asset Market Clarity Act would weaken the oversight tools investigators and prosecutors rely on to combat financial crime.
The law enforcement letter, addressed to Acting Attorney General Todd Blanche and Patrick Witt, executive director of the President’s Council of Advisors for Digital Assets, came from the National District Attorneys Association, the National Association of Assistant United States Attorneys, the International Association of Chiefs of Police, and the National Sheriffs’ Association.
Together, the groups represent more than 70,000 prosecutors, sheriffs, chiefs of police, investigators, and other law enforcement professionals.
Their central concern is Section 604 of the bill — a provision that incorporates the Blockchain Regulatory Certainty Act, or BRCA, which would establish that a developer or infrastructure provider who cannot move or control a user’s digital assets is not a money transmitter under federal law.
Proponents argue the language is essential to protect software developers from criminal prosecution. Law enforcement groups counter that the exemptions are too broad.
“As currently drafted, Section 604 risks creating gaps in oversight and accountability that could impede those efforts,” the groups wrote, adding that their concern is “not with individuals who merely write or publish software code, nor with responsible technological innovation,” but rather with exemptions that could shield actors who facilitate the movement of digital assets while obstructing investigators.
The groups also contend the bill falls short on anti-money laundering and countering the financing of terrorism requirements, pointing out it does not establish suspicious activity monitoring and reporting obligations comparable to those applied to traditional financial intermediaries. They warned that certain provisions could exempt mixers, tumblers, and some decentralized finance businesses from AML and know-your-customer requirements.
The other letter, sent to Senate Majority Leader John Thune and Senate Democratic Leader Charles Schumer, carried signatures from roughly 80 organizations and leaders, including the Alliance to End Human Trafficking, the Jesuit Conference’s Office of Justice and Ecology, and dozens of Catholic sisters and survivor advocates.
“Human traffickers are quick to exploit new technologies when oversight fails to keep pace,” the groups wrote, arguing that the bill’s regulatory gaps could make it harder to trace financial flows tied to trafficking, child exploitation, and organized crime.
Background: What the CLARITY Act would do
H.R. 3633, the Digital Asset Market Clarity Act, is the most significant piece of crypto legislation to advance in Congress in years. The House passed it 294-134 in July 2025. The Senate Banking Committee cleared the bill 15-9 in May 2026, placing it on the Senate Legislative Calendar eligible for a floor vote.
The bill divides oversight of digital assets between the Securities and Exchange Commission and the Commodity Futures Trading Commission, creating a framework for crypto exchanges, brokers, stablecoin issuers, and DeFi participants.
The Trump administration has made the legislation a priority, and crypto industry groups have pushed to keep Section 604’s developer protections intact.
To advance in the Senate, the bill needs 60 votes — a threshold that gives moderate Democrats significant leverage. Senators Mark Warner of Virginia and Catherine Cortez Masto of Nevada have both tied their support to law enforcement’s sign-off on Section 604, making the opposition letters a direct threat to the bill’s prospects.
Yesterday, Congress scheduled a July 17 hearing in New York on the CLARITY Act, a major crypto market structure bill that would divide oversight between the SEC and CFTC, as lawmakers push toward potential passage later this year.
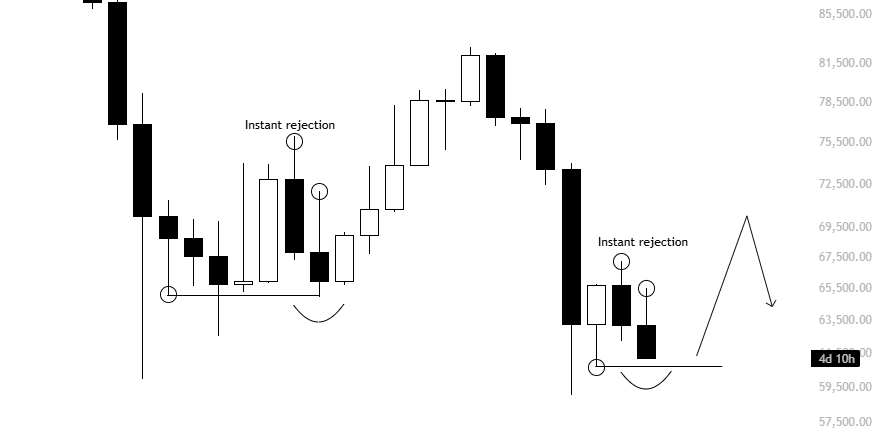
Traders had warned of increasing short interest with rising funding rates, boosting the odds of a capitulatory move lower.
“It’s time to start bouncing soon on the LTF,” trader Killa wrote in ongoing commentary on X, referring to low time frames.
“Range bound till proven otherwise.”
BTC/USD chart segment. Source: Killa/X
Killa uploaded a further chart showing a relief bounce toward $70,000, being due following the bounce.
BTC/USD chart segment. Source: Killa/X
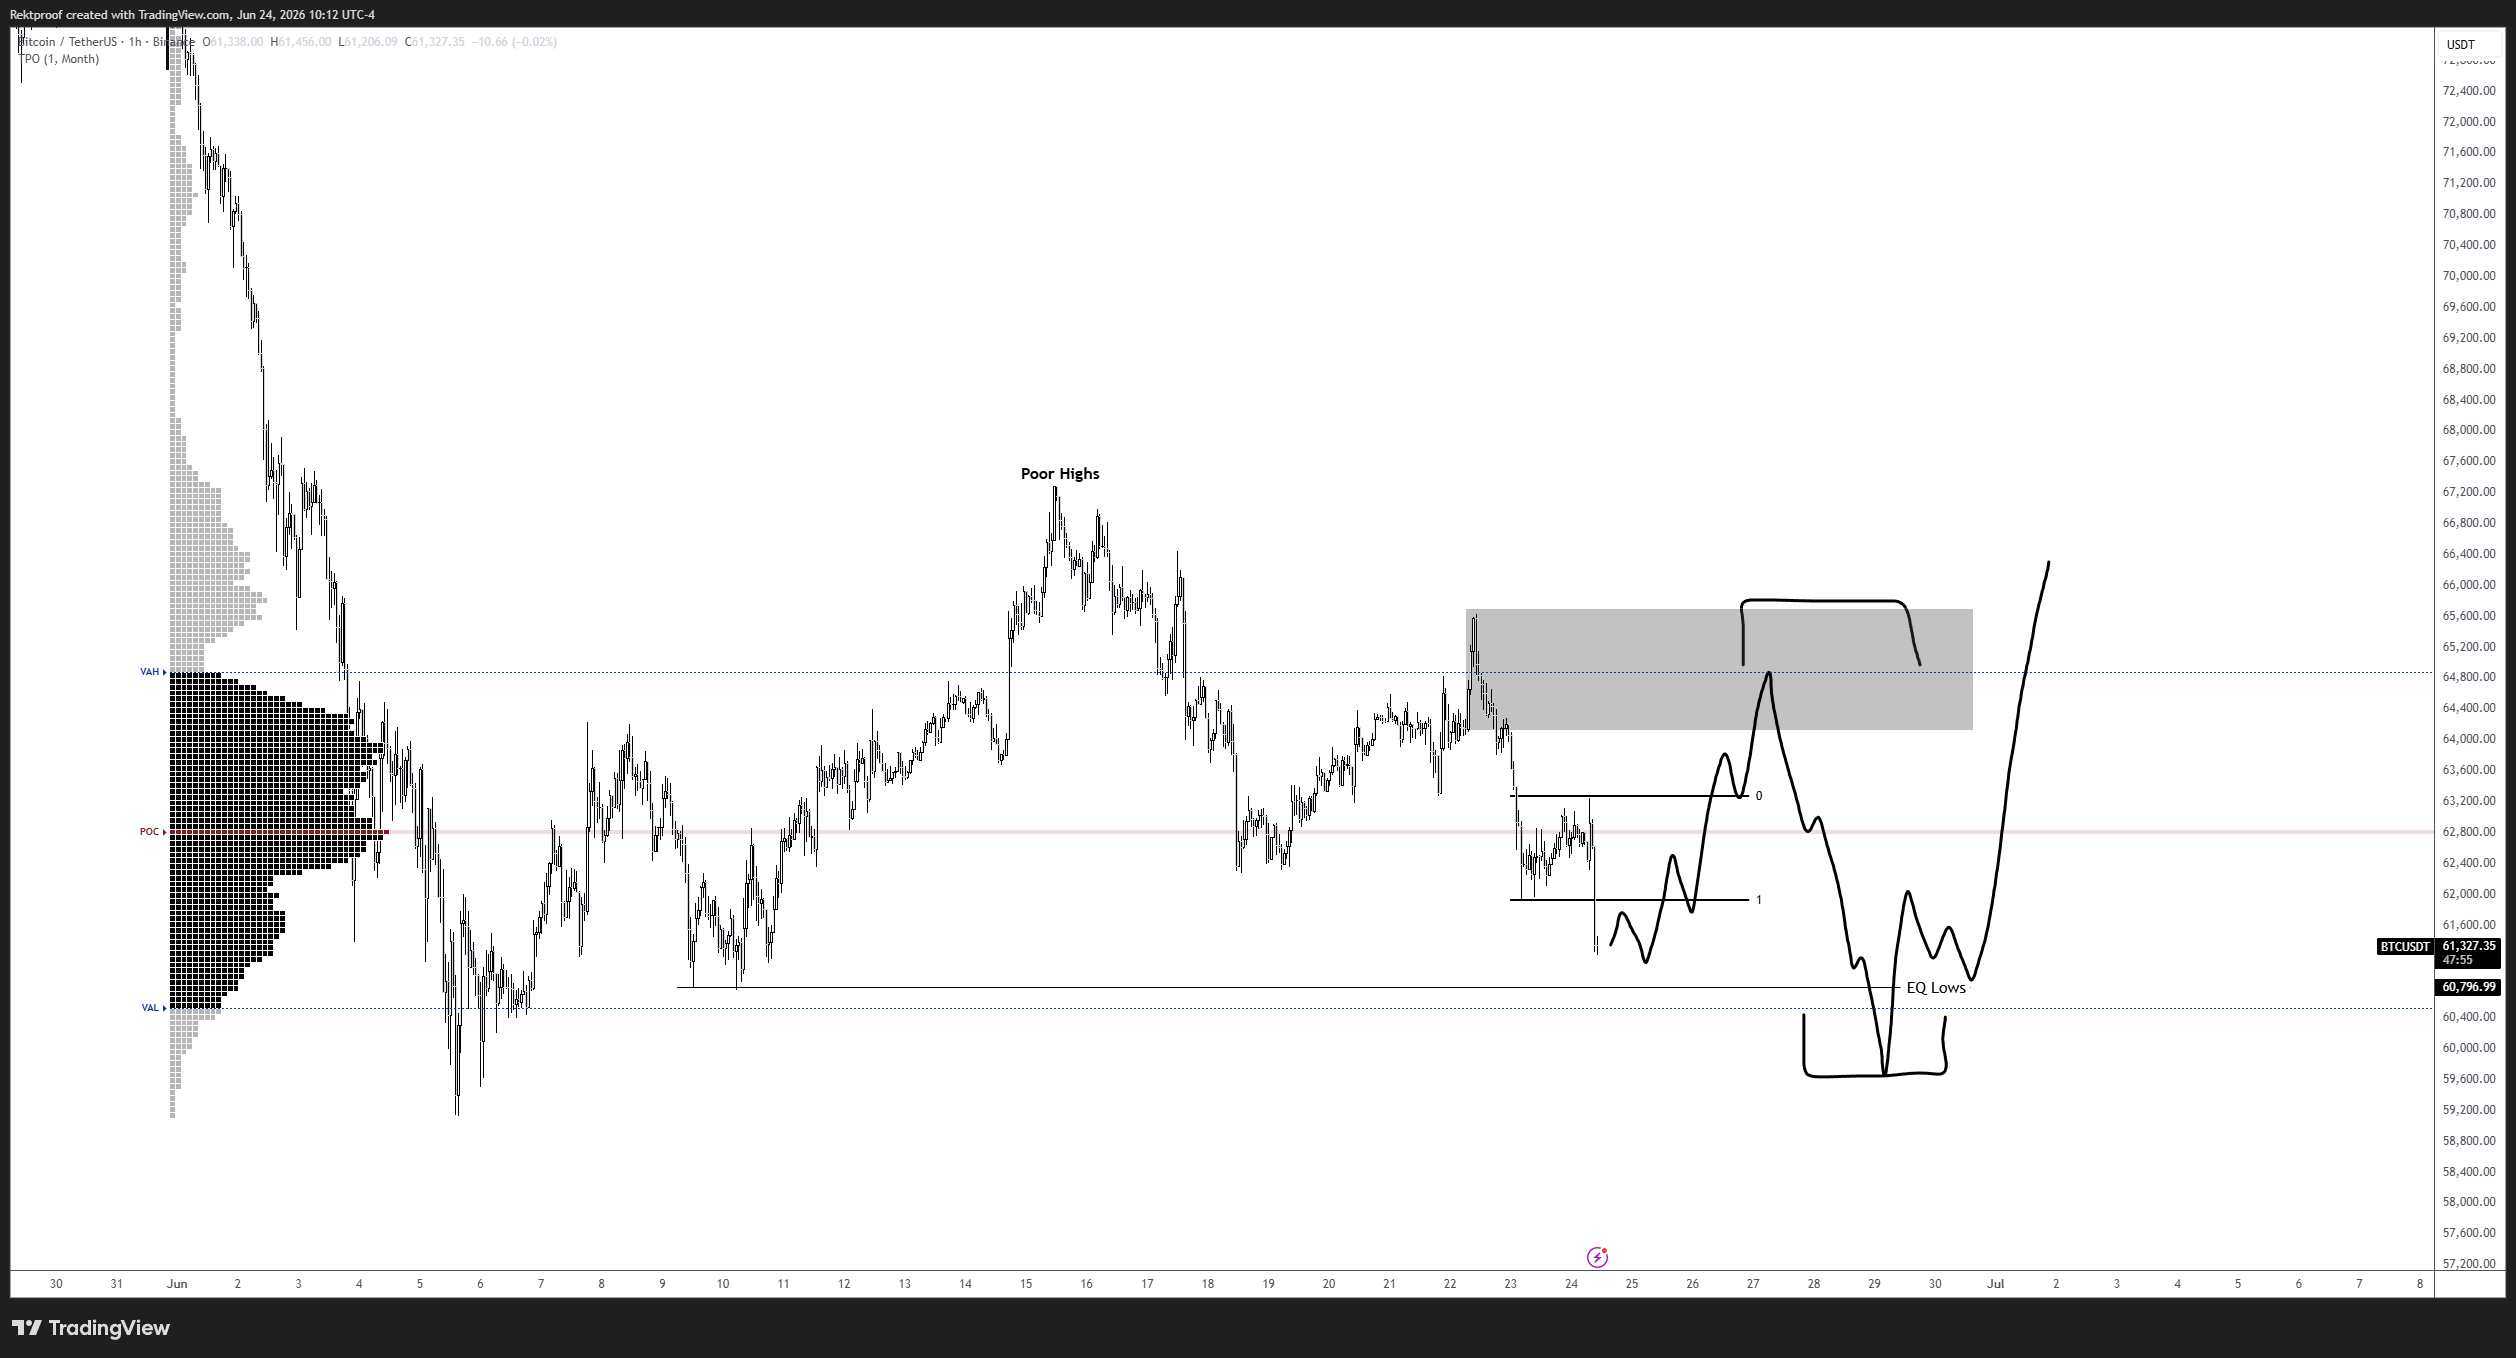
Fellow trader RektProof had a broadly similar forecast, seeing BTC/USD trading in a range with $60,000 as its floor “for the rest of the month.”
“Overall, a move to supply and back down to the EQ lows before forming back to poor highs + 70k,” he added.
BTC/USDT one-hour chart. Source: RektProof/X
Stocks tread water as Hormuz oil transit progresses
On a macro level, US stocks appeared to have already priced in relief from the US-Iran peace deal.
Related: BTC price four-year trend calls for $76K as analysis says Bitcoin ‘not broken’
Upside was limited at the open despite US President Donald Trump offering further details of mutual cooperation between the two sides.
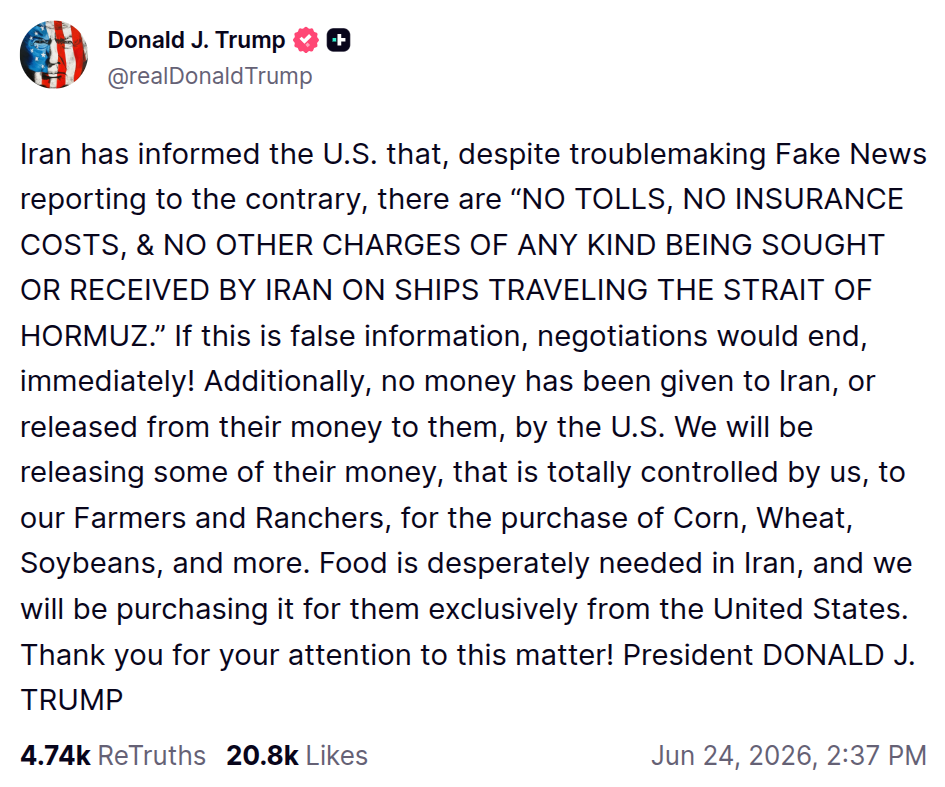
Trump specifically made reference to the Strait of Hormuz oil transit route, writing in a post on Truth Social that there would be “no tolls, no insurance costs, & no other charges of any kind being sought or received by Iran on ships traveling” via the route.
Source: Truth Social
The S&P 500 traded up 0.4% at the time of writing, while the Nasdaq Composite Index even turned slightly negative on the day.
Earlier, Cointelegraph reported on several factors keeping risk-asset enthusiasm in check, including forward earnings guidance by tech giant Micron Technologies and the May print of the Personal Consumption Expenditures (PCE) index, due out on Wednesday and Thursday, respectively.
Blockchain project MemeCore’s M token collapsed about 74% over 24 hours, sliding from a high near $2.92 to as low as $0.51 before steadying around $0.74, with no exploit, hack or announcement to account for the drop.
The fall erased close to $3 billion in market value. M’s market capitalization dropped below $1 billion, to about $969 million, from roughly $3.8 billion before the slide, per CoinDesk data.
Trading was thin relative to the size of the move, with only about $21 million changing hands over the day.
No confirmed catalyst has emerged. But M is a token that widely-known onchain investigator ZachXBT publicly questioned months ago.
In an April post, he asked why the exchange Kraken had listed M for spot trading in July 2025 and how it cleared the exchange’s due diligence, alleging that insiders had “manipulated the price” to a $6 billion market capitalization and an $18 billion fully diluted valuation. The latter is the value the token would carry if every coin that will ever exist were already circulating.
Why did Kraken list $M (Memecore) on July 3, 2025 for spot and how did it pass due diligence?
$7.9M in suspicious Kraken withdrawals to 18 newly created addresses with 11.7 $M sitting total (valued at $39.8M now).
South Korea’s financial regulator folded token securities infrastructure into a broader overhaul of the country’s capital markets, alongside plans for faster settlement, longer trading hours and greater use of artificial intelligence.
On Tuesday, the Financial Services Commission (FSC) said it had launched a capital market infrastructure review meeting to coordinate reforms across government agencies and market operators. According to the FSC, plans for token securities will be further discussed separately through a public-private council before being linked to the wider initiative.
The initiative includes a roadmap for shortening the securities settlement cycle, expected by October, and a Korea Securities Depository (KSD) system for settling over-the-counter trades in unlisted shares and fractional investment products by the end of 2026.
The move places tokenized securities within the country’s broader effort to modernize traditional financial markets, potentially bringing blockchain-based investment products closer to systems used for mainstream securities settlement and trading.
FSC Vice Chairman Kwon Dae-young said the initiative would build on broader efforts to improve the capital market, guided by four policy priorities: trust, shareholder protection, innovation and market access.
South Korea prepares token securities framework for 2027
South Korea’s token securities initiative predates the latest capital-market review. In January, the National Assembly approved amendments recognizing blockchain-based distributed ledgers as valid securities registries and permitting the issuance and circulation of token securities.
According to the FSC, the framework is scheduled to take effect in February 2027, after regulators complete subordinate rules and supporting infrastructure. At the second meeting of its public-private token securities council in May, the FSC said it was targeting July for the release of proposed subordinate regulations and guidelines.
Related: South Korea reviews Hana Bank’s Dunamu stake under banking rules: Report
Technical infrastructure is also under development. Samsung SDS said in May that it had won a KSD contract to build a token securities management platform that connects the depository’s existing electronic securities account system to blockchain-based data. The company aims to complete the platform by February 2027, when the new framework is scheduled to take effect.
According to the FSC, detailed token securities plans will continue to be discussed by the public-private council before being linked to the broader review, part of South Korea’s preparations for a real-time, continuously accessible and integrated digital market.
Magazine: Japanese pension fund tips 1% in crypto, G7 urges action on NK hackers: Asia Express
US President Donald Trump cancelled the signing ceremony for a housing bill containing a ban on a central bank digital currency (CBDC) as he looked for Republicans in Congress to prioritize a controversial voting bill.
In a Wednesday morning Truth Social post, Trump said that the signing for the 21st Century ROAD to Housing Act, passed by the US Senate and House of Representatives, would be cancelled “until such time as we pass the desperately needed SAVE America Act.”
Source: Donald Trump
The housing bill, passed by the House on Tuesday, included a provision barring the US Federal Reserve from issuing or creating a CBDC “or any digital asset that is substantially similar” until the end of 2030. However, the legislation also included a carve-out for stablecoins, allowing “dollar-denominated currency that is open, permissionless and private.”
Many had expected Trump to sign the bill, aimed at tackling housing affordability, into law on Wednesday without issues. However, the president said in March that he would “not sign other bills” until the SAVE America Act was passed. The legislation would require voters to provide proof of US citizenship in person to register, with critics saying the measure would disenfranchise citizens already eligible to vote.
Related: US Senate passes housing bill with CBDC ban until 2030
Senate Republicans largely supported the housing bill, which passed the chamber in a 85-5 vote on Monday. Tim Scott, the Republican who chairs the Senate Banking Committee, expressed support for the legislation as recently as Wednesday morning before Trump’s announcement, as did Democratic Senator Elizabeth Warren, who co-sponsored the bill.
“I don’t say this often these days, but Congress actually passed something good,” said Warren.
Could Trump’s position also impact crypto market structure?
Given the president’s opposition to signing any bill into law other than the SAVE America Act, it’s unclear whether Trump also intends to veto or delay signing of crypto-related bills.
As of Wednesday, the US Senate was still waiting to potentially vote on the Digital Asset Market Clarity (CLARITY) Act, a bill expected to change the roles of financial regulators in overseeing and enforcing digital asset laws. However, Trump said in May that he intended to codify a “future-proof digital asset market structure,” likely referring to CLARITY.
If Trump vetoes either bill, Congress could override him with a two-thirds majority in both chambers.
Magazine: AI is banking the unbanked in Africa… faster than crypto
By the year 2036, Bitcoin mining looks nothing like it did five years ago, much less ten. Long gone is the model of Bitcoin miners that dominated the landscape of the early to mid-2020’s. These large, often publicly traded, mining companies looked for large tranches of cheap power in mostly first-world countries they could monetize at scale. These corporations did not generate their own energy, nor did most design and manufacture their ASICs. They looked for a confluence of attractive power terms from an electric utility, available land near substation infrastructure, and timed the purchase of ASICs for as short a payback period as possible.
The compressing margins had already strained this business model by the middle of the decade. Then the explosion of artificial intelligence and high-performance compute (AI/HPC) data centers created a more profitable use of grid connected electricity. This effectively ended the availability of power for public Bitcoin miners in the markets they had adapted for. Many simply took their model and altered it slightly to accommodate the AI/HPC data center buildout. The process was similar, and the companies who successfully pivoted were rewarded by their shareholders. The opposite was true for those public mining companies who failed to build more traditional data centers
As the era of public Bitcoin mining companies ended, governments started to notice the advantages of Bitcoin mining for expanding and managing a national grid. Rapid growth in generation commonly outpaced transmission capacity necessary for broader grid connectivity, creating pockets of electricity that could not be delivered and utilized. Several nations possessed surplus energy at off-peak hours, but deficits during peaks in the morning and evenings. Many of the grids throughout the Global South lacked a buyer or high-capacity transmission infrastructure to export surplus energy on day ahead markets.
There was a growing realization that mining Bitcoin with the excess electricity was akin to exporting the power over the internet, rendering the expensive cross-border transmission infrastructure unnecessary for this specific sales activity. Countries began to use the design of mineral extraction deals as archetypes. In those arrangements, a joint venture or special purpose vehicle was formed between a foreign mining company and the government. The mining company would extract the mineral, but the country received a royalty in the form of a predetermined percentage of profits given it was the resource of the nation.
The sovereign level Bitcoin mining deals were similar. The surplus power was a national asset just like minerals in the ground, but the difference being the temporal aspect of the electricity. Every hour that excess was not monetized, that electricity was unproductive, thus minutely changing the economics of the power plant that generated the electricity. If hours turned into days, months or even years, the finances of the mostly state-owned electric utilities deteriorated. Countries increasingly followed the pioneering nations like Bhutan into similar sovereign level Bitcoin mining deals as they realized they couldn’t afford inaction.
In the late 2020’s, the U.S. and China played tug-of-war with the world economies via their digital currencies. The Americans exported the dollar through stablecoins, while the Chinese offered cheap debt if denominated in the Renminbi and offered swap lines with countries in the Digital Yuan, their central bank digital currency issued directly from the Bank of China. “Middle powers”, or countries with excelling economies and ability to influence their region but were a rung below great power status, sought to extricate themselves from the middle of the American-Sino economic struggle. For many, Bitcoin was such an escape hatch.
Take for instance the Strategic Bitcoin Reserve (SBR) legislative proposal in Brazil in 2026. Not only did it codify the country’s ability to put up to 5% of national reserves into Bitcoin, but it also abolished capital gains tax on Bitcoin and allowed payment of taxes in Bitcoin. Other middle powers followed suit with similar adoption measures. By leaning into alignment at the state or citizenry level with a neutral reserve asset not controlled by either America or China, they were able to avoid the trap of choosing one financial system and boxing themselves out of the other.
For those countries that assumed this strategy and possessed any measure of energy independence, Bitcoin mining became the most cost-effective method of accumulation. Some energy heretofore exported to neighbors was kept for the purpose of Bitcoin mining. Abundant energy potential without nearby offtake or grid connectivity that was previously deemed nonviable for development was now prioritized. Such projects now became a source of pride as they expanded the energy portfolio of the country while simultaneously creating a measure of economic independence.
Examples of this type of adoption were pockmarked all over the globe. Russia partially pioneered the strategy by turning isolated energy production in Siberia into sanction proof assets during the war with Ukraine. Turkey lessened exports to countries like Bulgaria and Iraq and further developed hydroelectric generation in the eastern part of the nation. Brazil and India similarly developed the plentiful hydroelectric potential in the Amazon and Himalayas respectively, far from population centers along the coast. Indonesia and Malaysia finally found a suitable use for the vast geothermal energy on Borneo Island. Ethiopia turned their private electricity sales to Bitcoin miners into more of a state pursuit with profit share between miners and their sovereign wealth fund.
These state involved Bitcoin mining operations served as a sandbox to advance grid management practices using curtailable electric load or reserve capacity. While pundits for years argued whether battery energy storage systems (BESS) or Bitcoin mining was the better dispatchable demand, it turned out the answer was a combination of the two because of differing and complimentary characteristics. Bitcoin mining can handle large scale load shedding or absorption for long stretches of time, while batteries can respond in milliseconds with precision but lack long-term management ability due to finite storage capacity and limited cycles over their lifespan.
The combination of economic resiliency and grid improvement that these nations enjoyed from Bitcoin mining created envy in their regional neighbors. In about half a decade, sovereign level Bitcoin mining projects went from viewed as risky to essential. Even countries with expensive electricity tariffs found it more economical to institute Bitcoin mining than to deal with the variability of renewables with BESS alone. ASICs, even ones several generations old, sold at a premium for a time as the sudden FOMO-driven demand took hold. Before long, it was more unique to find a ministry of energy without Bitcoin mining integration than one with such a program.
Now that it is 2036, we will experience the next halving event this year in which the block reward will drop to 0.39 Bitcoin per block. Luckily, Bitcoin becoming extremely valuable as a global macro asset, exceeding the market cap of gold, caused nations to use the digital asset as a neutral reserve asset in trade between different economic and currency blocks. This drove more large transfers to the base chain for immutability, subsequently increasing revenue from fee collection which surpassed the value of block rewards. Still, the margins of mining have continued to compress because of global adoption at the state level and created an area of geopolitical competition.
Early Bitcoin enthusiasts lament the state capture of the mining industry, but unfortunately it was inevitable from a game theoretical perspective. As Bitcoin gained adoption in the underpinning of the global financial system, the production of the asset became an issue of geopolitical importance. No private industry had the ability to compete with national governments in the aspects of scale, coordination and control of energy. In a sense, the only way to avoid the government concentration of Bitcoin mining would have been for the Bitcoin network to stall in its adoption somewhere short of becoming the most prominent neutral reserve asset on the planet. If that had been the case, Bitcoin mining would have remained a private sector industry, but the network would have never gained significance beyond a niche alternative asset.
That’s not to say that the mining industry is operated completely by governments. Public private partnerships are the backbone of the space, much like the energy industry of ten years ago. While petrochemical companies are private sector entities, they are heavily reliant on licensed government-owned oil and gas deposits. Similarly, independent power providers build electric generation facilities to sell energy for a profit, but they must jump through regulatory hoops and market to an electric utility that is at a minimum under government oversight, if not owned outright. Bitcoin mining began to operate under a similar paradigm in that private companies built and operated the data centers but with government sanctioned contracts outside of very rare circumstances.
The companies making the most profit in the space are those that design and manufacture ASICs. These companies are highly specialized and export controlled in the ways that chip companies were in the 2020s during the initial AI boom. These corporations are domiciled in either the U.S., China, or countries closely aligned with one of the two. Other countries could not compete with the chip design advances and other technological byproducts of the defense tech race between the two great powers.
Given that mining efficiency is a source of national advantage, the research and development of machines that provide that edge has been partially funded by government grants and spurred by classified technological information. In exchange for that aid, the government disqualifies or approves foreign sales through legislation that looks similar to International Traffic in Arms Regulations (ITAR) or the CHIPS Act. Access to cutting edge ASICs by countries not sophisticated enough to design and manufacture their own are sweeteners for trade deals much like access to NVIDIA chips were during the AI boom.
While the cypherpunks of the early part of the century would bristle at the nation state involvement of Bitcoin mining, in an odd way the decentralization of the network is as strong as ever. The proliferation of hash rate has guaranteed that no single actor could ever attack the network. Additionally, any emerging threats to the network created by a single nation would quickly supersede disagreements and temporarily unite the rest of the world against that country as a rogue actor threatening the global financial system. While many countries kept their fiat currencies as the backbone of their economies, every country on earth recognizes the value of Bitcoin therefore allowing individuals to live on a Bitcoin standard in every corner of the world. If Satoshi had to choose between decentralization of money or the proof of work algorithm, he likely would have chosen the former. Let’s hope that’s the case at least, because that’s what happened.
This piece is featured in the latest Print edition of Bitcoin Magazine, The 2036 Issue. We’re sharing it here as an early look at the ideas explored throughout the full issue.