Home Blog Page 837

Trump’s cyber strategy vows to ‘support the security’ of cryptocurrencies and blockchain

0

The Trump administration’s new national cyber strategy places the security of cryptocurrencies and blockchain technologies within the United States’ broader push to maintain leadership in emerging technology.

In a section focused on maintaining “superiority in critical and emerging technologies,” the document states that the government will support the security of “cryptocurrencies and blockchain technologies.”

The statement appears in President Trump’s Cyber Strategy for America, which outlines six policy pillars meant to guide federal cyber policy, including securing infrastructure, modernizing federal networks and strengthening U.S. advantages in areas such as artificial intelligence and quantum computing.

“We will build secure technologies and supply chains that protect user privacy from design to deployment, including supporting the security of cryptocurrencies and blockchain technologies. We will promote the adoption of post-quantum cryptography and secure quantum computing,” according to the document.

“And we will secure the AI technology stack—including our data centers—and promote innovation in AI security,” the document added.

By placing blockchain security alongside AI and post-quantum cryptography, the strategy frames decentralized financial infrastructure as part of the nation’s technology competition with foreign rivals.

The strategy does not introduce specific crypto regulations. Still, the language signals that federal policymakers see securing blockchain systems as part of protecting economic and technological leadership.

Still, it further underscores the Trump administration’s commitment to the cryptocurrency space (which came under scrutiny recently), a commitment he has supported since his 2024 campaign.

In July of that year, Trump addressed the Bitcoin 2024 conference in Nashville, promising to make the United States the “crypto capital of the planet” and a “Bitcoin superpower.” He pledged to end what he described as an anti-crypto regulatory push and proposed creating a national Bitcoin stockpile.

In early 2025, he directed the creation of a Strategic Bitcoin Reserve using seized bitcoin and launched a presidential working group on digital assets, while prohibiting a U.S. central bank digital currency (although a year has passed, and there’s still no reserve). Later that year, he promoted stablecoin legislation known as the GENIUS Act and continued to push for broader market-structure rules for the industry.

He has also eliminated various Biden-era anti-crypto policies and has seen U.S. lawmakers drop cases against major cryptocurrency firms, including Uniswap, Tron, Coinbase, and Binance.

Coinbase (COIN) says new U.S. tax-reporting rules for crypto are cluttered, confusing

0

Cryptocurrency trading giant Coinbase (COIN) said new U.S. tax reporting requirements are overly onerous for many crypto holders and add unnecessary clutter to the country’s taxation system.

While the idea is that taxable activity on crypto should be reported in the same way as with equities, for example, the rules require reporting transactions in stablecoins — whose value, by definition, doesn’t change — and the tiny amounts spent on the network fees known as gas.

The Nasdaq-listed exchange is currently sending millions of American crypto holders the new 1099-DA forms designed to bring crypto in line with the rest of finance. While all Coinbase’s customers will be affected to some extent, it’s the very large group of retail customers who are being hit with an unnecessary administrative burden on what amounts to small transaction flows, said Lawrence Zlatkin, the company’s VP of tax.

“Frankly, [small retail] transactional flow is so small, I just don’t know why we’re spending efforts as a country focused on them,” Zlatkin said in an interview. “I just think it just does a disservice to people when you’re trading 50 bucks, let’s say, that you get a form like this and you have to report gains or losses. That’s just not what the tax system is supposed to be about.”

For trading platforms, the new system means sharing details of customers’ digital asset transactions with the IRS. Customers are copied in using the form, so they can voluntarily reconcile their gains and losses with the tax authority.

As is often the case when trying to align crypto with traditional finance, however, there are challenges.

This year, Coinbase will provide the IRS only with the gross proceeds of digital asset sales, and not the net value or cost basis. As a result, the onus is on the trader to add what’s missing regarding their crypto acquisition costs and actual tax basis. (Coinbase will begin calculating cost basis on behalf of its customers starting next tax year.)

This will cause some degree of confusion, particularly among people who have never owned assets like stocks. And crypto brings its own level of complexity, given how holdings can be shunted between platforms and swapped in and out of various coins and tokens.

There are other obvious over-reporting wrinkles in the system that need to be ironed out, Zlatkin said, such as the need to report stablecoin holdings, whose value, by design, is fixed.

“People should pay taxes where they have income,” Zlatkin said. “Do you have income on USDC? No, you don’t. So why are we reporting USDC transactions? And we’re reporting those on our exchange as there’s no blanket exemption for USDC. That, to me, clutters the system.”

Gas fees, the small crypto transactions used to pay blockchain costs, just add to the reporting clutter, Zlatkin said.

“Gas fees might be 50 cents, a buck — do we have to disclose that? Is that a valuable use of resources to collect revenue? And I would posit that the answer is no,” he said. “We should focus on where there’s real income to get people to voluntarily comply. But not where there’s no income, such as in stablecoins or in tiny, tiny transactions that are mostly network fees.”

Coinbase’s goal is to educate and, moving forward, to create tools that help make the sometimes onerous task of calculating cost basis on crypto easier, said Ian Unger, the exchange’s director of tax reporting information.

When an equities investor sells stocks or moves their shares between brokers, those transactions come with transfer statements, so the cost basis transfers with it, he pointed out.

“That’s not the world we live in today for crypto assets,’ Unger said in an interview. “There could be a world where some of this does get easier for those who buy and sell on one exchange and want to move to another exchange. But we’re not there yet, and so until we get there, there’ll be a lot of confusion.”

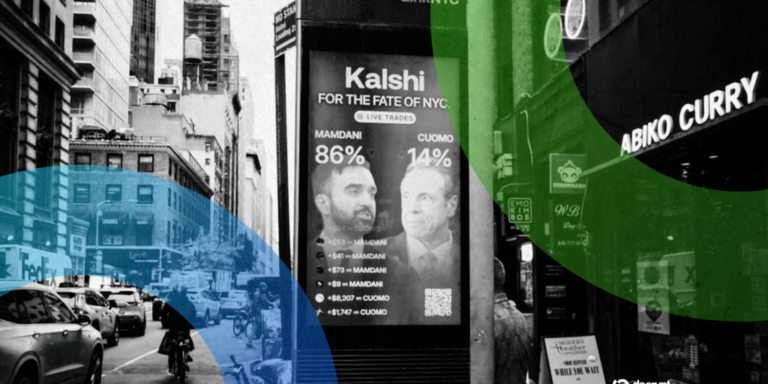
Kalshi Sued Over Refusing to Pay Out Prediction Market After Iran Leader’s Death

0

In brief

  • Kalshi is facing a lawsuit in California over its resolution of a market related to the former Iranian leader.
  • The prediction market opted to utilize a rules provision called the “death carveout,” which effectively resolved and paid the market on its last traded price.
  • Plaintiffs allege the market’s rules were not disclosed prominently enough and are seeking compensation for their positions.

Popular prediction markets platform Kalshi is facing a class action lawsuit related to its handling of a market on the unseating of Iranian leader Ayatollah Ali Khamenei.  

Filed in the District Court for the Central District of California, the suit alleges that the platform ran a “predatory scheme to exploit retail consumers” by creating expectations that it would pay out correct predictions, yet failed to do so in its recent “Ali Khamenei out as Supreme Leader?” market. 

The plaintiffs allege that they expected that in the event of Khameni’s death—which was confirmed by multiple outlets on February 28—holding contracts for Khameni out by March 1 would resolve to “yes,” ultimately paying each share $1 as a correct prediction. 

Instead, the prediction market utilized a “death carveout provision,” a rules clause which indicated that if the Supreme Leader left office “solely because they have died,” then the market would “resolve based on the last traded price.” In other words, with this clause, the exchange did not pay out “yes” shares at $1.00, as expected by the plaintiffs. 

“Plaintiffs and the proposed class members—who correctly predicted the outcome—did not receive the amounts they were promised,” the suit reads. “Plaintiffs Risch and Gliksman, like thousands of other consumers who correctly predicted the outcome, received arbitrary amounts unilaterally determined by [Kalshi] that were significantly lower than their respective contract values.” 

As social media pushback began to build on February 28, the day of Khameni’s death, Kalshi CEO Tarek Monsour took to X to explain his firm’s decisions. 

“We don’t list markets directly tied to death,” he said. “When there are markets where potential outcomes involve death, we design the rules to prevent people from profiting from death. That is what we did here.” 

The plaintiffs allege those rules, like the death carveout “upon which defendants relied was not adequately disclosed to plaintiffs or the proposed class members at the time they entered into their trades.” 

“In these instances, we make the caveat clear in the rules and in the market page, but today is a good learning that we can do more in terms of improving the UX and adding more ways to surface the rules,” said Monsour. 

As a result, the firm reimbursed all fees and net losses, with Monsour highlighting that “no trader lost money” on the market. 

Plaintiffs in the case held around $259.84 worth of positions in the market, which ultimately generated more than $54 million in total trading volume. 

In the suit’s relief requests, plaintiffs and all others similarly situated are requesting compensatory damages representing the full value of “yes” payouts, and “punitive damages in an amount sufficient to punish defendants and deter similar conduct in the future.” 

“We stand by principle and law,” Mansour posted on X in acknowledgement of the suit, reiterating that the firm didn’t deviate from rules, prevented a market where traders can benefit from a person’s death, and made no money on the market. 

Kalshi recently raised funds at an $11 billion valuation as prediction markets surge in popularity and trading volumes. (Disclaimer: Decrypt’s parent company, Dastan, operates the prediction market platform Myriad.) 

Daily Debrief Newsletter

Start every day with the top news stories right now, plus original features, a podcast, videos and more.
The World’s Largest Asset Managers Hold MSTR: Strategy Highlights Massive Institutional Bitcoin Exposure

0

Massive institutional exposure to Strategy stock underscores Wall Street’s deepening link to bitcoin as trillion-dollar asset managers quietly accumulate shares tied to the largest corporate bitcoin treasury. Vanguard, Blackrock, and Global Funds Accumulate Shares as World’s Largest Asset Managers Hold MSTR Strategy (Nasdaq: MSTR), the largest corporate holder of bitcoin, shared on social media platform […]

dLocal and Open English Introduce Bre-B Instant Payments to Eliminate Checkout Friction in Colombia

0

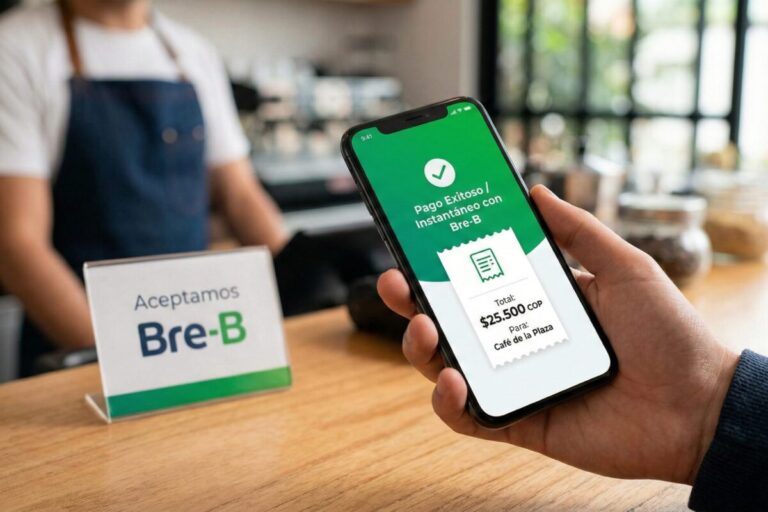
dLocal, the cross-border payment platform connecting global merchants to emerging markets, and Open English, a leading online English-learning platform, have rolled out Bre-B as a new instant payment method for students in Colombia. The nationwide launch highlights both companies’ readiness to activate new local payment rails as soon as they become available.

Overcoming local payment hurdles

In Colombia, digital education continues to grow, but payment access remains uneven. The local market faces several persistent challenges:

  • Credit-card ownership is limited.
  • Transaction declines are common.
  • Cash-based payment flows still heavily rely on offline steps.

For subscription-based services like eLearning, these frictions can interrupt student enrolment and increase checkout drop-offs, making the use of an instant payment network highly relevant.

Leveraging the Bre-B infrastructure

Launched by Banco de la República last October, Bre-B is Colombia’s first government-backed real-time payment infrastructure. It supports 24/7 transfers using digital identifiers known as llaves and has reached nearly 100 million registrations to date.

By integrating this new payment method through dLocal, Open English allows students and corporate clients to pay instantly from participating Colombian banks or digital wallets using a Bre-B llave or QR code. Bre-B was activated within Open English’s existing payment setup, enabling a fast rollout without disrupting the enrolment flow. Payments are confirmed in seconds, removing the need for credit cards or manual verification, so students can access classes shortly after signing up.

Industry perspectives
Andrés Moreno, CEO at Open English

Andrés Moreno, CEO at Open English, commented on the integration:
“If someone is ready to learn, we don’t want payments to slow that down. Making education accessible means acting quickly when local systems change. Bre-B lets students in Colombia pay in a way that works for them. With dLocal, we can do that without compromising how our checkout performs.”

Sofia Posada, head of alternative payment methods at dLocal, added:
“Since Bre-B launched, we’ve seen how quickly people start using it in everyday payments. Rolling this out with Open English is all about putting that rail where it makes sense, helping students pay and get started right away.”

A growing strategic partnership

Beyond the Bre-B rollout in Colombia, dLocal and Open English are continuing to expand their two-year collaboration. The partnership currently supports alternative and local payments across key emerging markets, including Brazil, Argentina, Colombia, Mexico, Chile, Peru, Uruguay, Guatemala, the Dominican Republic, Ecuador, and Turkey.

Looking ahead, upcoming initiatives for the partnership will include:

  • The addition of Buy Now, Pay Later (BNPL) options like Pareto in Argentina and Pagaleve in Brazil.
  • The exploration of B2B and payout flows to support teachers, partners, and internal operations.

Together, these initiatives reflect a shared focus on building payment flows that match local payment behaviour while supporting the scale and operational needs of a global digital education platform.

Inside the Quest at Colossus to Replace Visa and Mastercard With KYC-Less Crypto Cards

0

In brief

  • Colossus is attempting to bypass Visa and Mastercard by building its own sovereign credit card rail using an Ethereum layer-2 network.
  • The company is leveraging its interpretation of the GENIUS Act to operate without the traditional KYC or AML requirements.
  • The startup’s launch follows the total collapse of UnCash, which was shut down by a “corporate guillotine.”

Joseph Delong’s desk looks less like a developer’s workstation these days and more like an electronics repair shop, littered with technology that crypto was pioneered to replace.

That’s because the veteran Ethereum developer and former SushiSwap CTO has accumulated what he describes as a “box of goodies” while building a stablecoin credit card network called Colossus—from point-of-sale test terminals to card readers and manufacturer sample books.

“Trying to get my hands on the hardware, it’s like this arcane knowledge that nobody could get access to,” Delong told Decrypt from his home office in San Antonio, Texas.

Consisting of four employees, the company expects its Ethereum layer-2 scaling network to debut in March, and it’s designed in a way that replaces traditional bank settlement with a sovereign credit card rail that treats users’ account addresses as their sole identity.

Colossus has raised $500,000 in pre-seed funding, according to documents shared with Decrypt. Those investments valued the startup at $10 million, Delong said.

In theory, Colossus will enable users to “burn their cards from their home,” but Delong acknowledged that building a service enabling anyone to pay for things with crypto while circumventing incumbents like Mastercard and Visa has been no easy task. And those efforts may present unforeseen hurdles.

Part of that has to do with disrupting longstanding relationships between businesses involved in the settlement process behind incumbent credit card networks, which weren’t built on the cypherpunk principles that Delong is committed to imbuing Colossus with.

“Many of these entities don’t see this as a problem because they’ve established this relatively high-quality trust relationship over time,” he said. “They’re able to settle in between all these different banks on either promises or a little bit of collateral.”

In a traditional swipe, what’s known as an issuing bank serves as the primary gatekeeper, approving transactions after verifying balances and identities in line with know-your-customer (KYC) and anti-money laundering (AML) requirements.

Issuers fit into a chain of middlemen, which includes member associations like Mastercard and Visa that set their networks’ rules, processors that handle the technical messaging, and acquirers that manage relationships with merchants, such as Worldpay and Fiserv.

Colossus is designed to collapse this entire stack by vertically integrating the issuer, processor, and settlement network. Instead of needing a bank to approve the movement of deposits, the firm’s layer-2 network uses cryptographic signatures to instantly trigger stablecoin transfers. In theory, that means a reduction in overall fees.

The arrangement preserves the role that acquirers fulfill for merchants, serving as the critical distribution mechanism for point-of-sale terminals already sitting in millions of stores. They effectively act as a bridge for Colossus, liquidating on-chain stablecoin transfers into the traditional wire transfers that businesses rely on to pay expenses.

“I don’t know who convinced all these crypto people that merchants want stablecoins,” Delong said. “They generally want something that they can pay their suppliers with.”

Not your keys, not your card

Although merchants may not find much use in holding stablecoins now, the firm is using them in a relatively novel way—collecting as little information about its customers as possible. 

When it comes to the company’s interpretation of a regulatory framework for stablecoins signed in federal law last year, Colossus has determined that the GENIUS Act does not require it to adhere to compliance protocols designed to prevent financial crimes by obtaining personal information like issuers do, nor attain money transmitter licenses across states.

Delong said its network’s sequencer, which orders and batches transactions before sending them to the Ethereum network, may have certain design features to comply with sanctions issued by the U.S. Treasury Department’s Office of Foreign Assets Control (OFAC).

That would essentially filter transactions through a centralized door, without baking banking rules into the underlying code of Colossus’ network.

Several startups have tried to establish KYC-less, crypto-linked cards before. But those relying on networks from payment incumbents have historically struggled to gain long-term traction, including UnCash, which announced its shutdown abruptly last month.

In a since-deleted announcement, UnCash pointed the finger at Mastercard. An abrupt termination by its card issuers amounted to a “clean, corporate guillotine,” the firm said.

UnCash noted that 90% of its cards ran on Mastercard’s network. The firm was reportedly among those leveraging a common “loophole,” issuing thousands of cards for purported employees under a single business identity, per Fintech Business Weekly.

Most crypto-linked cards are established through partnerships with Mastercard or Visa. While Delong is trying to cut that duopoly out of the loop alongside issuers, he still respects firms like Coinbase and Gemini are taking “a relatively easy road” to build momentum quickly.

“What we’re doing is a little bit more quixotic initially, but it has long-term benefits,” he said. “The idea that you have to KYC or AML for a credit card is a little silly, I think.”

Even so, such products are becoming increasingly popular. Crypto-linked cards facilitated $1.5 billion in stablecoin volume last August, doubling from a year prior, according to a report published by crypto analytics firm Artemis earlier this year.

The report found that firms in Latin America, EMEA, and Southeast Asia were pronounced in using crypto-linked cards as a way to “target populations facing acute financial frictions,” including inflationary local currencies and capital controls.

In the U.S., some lawmakers vocalized concerns that the GENIUS Act did not sufficiently address illicit finance concerns before its passage. Delong described Colossus as a company that could make crypto feel a bit more like cash, while also enabling people to fully live on-chain.

Delong’s motivation for building Colossus is also somewhat personal. He cast off bank accounts as a place to store value years ago, but still liquidates stablecoins regularly to cover bills.

“I really want to make an impact,” he said. “I think this is the last rail that will give us full liberty.”

Daily Debrief Newsletter

Start every day with the top news stories right now, plus original features, a podcast, videos and more.
Ex-CFO Gets 2-Year Prison Term

0

Trusted Editorial content, reviewed by leading industry experts and seasoned editors. Ad Disclosure

He told his colleagues only after the money was gone. Nevin Shetty, the former chief financial officer of a Seattle-based tech startup, was sentenced Thursday to two years in federal prison after secretly transferring $35 million in company funds into a cryptocurrency platform he ran on the side — then watching nearly all of it disappear in a matter of months.

A Scheme That Ran In Secret

Shetty made the transfers in 2022 without the knowledge of a single executive or board member at his employer, according to the US Justice Department.

He moved the funds into a platform called HighTower Treasury, which he controlled, and used the money to pour into high-yield DeFi lending protocols promising annual returns of 20% or more.

In the first month, he cleared $133,000. Then the Terra ecosystem collapsed, and the broader crypto market followed it down.

By May 13, 2022, the value of those investments had fallen to nearly zero. With $35 million essentially wiped out, Shetty approached two fellow executives and told them what he had done. He was fired the same day.

The case sat in federal court for years. Shetty was indicted on wire fraud charges in May 2023. A nine-day jury trial followed in November 2025, ending with a guilty verdict on four counts.

At sentencing Thursday, a Seattle judge handed down the two-year prison term. Shetty was also ordered to repay the stolen funds in full and serve three years of supervised release after completing his sentence.

As of today, the market cap of cryptocurrencies stood at $2.3 trillion. Chart: TradingView

How The Market Timing Made It Worse

The timing of the transfers put Shetty at the center of one of crypto’s most chaotic periods. The collapse of TerraUSD and its sister token Luna in May 2022 triggered a broad market selloff that wiped out billions of dollars in value across the industry.

Reports indicate Shetty’s DeFi positions were caught in that wave, with losses accelerating fast enough that the investment value reached near zero before any recovery was possible.

The Justice Department said the disclosure of the transfers came only because of the market downturn — implying that, had conditions held, the scheme might have gone undetected longer.

Where The SBF Appeal Stands

Shetty’s case unfolded in the shadow of a far larger crypto fraud. Former FTX chief executive Sam Bankman-Fried was convicted separately and sentenced to 25 years in prison in 2024.

Bankman-Fried has appealed that ruling. As of Friday, the US Court of Appeals for the Second Circuit had not issued a decision following arguments heard in November, according to reports.

The two cases are unrelated, but both reflect federal prosecutors’ continued push to bring criminal charges over crypto-related financial misconduct.

Shetty’s two-year sentence stands as one of the more recent outcomes in that effort, covering conduct that took place more than three years ago.

Featured image from Aggressive Austin, TX Criminal Defense Attorney, chart from TradingView

Editorial Process for bitcoinist is centered on delivering thoroughly researched, accurate, and unbiased content. We uphold strict sourcing standards, and each page undergoes diligent review by our team of top technology experts and seasoned editors. This process ensures the integrity, relevance, and value of our content for our readers.

Florida moves ahead with state-level stablecoin regulation – DL News

0

  • Florida lawmakers passed a stablecoin bill this week.
  • The legislation will regulate the digital assets at state-level.
  • President Trump this week sided with the crypto industry over crypto legislation.

Florida lawmakers this week pushed forward legislation aimed at regulating stablecoins in the Sunshine State.

Lawmakers passed Senate Bill 314 at a State Senate vote Friday. The bill demands stablecoin issuers in Florida be licensed by the Office of Financial Regulation.

“[The bill] aims to integrate state oversight with federal standards, specifically the federal Genius Act to ensure consumer protection and financial stability,” Republican Senator Colleen Burton said Friday.

DeSantis’ pro-crypto agenda

The bill will now head to Florida Governor Ron DeSantis for signing.

If approved, Florida would become the first state to have its own regulation for managing the tokens.

DeSantis is a pro-crypto politician: the Republican in the past has said he would protect Bitcoin when running for president, and made Florida the first state to ban central bank digital currencies — or CBDCs — after claiming they were “woke” and would “crowd out and eliminate other types of digital assets, like cryptocurrency.”

Wider stablecoin regulation

Stablecoins have been a hot topic since President Trump signed the Genius Act last year to regulate the tokens.

The bill allows banks and other entities to issue stablecoins if they back the tokens with assets like US Treasuries and provide monthly disclosures of their reserves.

Still, banking chiefs and crypto executives are at odds with how to move forward with the regulation of the assets in another piece of legislation: The Clarity Act.

Companies like Coinbase want the legislation to allow firms in the space to pay customers rewards on their stablecoin holdings; banks have said such a practice should be banned or they could lose their deposits as their customers move to crypto.

President Trump this week sided with the digital asset industry, saying that banks shouldn’t be allowed to undermine the government’s pro-crypto agenda.

Mathew Di Salvo is a news correspondent with DL News. Got a tip? Email at mdisalvo@dlnews.com.

The Multibillion-dollar shift turning prediction markets into a professional hedging tool

0

The dominant narrative around prediction markets still centers on elections and sports. Sports account for the majority of volume at major venues, and election contracts are what put the category on the front page. But based on what active traders are actually doing with real money, prediction markets are expanding for an even more impactful purpose: they’re a place to hedge risks that no existing financial instrument can price cleanly because the assets are new in nature. Their applicability spans geopolitical events, policy shifts, combined with commodity-linked outcomes, and this market has the potential to dwarf anything sports will ever produce.

Case in point: when Kevin Warsh was nominated as the next Federal Reserve chair in January, trading activity on Kalshi and Polymarket surged, and among frequent, multi-market traders, the volume spike dwarfed that of the Super Bowl. More recently, the 24-hour window around the Iran conflict produced more trading activity than any single sports day this year. Sports still account for the majority of the overall volume on both venues. But the traders driving the growth edge are building strategies across categories and venues. These traders are increasingly clustering around geopolitical, macro and policy-linked contracts. They are not looking for entertainment. They are looking for tools to price uncertainty that affects their other positions, their businesses, and (in some economies) their household budgets.

Serious institutional voices are now articulating that shift. In a February 2026 paper, Federal Reserve economists evaluated Kalshi’s macroeconomic prediction markets and argued that these markets can provide high-frequency, continuously updated, “distributionally rich” expectations data that could be valuable to researchers and policymakers.

From entertainment to infrastructure

To see where prediction markets are headed, we only need to monitor trader behavior, and the trend shows a growing number of participants integrating prediction market contracts into broader financial strategies.

This means a commodity trader monitoring oil exposure now tracks Russia-Ukraine ceasefire contracts as a live signal for geopolitical risk that directly affects energy prices. An equity trader managing a concentrated tech position watches tariff-related prediction markets to calibrate event risk that no single stock indicator captures cleanly. In both examples, contract prices are doing something no traditional instrument offers. They’re updating in real time as the narrative around a specific event shifts, and this gives traders a probability signal they can act on across their wider book.

The commodities market is a $60 trillion annual market in the United States. The entire category began with farmers hedging crop yields. This simple premise scaled because the underlying need was real. Prediction markets are approaching a similar threshold. The format is simplistic: what we currently have are binary yes/no contracts on time-elapsed events, but the need they address is both universal and largely unserved by existing instruments: they allow you to price and act on uncertainty.

Before prediction markets, there was no clean way to express a view on whether a central bank would hold rates, whether a military strike would occur or whether a trade policy would shift. Traders could try to infer these probabilities from currency pairs or futures, but they were always trading them as a proxy. Even elections, arguably the most closely watched political events, were priced indirectly, so that a clean-energy Democrat leading in the polls would suppress coal stocks. Prediction markets are a superior instrument as they price the event itself. That makes them useful as hedging tools, which is an order of magnitude more applicable.

The international dimension

The fastest-growing segment of prediction market participation is international, spread across Europe, Asia and, increasingly, emerging markets. In economies marked by currency volatility, inflation and policy unpredictability, the ability to price uncertainty is becoming a necessity for investors.

Stablecoins have already demonstrated this principle. Across Latin America and parts of Africa and Southeast Asia, digital dollars have become a mainstream store of value and remittance tool, not because users were drawn to crypto ideology, but because traditional banking infrastructure struggled with costs and volatility. Stablecoin adoption spread because it solved an everyday problem.

Prediction markets extend that applicability by providing a contract on whether a currency will depreciate next quarter, whether fuel subsidies will be cut, or whether a central bank will intervene. When such contracts are accessible through the same EVM infrastructure, a small position on a fuel price outcome starts to look less like a bet and more like insurance that provides a defined cost for a risk that is otherwise unmanageable.

Consumer-grade simplicity is not yet there, but the trajectory is visible, particularly for traders from high-volatility economies who are not treating prediction markets as entertainment. For them, they serve as an information layer that is also actionable.

What comes next

Prediction markets are now posting hundreds of millions in daily trading volume. Polymarket processed $8 billion in January; Kalshi processed $9 billion. Those figures have moved in only one direction.

But the more important evolution will be in format. The current generation of prediction markets operates on simple binary outcomes. As the category matures, expect conviction-weighted instruments, conditional contracts and markets that reference real economic indices, making these tools more useful for hedging and less dependent on novelty for adoption.

Prediction markets are gaining traction because they measure outcomes with direct economic consequences for traders. Weather and commodity-linked markets, inflation and monetary policy contracts, and geopolitical risk pricing all sit at this intersection. Prediction markets are beginning to overlap meaningfully with traditional finance.

Elections have consistently been the category that drives the deepest engagement and the largest volume spikes, and that will continue as the US midterms approach. Sports generate steady liquidity. But the long-term value of prediction markets will grow to serve a larger population of people and institutions that need to manage uncertainty as part of their daily economic lives.

Euro Regulators Question Meta Over AI Glasses Privacy Fears

0

Meta has attracted the attention of the authorities in Europe again — this time over alleged privacy breaches by its AI smart glasses.

European Parliament lawmakers and the United Kingdom’s data regulator, the Information Commissioner’s Office (ICO), raised concerns after reports in the Swedish media suggesting that workers subcontracted by Meta viewed sensitive content recorded by the AI glasses.

The reports first appeared in the Svenska Dagbladet and Göteborgs-Posten newspapers and centered on work carried out by a company called Sama in the Kenyan capital, Nairobi. 

Sama, the U.S. company, has faced criticism before over its labor practices in Africa for allegedly paying substandard wages, subjecting them to inhumane work environments by requiring them to view and then label offensive and violent images.

The Swedish outlets say they spoke to more than 30 Sama employees who reviewed content and annotated data captured by users’ smart glasses to further train the AI and improve the experience.

The nature of the content Sama’s workers say they viewed has sparked alarm, with Svenska Dagbladet reporting that: “Several describe video material showing bathroom visits, sex and other intimate moments.”

The report goes on to quote one worker who claims: “We see everything — from living rooms to naked bodies. Meta has that type of content in its databases. People can record themselves in the wrong way and not even know what they are recording.”

In response to the allegations, Meta told the BBC: “When people share content with Meta AI, like other companies, we sometimes use contractors to review this data to improve people’s experience with the glasses, as stated in our Privacy Policy. The data is first filtered to protect people’s privacy.”

However, the Swedish media reports suggest that this “filtering,” which can include blurring of faces in images, does not always work.

Meta’s U.K. AI terms of service, meanwhile, do state that: “In some cases, Meta will review your interactions with AIs … and this review may be automated or human.” But they do not specify what exactly will be reviewed by humans.

That prompted the U.K.’s ICO to step in. In a statement issued to the BBC, the commission said: “Service providers must clearly explain what data is collected and how it is used. The claims in this article are concerning. We will be writing to Meta to request information on how it is meeting its obligations under the U.K. data protection law.”

In the EU, meanwhile, media outlet Euractiv reported that members of the European Parliament from 17 countries have written to the European Commission demanding to know what action it is prepared to take to ensure Meta is compliant with EU data protection regulations.

Meta’s AI glasses have proven to be a hit since launch, tripling global sales to 7 million in 2025 and prompting rivals to play catch-up.

The company has had a number of other brushes with the authorities in Europe, raising their ire over blocking other companies’ AI chatbots from WhatsApp, being fined for mishandling Facebook data and also for breaching obligations to provide consumers with services that used less of their data.