Home Blog Page 769

Boris Johnson bashes Bitcoin — and gets educated by crypto’s biggest names – DL News

0

  • Boris Johnson described Bitcoin as a “giant Ponzi” in a Daily Mail column.
  • The crypto community was quick to bite back.
  • Crypto critics have long compared digital assets to a Ponzi scheme.

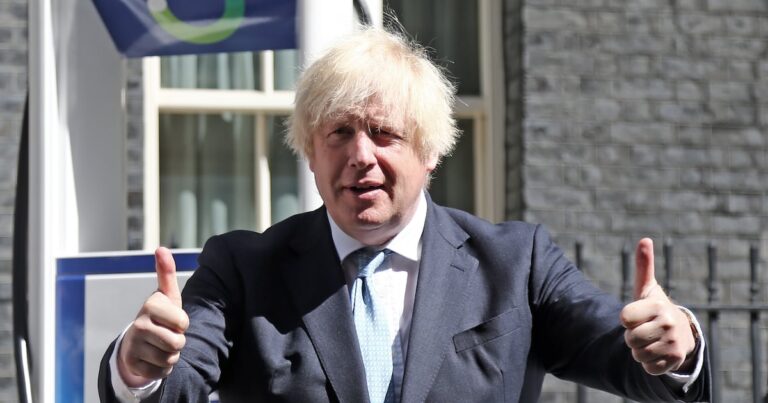
The crypto community bit back at Boris Johnson after the ex-British Prime Minister wrote a column calling Bitcoin a Ponzi scheme.

Strategy co-founder Michael Saylor, Tether CEO Paolo Ardoino, and even legendary Bitcoiner Adam Back all responded to Johnson’s article, “I’ve long suspected Bitcoin is a giant Ponzi scheme and now I’m hearing tales of woe that make me fear I’m right.”

“Bitcoin is not a Ponzi scheme,” wrote Bitcoin treasury pioneer Saylor on X on Friday.

“A Ponzi requires a central operator promising returns and paying early investors with funds from later ones.”

The responses came after Johnson posted his Daily Mail column on X where he warned would-be investors about putting their money in crypto.

The politician isn’t the first high-ranking official to have referred to cryptocurrencies as a Ponzi.

‘But Bitcoin? What is it?’

Johnson, who was UK Prime Minister from 2019-2022, wrote in the Daily Mail that he had met a fellow churchgoer who needed financial help.

After lending the “nice old boy” money, he found out that he had lost cash by buying Bitcoin.

Johnson went on to write that while Bitcoin is decentralised, if people lose faith in the cryptocurrency, it could lose value — and burn investors as a result.

“The more elderly people get ripped off — in the name of Bitcoin — the faster that disillusion will set in,” wrote Johnson.

“I have always suspected from the outset that all cryptocurrencies were basically a Ponzi scheme, with very few good-use cases.”

Oh, Bozza!

The crypto community was quick to try and correct Johnson.

Saylor added that the biggest cryptocurrency had “no guaranteed return — just an open, decentralized monetary network driven by code and market demand.”

And investor and fund manager Fred Kreuger added: “A Ponzi usually needs a central operator, Boris. Bitcoin just has math. Your system has the Bank of England.”

Tether CEO Paolo Ardoino simply highlighted X’s community notes, which gave detailed explanations on why Bitcoin is not a Ponzi.

Blockstream CEO and early Bitcoin developer Adam Back responded to Johnson’s post by using his nickname, “Bozza.”

The Ponzi narrative

Bitcoin has long been described by crypto critics as a Ponzi — a scam where people are rewarded for conning others to pile into a bogus investment with false promises of big returns.

Economist Nouriel Roubini has in the past called crypto a “total real‑bubble Ponzi scheme” that will collapse.

And European Central Bank Executive Board member Fabio Panetta in 2022 referred to the digital asset industry as a Ponzi, likening crypto to a “house of cards” that could collapse.

But those in the crypto world simply point to Bitcoin and other digital assets not having a central authority — as Ponzi schemes typically do — as a rebuttal to the critique.

Mathew Di Salvo is a news correspondent with DL News. Got a tip? Email at mdisalvo@dlnews.com.
AI developers may not be keen on crypto, but stablecoins are the secret to agentic finance, crypto insiders say

0

To get an idea of how big a deal AI-based commerce could be for crypto, ask entrepreneurs and developers involved in digital assets, particularly stablecoins. They’ll happily tell you blockchain-based money is the natural fit, an essential element in the mix and so forth.

Their logic is simple. Over the past few years, stablecoins — mostly digital versions of the dollar on public blockchains like Ethereum — have begun eating into the global payments industry. And while they’ve proven to be faster and cheaper than traditional bank transfers, it’s in the new world of autonomous, micro-transacting AI agents that they will shine.

That, at least, is the view of companies like Circle Internet (CRCL), the creator of the second-largest stablecoin, and technicians at crypto exchange Coinbase (COIN), which has led engineering on x402, a payments protocol designed for use by autonomous AI agents in a field becoming known as agentic finance.

Just as 24/7, frictionless, cross-border payment has been a growth area for stablecoins, agentic commerce has particular requirements that the dollar-pegged tokens meet, according to Dante Disparte, Circle’s chief strategy officer and head of global policy. Those include the ability to program the coins so they transfer only when particular conditions are met and to daisy chain, or compose, a set of actions that occur on receipt of a token.

“Firstly, you have to be able to exploit the otherwise really innocuous features of stablecoins, which is programmability and composability,” Disparate said in an interview. “Number two, where the stablecoin lives, the physical blockchain ledgers themselves, are the common reference point the agents will turn to.”

The crypto industry, however, is viewed with, if not suspicion, then at least circumspection, among some AI developers. For example, Peter Steinberger, the creator of AI agent OpenClaw, is publicly opposed to crypto, so much so that he refuses to engage in any further commentary on the subject and declined to comment for this article.

While crypto’s bullishness on AI is one end of the spectrum, consider the other side, said Sean Neville, co-founder of Catana Labs, a builder of agentic finance infrastructure that last year raised $18 million in seed funding led by a16z.

“I’ve worked with people who are more in the AI developer and engineering community that have a very low opinion of crypto,” said Neville, who is also a co-founder of Circle, in an interview. “I think stablecoins have achieved some escape velocity, but the AI developer community in particular has a negative view of crypto, because of things like memecoins and Ponzi schemes and whatnot.”

Untouched by human hands

A key feature of agentic finance is that it involves micro-transactions, or nano-payments, some of which take place between AI agents with humans somewhere in the background.

This is quite different from using Chat GTP as a front-end for a shopping cart and plugging a credit card into it, though, in the near term, agentic systems will access both crypto and cards, Neville said. Agentic payments are likely to be high-frequency transactions in the fractions-of-a cent range that credit card networks will struggle to handle.

“Over time, I do think that there are significant advantages in stablecoins and blockchain rails that are much more natural fits for agentic flows beyond just the retail commerce use case,” Neville said. “If AI is doing things like leveraging 24/7, programmable rails to stream different kinds of money around the world, across borders, it’s just difficult to do that with anything other than stablecoins.”

With clear regulatory guidance for stablecoins finally coming in the U.S., there are potentially more pressing questions for AI agents around fragmentation and conflicting protocols jockeying for position, Neville said.

“There’s a bunch of different ways for agents to pay each other, but if they can’t all agree on how payments should work, then it’s difficult to bootstrap marketplaces, whether they’re using micro payments or not,” he said. “I would love to see something like an SSL equivalent emerge for agents, and it would be great to see a standard that nobody owns, so that we could all kind of build on the same interoperable standard.”

SSL, or Secure Sockets Layer, is a standard technology that encrypts the connection between a web server and a browser.

Stablecoin-friendly option x402, which is often cited in the debate, has caused some people to get hung up on the protocol’s transaction volume from one month to another, said Erik Reppel, head of engineering for Coinbase Developer Platform and an x402 founder. He said his focus is firmly on looking ahead at a whole category of commerce that will hugely disrupt the internet’s existing advertising marketplace.

“I think the thing people haven’t quite realized is that we’re going to break the fundamental economic model of the internet, moving from browsers and you visiting the website of the person who’s publishing content, to consuming things through your agents and your chat interface,” Reppel said in an interview.

The few cents paid by an agent crawling a website, equivalent to the value of an advert flashed before a human’s eyes, could in theory be accomplished by spinning up lots of virtual cards, if a developer has a relationship with, for example, Visa, Rappel said.

“But anyone can program stablecoins,” he said. “Anyone in the world can spin up as many wallets as they want, and then just use wallets as the way to fully isolate funds for an agent. What we want is agents to have isolated, programmable funds, where your agent can’t spend into your credit card limit and can’t access your credit card.”

Catena’s Neville said the company is grappling with squaring regulated money transmission with a sea of agents and bots that have no financial identity. The goal is to keep the bad bots out, he said, while identifying and allowing the ones you want, while giving them specific guidelines and policies they can’t escape.

“The way to handle that is programmable money, because we can leverage cryptography to ensure verifiability and auditability and so on,” Neville said. “It’s effectively identity and policy controls so agents can operate within the rules, regardless of which protocol or which wallet or account infrastructure they happen to be using.”

Empower Federal Credit Union Expands Partnership with Alkami by Selecting MANTL to Power Omnichannel Growth

0

Alkami Technology, Inc. (Nasdaq: ALKT) (“Alkami”), a digital sales and service platform provider for financial institutions in the U.S., today announced that Empower Federal Credit Union (Empower FCU) has selected MANTL’s Onboarding & Account Opening Solution to modernize its retail and business account opening experience. By expanding its partnership with Alkami, Empower FCU is accelerating member growth and advancing its omnichannel strategy.

Empower FCU leverages the Alkami Digital Banking Platform, and implementing MANTL’s full suite of omnichannel retail and business account opening technology will create a seamless, end-to-end onboarding experience for members and employees from account opening through digital banking. The credit union will enable members and businesses to open accounts online, in-branch, on a mobile application (app), or in the field, supporting Empower FCU’s goal of delivering a consistent, frictionless experience across every channel.

“We selected MANTL because it delivers a modern, seamless account opening experience across both online and in-branch channels,” said Lori Verzillo, senior vice president, chief retail officer, at Empower Federal Credit Union. “Fully integrated with our Alkami Digital Banking Platform, this partnership creates a true omnichannel journey, simplifies onboarding, and accelerates growth—allowing us to support our members and deliver a smooth experience across every channel, meeting them where they are from the start and throughout the relationship.”

This partnership reinforces the credit union’s commitment to delivering fast, intuitive, and flexible experiences that meet members wherever they are. Through MANTL Retail Account Opening, Empower FCU expects to deliver online account opening in less than five minutes and in-branch openings in under 10 minutes, dramatically reducing friction while elevating the member experience. MANTL Business Account Opening will further strengthen the credit union’s ability to attract, serve, and deepen relationships with business members as it expands its business banking offerings. Existing members will also be able to open additional accounts in just a few clicks, helping drive cross-sell opportunities and deepen primary financial relationships.

“Empower Federal Credit Union is taking a thoughtful, member-first approach to omnichannel origination, and Alkami is proud to support that vision,” said Taylor Adkins, vice president of product management at Alkami. “By delivering a unified retail and business account opening experience within the Alkami Digital Banking Platform, Empower FCU is removing friction, strengthening its business banking capabilities, and creating a foundation for long-term member and business growth.”

Bitcoin Treasury Firms on Track to Absorb 10x Daily Mined Bitcoin Supply, Industry Leaders Say

0

Corporate demand for bitcoin is accelerating as publicly traded companies tap stock and preferred-share financing to accumulate supply, a trend some industry leaders say could significantly increase corporate demand for newly mined coins and potentially influence market dynamics. Wall Street Capital Floods Bitcoin as Corporate Treasuries Expand Holdings Corporate treasury demand for bitcoin is increasing […]

Basel Reform May Bring Wave of Fresh Bank Capital to BTC — Analyst

0

The Basel III rules, which govern bank capital requirements, are set to be updated in 2026, and if Bitcoin (BTC) receives a lower risk rating in the revised rules, it could potentially trigger a “huge” influx of liquidity into BTC, according to market analyst Nic Puckrin.

Under the current Basel rules, BTC and similar digital assets are given a 1,250% risk weight, meaning banks must hold reserve assets at a 1:1 ratio to back any Bitcoin held on their balance sheets, Puckrin said.

These restrictive capital requirements make it “almost impossible” for banks to hold BTC or offer BTC-related services, he added. He said:

“The Fed just announced a proposal on how these rules will be implemented in the US, with a 90-day public comment window. If BTC’s treatment improves even slightly, it could open the door for banks to finally integrate BTC into the financial system.” 

Source: Nic Puckrin

In February, several crypto treasury company executives called for reform of the Basel rules to implement more accommodating risk weights for digital assets that would allow banks to participate in the blockchain economy.

Related: Bitcoin advocate group to fight Basel’s ‘toxic’ treatment of cryptocurrency

Basel rules create a different kind of chokepoint

The Basel Committee on Banking Supervision (BCBS) proposed the current capital requirements for cryptocurrencies in 2021, which placed crypto in the highest risk category.

While BTC and crypto carry a 1,250% risk weight under the current rules, investment-grade corporate bonds carry a risk weight of up to 75%, according to Jeff Walton, chief risk officer at Bitcoin treasury company Strive.

Gold, government bonds and physical cash have a 0% risk weight, Walton said, adding that “risk is mispriced.” 

Banks, Basel, Bitcoin Adoption
Risk weights for different asset classes under the Basel III framework. Source: Jeff Walton

The Basel capital requirements are a covert form of choking off the crypto industry, and are more subtle than efforts to debank crypto companies under Operation Chokepoint 2.0, Chris Perkins, president of investment company CoinFund, told Cointelegraph.

“It’s a very nuanced way of suppressing activity by making it so expensive for the bank to do those activities,” Perkins said.

Magazine: Danger signs for Bitcoin as retail abandons it to institutions: Sky Wee