Home Blog Page 427

Canadian, German AI Startups Join Forces to Challenge US AI

0

Canadian AI lab Cohere has acquired German AI company Aleph Alpha, in a bid to meet rising demand for sovereign AI systems.

Financial details of the deal were not disclosed, though the companies said the alliance (which will operate under the Cohere name) will combine Cohere’s AI scale with Aleph Alpha’s “strong research excellence” and network. 

“The initiative reflects a shared vision: to provide the world with an independent, enterprise-grade sovereign alternative in an era of growing AI concentration,” the companies said in a release. 

The development comes as concerns about AI sovereignty are on the rise, with increased scrutiny over the market dominance of both U.S. and Chinese AI giants. 

By joining forces, the partners are targeting customers seeking independence from this concentration of AI technology in the U.S. and China and prioritizing regional control. Engineering talent and computational resources from the two regions will also be pooled under the deal to accelerate the development of next-generation frontier models and systems.

Related:GPT-5.5 Boasts Coding Advancements, But Falls Short of Opus 4.7

“Organizations globally are demanding uncompromising control over their AI stack,” Cohere CEO Aidan Gomez said in a statement. “This transatlantic partnership unlocks the massive scale, robust infrastructure, and world-class R&D talent required to meet that demand.”

“We are building a real counterweight for organizations that refuse to outsource control over their AI to a single provider or jurisdiction,” Ilhan Scheer, co-CEO of Aleph Alpha, said in a statement. “[We are] giving European institutions and enterprises access to powerful, yet controllable AI they can truly own.”

In particular, the new entity is aimed at providing AI systems tailored for highly regulated sectors such as finance, defense, energy, manufacturing, telecommunications and healthcare. 

Backing the initiative financially is Schwarz Group, which plans to lead Cohere’s upcoming Series E round with a $600 million structured financing commitment. 

The investment will also strengthen ties with Schwarz Group’s cloud platform, STACKIT, which is expected to serve as a key infrastructure layer for sovereign AI deployments in Europe.

Founded in 2019, Cohere previously raised $1.6 billion from investors including Nvidia and AMD.

Nakamoto (NAKA) Launches Bitcoin Derivatives Program To Capture Volatility Income And Hedge Downside Risk

0

Nakamoto Inc. has launched an actively managed Bitcoin derivatives program aimed at generating income from market volatility while reducing downside exposure, according to a company statement released Friday.

The program, in operation since the first quarter of 2026, is structured as a complement to Nakamoto’s core strategy of holding Bitcoin as a treasury asset. It uses a portion of the company’s Bitcoin holdings as collateral in a derivatives strategy managed by Bitwise Asset Management through a separately managed account. Custody services are provided by Kraken Institutional.

The initiative centers on two primary components: an income sleeve and a hedging sleeve. The income sleeve involves writing covered calls and call spreads against a defined share of Nakamoto’s Bitcoin holdings. This approach seeks to capture premiums from options markets, where implied volatility in Bitcoin pricing often exceeds realized volatility.

The hedging sleeve focuses on purchasing protective puts and put spreads. These positions are designed to offset potential losses during periods of price decline, providing a buffer against adverse market moves. According to the company, premiums generated from the income sleeve may help fund the cost of these protective positions.

Bitcoin’s volatility as opportunity 

Tyler Evans, chief investment officer of Nakamoto and UTXO Management, said the firm views Bitcoin’s implied volatility as a consistent source of opportunity. He described the program as a structured effort to convert that volatility into shareholder value while maintaining exposure to the underlying asset.

Bitcoin used as collateral within the program remains under Nakamoto’s ownership and continues to be counted toward its reported holdings. The company emphasized that derivatives positions supplement its spot Bitcoin exposure rather than replace it.

Premiums collected through the program may be received in either Bitcoin or U.S. dollars, depending on the structure of each trade. Nakamoto said these proceeds can be allocated toward hedging costs, additional Bitcoin purchases, or general corporate needs in line with its capital allocation strategy.

The program operates under a unified investment mandate that defines limits on notional exposure, eligible instruments, counterparties, and custody requirements. It also accounts for the tradeoff between income generation and potential limits on upside participation due to call option positions.

Nakamoto framed the strategy as part of a broader effort to generate yield from its Bitcoin treasury while maintaining long-term accumulation goals. The company said the hedging component is intended to support balance sheet stability and reduce the risk of forced asset sales during periods of market stress.

Performance details from the program’s first quarter of operation are expected to be disclosed in Nakamoto’s upcoming Form 10-Q filing.

Bitcoin Magazine is published by BTC Inc, a subsidiary of Nakamoto Inc. (NASDAQ: NAKA)

7 Reasons JPX Should Reconsider Its Proposed Digital Asset Exclusion From TOPIX

0

A closer look at why the consultation’s proposed deferral sits awkwardly inside a rules-based benchmark and what a better path forward might look like.

JPX Market Innovation & Research (JPXI) is considering a new rule that would defer companies whose principal asset is cryptoassets from new inclusion in TOPIX and other periodically reviewed indices. The proposal is measured in tone, and the underlying concern, how to treat a newly emerging category of issuer, is a reasonable one for any index provider to think about.

But the specific rule under consultation raises real questions. It would affect companies like Metaplanet, Remixpoint, and ANAP Holdings, along with a growing set of Japanese issuers whose business models are fully legitimate, fully regulated, and fully aligned with long-standing corporate treasury practices.

Here are seven reasons JPXI should reconsider the proposal before February 2026.

1. The Rule Doesn’t Measure What TOPIX Normally Measures

TOPIX is designed to function as a broad, neutral, investable benchmark of the Japanese equity market. Its methodology already contains objective tools for that purpose: liquidity screens, free-float-adjusted market capitalization criteria, continuation buffers, and established treatment for delistings and other listing-quality events.

A crypto-asset screen is a different kind of test. It doesn’t measure liquidity, free float, turnover cost, market capitalization, or listing quality. It looks instead at the composition of a company’s balance sheet.

That’s a meaningful departure from how TOPIX eligibility has historically worked, and it deserves a clearer justification than the consultation currently provides. If a company satisfies TOPIX’s ordinary eligibility requirements, deferring it because of one category of asset introduces a new kind of judgment into a methodology that has been valued precisely for its objectivity.

2. “Principal Asset Is Cryptoassets” Needs a Clearer Definition

The consultation refers to companies whose “principal asset is cryptoassets,” but leaves several administrative questions open:

  • Is the test based on parent-only holdings or consolidated holdings?
  • Would exposure through wholly owned subsidiaries, affiliated companies, or strategic equity stakes be captured?
  • Would indirect exposure through securities, derivatives, or economically similar instruments count?
  • Is the inquiry formal (direct legal title) or substantive (economic exposure)?

These aren’t edge cases. They determine which companies the rule actually applies to. Index methodology gains its credibility from rules that are objective, measurable, and consistently administrable, and a clearer definition would help everyone: issuers, investors, and JPXI itself.

3. The Rule May Be Easier to Work Around Than to Apply

A practical concern follows from the definitional question. If direct Bitcoin holdings by the parent company are disfavored, but equivalent exposure through other structures is not, the rule becomes sensitive to legal form rather than economic substance.

Consider the asymmetry:

  • A direct Bitcoin position would trigger the rule
  • A position in the iShares Bitcoin Trust ETF (IBIT) likely would not
  • A position in a listed Bitcoin miner likely would not
  • A stake in a crypto-linked subsidiary likely would not

The economic exposure in these cases can be very similar. The index treatment would be quite different. That creates an incentive for issuers to restructure toward less transparent forms of exposure rather than disclose direct holdings on the balance sheet. A benchmark rule generally works better when it encourages clear disclosure rather than the opposite.

4. The Carve-Out for Existing Constituents Creates an Internal Tension

The consultation contemplates deferring new inclusion while not applying the rule to existing constituents. This is understandable from a stability standpoint, no one wants unnecessary index churn.

But it also creates an internal tension in the rule’s logic. If Bitcoin treasury exposure were genuinely incompatible with TOPIX, it would be difficult to justify exempting current members. And if it isn’t incompatible, it’s worth asking why new entrants meeting the same investability criteria should be treated differently.

Reconciling that asymmetry would strengthen the proposal considerably.

5. “For the Time Being” Leaves the Timeline Open-Ended

The consultation says the deferral would apply “for the time being,” without specifying a review period, exit standard, or sunset mechanism. In practice, that leaves the timeline open-ended.

The timing matters here. October 2026 will be the first periodic review under the next-generation TOPIX framework in which Standard and Growth market companies can become eligible through the new process. A deferral that coincides with that review, without a defined path back to eligibility, could function as a longer-term exclusion even if it isn’t framed that way.

A clearer review cadence, or an explicit sunset, would make the proposal easier to evaluate on its merits.

6. Global Peers Have Taken More Time on the Same Question

JPXI is not the only index provider thinking about this. MSCI recently considered a threshold-based approach to digital-asset treasury companies and ultimately did not adopt a blanket exclusion, acknowledging the need for further work to distinguish operating companies from non-operating or investment-like entities. FTSE Russell has not announced a comparable rule.

The common thread is that the classification question is genuinely unsettled. Operating companies that hold Bitcoin alongside other business lines: media, energy, retail, mining, infrastructure, don’t fit neatly into existing categories, and the global index community is still working out how to think about them.

Given that, there’s a reasonable case for JPXI to engage further with issuers and market participants before codifying a rule, rather than moving ahead of where the broader conversation has landed.

7. An Asset-Neutral Framework Would Be More Durable

If the underlying concern is that some listed companies have become more concentrated or investment-like, that concern is worth addressing, but it isn’t unique to cryptoassets. Concentrated holdings can take many forms: listed equities, private-company stakes, fund interests, real estate, or other non-operating assets.

A framework that applies consistently across these categories would likely be more durable than a single-asset rule. It would also sidestep the definitional and arbitrage concerns above, since the test would focus on the economic characteristic JPXI actually cares about rather than on one particular asset class.

Several paths could accomplish this:

  • Enhanced disclosure standards for concentrated treasury positions of any kind, giving investors clarity without changing index composition
  • An asset-neutral concentration framework that applies the same test to any non-operating asset held above a defined threshold
  • An optional index variant for investors who want exposure to the Japanese market with cryptoasset-heavy companies excluded, offered alongside, not in place of, the flagship benchmark

Where This Leaves the Proposal

None of this is to say JPXI’s instinct to think carefully about a new category of issuer is wrong. It isn’t. Bitcoin treasury companies are relatively new, and their prominence in Japan has grown quickly enough that questions about how to treat them are worth taking seriously.

But the specific rule on consultation is narrower, vaguer, and more open-ended than the questions it’s trying to answer. A clearer definition, a defined review period, and an asset-neutral framing would go a long way toward addressing the underlying concerns while preserving what has made TOPIX a trusted benchmark: objective, rules-based eligibility that reflects the Japanese equity market as it is.

That combination, substance over form, clarity over ambiguity, neutrality across asset classes, seems like the stronger path forward.

Add Your Signature

Bitcoin For Corporations has organized a coalition letter urging JPXI to withdraw the proposed exclusion and preserve TOPIX as a neutral, rules-based benchmark. The public comment period closes May 7, 2026 and every signature strengthens the case that this issue matters to issuers, investors, and market participants worldwide.

If the arguments above resonate, add your name. Individuals and organizations from any jurisdiction can sign.

→ Sign the coalition letter at topix.bitcoinforcorporations.com

You can also review the full position letter, see who has already signed, and share the campaign with your network from the same page. The deadline is firm, and the window to shape JPXI’s final decision is short.


Disclaimer: This content was prepared on behalf of Bitcoin For Corporations for informational purposes only. It reflects the author’s own analysis and opinion and should not be relied upon as investment advice. Nothing in this article constitutes an offer, invitation, or solicitation to purchase, sell, or subscribe for any security or financial product.
DOJ Drops Criminal Probe Of Fed Chair Powell, Clearing Path For Warsh

0

The Department of Justice ended its criminal investigation into Federal Reserve Chair Jerome Powell on Friday, removing the last major obstacle to Senate confirmation of Kevin Warsh as the central bank’s next leader — a development with consequences for monetary policy and Bitcoin.

U.S. Attorney for the District of Columbia Jeanine Pirro announced the closure of the probe, which had been launched over alleged cost overruns on a $2.5 billion renovation of the Fed’s Washington headquarters. 

Pirro said she was transferring the matter to the Fed’s own inspector general, calling for “a comprehensive report in short order.” She left open the possibility of reopening criminal proceedings if warranted.

The investigation had no legal foundation. A federal judge, James Boasberg, quashed DOJ subpoenas in March after a prosecutor conceded the government had found “essentially zero evidence” of a crime, branding the justification as “thin and unsubstantiated.” Powell himself called the probe a political weapon, stating in January that it was “a consequence of the Federal Reserve setting interest rates based on our best assessment of what will serve the public, rather than following the preferences of the President.”

A ‘bogus’ probe into Powell

Senator Thom Tillis, a North Carolina Republican on the Senate Banking Committee, had vowed to block Warsh’s confirmation until the probe ended, describing it as “bogus.” His opposition, combined with unified Democratic resistance, had stalled the nomination. With the investigation now closed, leadership expects a swift committee vote and floor confirmation before Powell’s term expires on May 15.

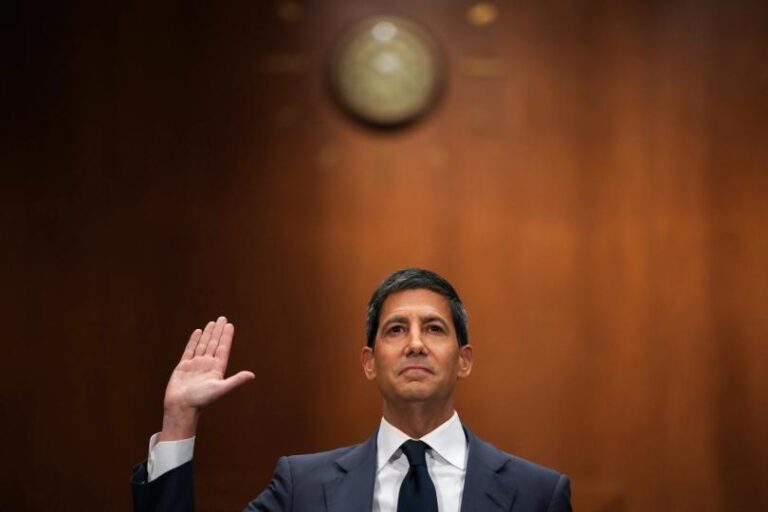
Warsh, 56, a former Fed governor and Stanford professor, testified before the Senate Banking Committee on Tuesday and pledged “strict independence” from the White House on rate decisions. “The president never once asked me to commit to any particular interest rate decision, period,” Warsh said. 

Senator Elizabeth Warren called him a “sock puppet” for Trump, while Republicans praised his qualifications.

For Bitcoin, the stakes are significant. The cryptocurrency has traded in the $70,000–$92,000 range this year as the Fed held rates steady at 3.5%–3.75%, with traders watching every signal from the central bank. 

Lower interest rates historically reduce yields on conventional assets, pushing capital toward risk assets like Bitcoin. When the DOJ first launched its probe in January, Bitcoin climbed toward $92,000 as institutional investors read the attack on the Fed as a threat to dollar credibility and a potential catalyst for rate cuts.

Warsh is considered more hawkish than Powell on inflation, having called the Fed’s post-pandemic rate response “the biggest policy error in 40 or 50 years.” 

Should he take the helm on May 15 and maintain a restrictive stance, Bitcoin bulls betting on rate-cut-driven liquidity expansion may find themselves waiting longer than expected.

Bitmine (BMNR) to buy 10,000 ETH for $23.8M from Ethereum Foundation

0

Bitmine Immersion Technologies (BMNR) said it is purchasing 10,000 ether (ETH) from the Ethereum Foundation, adding to its growing position as the largest digital asset treasury firm after the bitcoin-centric Strategy (MSTR).

The terms of the over-the-counter transaction were finalized on Friday and is worth $23.87 million, the Ethereum Foundation said in an X post.

ETH currently trades at around $2,310, some 3% lower than the sale price in the transfer.

The proceeds will support the organization’s operations, including protocol research, ecosystem development and grants, the foundation said.

The transaction comes as Bitmine continues to accumulate ether at scale while most digital asset treasuries have slowed or halted buying over the past months.

The firm, helmed by Fundstrat CIO Thomas Lee, bought over 100,000 last week, bringing its holdings to 4.97 million ETH, according to its Monday report. Its total assets stood at $12.9 billion, making it the largest public holder of ether, and second-largest public digital asset treasury trailing.

Bitmine is trying to accumulate 5% of ETH’s supply, which would translate to roughly 6 million tokens, the company previously announced.

Read more: Ethereum Foundation stakes another $93 million ether, reaching its 70,000 ETH target

Trump’s DOJ drops probe that stood in way of president’s pick to run Federal Reserve

0

President Donald Trump’s command of U.S. financial and economic policy may have taken a step closer now that his Department of Justice has backed down from an investigation of Federal Reserve Chair Jerome Powell, meaning his nominee to replace Powell may now have an open path to confirmation.

Fed chair nominee Kevin Warsh, whose own considerable wealth includes some crypto-world assets, is awaiting a final vote from the Senate after appearing in a confirmation hearing this week. Trump, who has relentlessly blamed Powell for maintaining overly high U.S. interest rates, chose Warsh to remedy that, but Republican Senator Thom Tillis had promised to block the confirmation as long as the DOJ pressed an investigation against Powell for cost overruns in a Fed building project.

That criminal probe was dropped on Friday, and Attorney General Jeanine Pirro said the DOJ asked the Fed’s inspector general to look into the renovation situation and issue a report. When the news emerged, Kalshi’s prediction betting on Walsh’s confirmation before May 15 shot up from about 30% odds to more than 80%.

“I expect a comprehensive report in short order and am confident the outcome will assist in resolving, once and for all, the questions that led this office to issue subpoenas,” Pirro wrote in a post on social media site X. “Accordingly, I have directed my office to close our investigation as the IG undertakes this inquiry. Note well, however, that I will not hesitate to restart a criminal investigation should the facts warrant doing so.”

Putting his own people atop the Federal Reserve not only equates with Trump’s greater influence over U.S. monetary policy, but it also leaves him with more allies on the Fed board as it makes decisions about financial policy — including implementing rules that govern the crypto industry and stablecoin issuers.

Because of Tillis’ threat, Warsh may have been in a holding pattern as long as the DOJ pursued its investigation, which could have left Powell in charge of the Fed indefinitely, well beyond the May 15 expiration of his term. Now, the Republican-majority Senate may be able to move more quickly toward confirmation of the nominee, who insisted during his hearing that he would act independently of White House direction.

Senator Elizabeth Warren, the ranking Democrat on the Senate Banking Committee that’s considering his nomination, dismissed the move and noted the administration is still pursuing Fed Governor Lisa Cook in court.

“This is just an attempt to clear the path for Senate Republicans to install President Trump’s sock pocket Kevin Warsh as Fed chair,” Warren said in a statement. “Let’s be clear what the Justice Department announced today: They threatened to restart the bogus criminal investigation into Fed Chair Powell at any time while failing to drop their ridiculous criminal probe against Governor Lisa Cook.”

Tillis called Warsh a “great nominee.” In his own posting this week on X, the senator said he’d vote yes on Warsh once the DOJ backs off of Powell:

“I look forward to supporting him out of committee once the DOJ drops their bogus investigation into Chairman Powell that threatens the independence of the Fed.”

Scaling without breaking: Why Execution resilience defines serious brokers

0

A trading platform can look strong on a calm day. Prices move in an orderly way, spreads hold, and orders pass through without friction. Then the market turns. A geopolitical shock hits, gold jumps, oil swings, and a flood of orders hits at once. That’s when the real test begins. In 2026, that test is telling a clearer story about the brokerage market. Growth still matters, but resilience has become the more revealing measure of quality.​

This shift reflects the maturing of the trading ecosystem. Retail participation is strong, competition among brokers is intense, and trading activity around news events and products such as gold, oil, and indices remains high. At the same time, traders have become more informed, more demanding, and more alert to the difference between a smooth platform in quiet conditions and a reliable one in volatile markets.​

Trading in 2026

The backdrop is unusually demanding. Uncertainty continues to drive sharp price moves across major markets, and those moves tend to pull in more retail activity, not less. For many traders, volatility is no longer an occasional disruption. It is part of the daily environment.​

That has changed expectations. Traders who follow macro events, monitor execution quality, and compare trading conditions across multiple firms are less likely to be persuaded by surface-level offers alone. They want strong conditions, but they also want proof that those conditions can hold when markets speed up, and pressure starts to build.​ Once expectations reach that level, volatility becomes the clearest way to judge whether a broker can actually meet them.

The volatility test

This is where weaker infrastructure starts to show. Volatility exposes the parts of a brokerage operation that often stay hidden during quieter sessions, including execution speed, spread stability, liquidity access, and withdrawal handling under heavy demand.​

When systems are not built for stress, the warning signs tend to appear quickly. Orders take longer to fill, slippage increases, spreads become unstable, and liquidity gaps become harder to manage. In some cases, the pressure reaches beyond the trade itself and affects withdrawals during peak activity, which can do lasting damage to trader confidence.​

That’s why volatility works as a stress test for brokers. It reveals whether a firm has built an operation that can cope with real market intensity, or whether it has simply performed well in easier conditions.​ The real issue is not volatility itself, but whether a broker has enough capacity to handle it.

Growth that outruns capacity

This matters because many brokers have spent recent years focused on expansion. Client acquisition has been aggressive across the sector, and in fast-growth markets, scaling can only deliver visible results for a time. The problem arises when commercial growth outpaces operational investment.​

A broker can scale marketing quickly. It can increase visibility, bring in more accounts, and grow volumes in a short period. But if execution architecture, liquidity management, monitoring systems, and server capacity do not expand at the same pace, the strain eventually shows. Usually, it shows during the very moments when traders care most about performance.​

Scaling without strengthening infrastructure has a predictable outcome. Once execution fails under pressure, trust tends to break, and rebuilding it is far harder than winning the first deposit.

A trader who experiences consistent execution during a volatile event, stable spreads, reliable fills, and withdrawals that process without friction stops comparing. That trust accumulates through every high-pressure moment a broker handles well. It cannot be rebuilt easily once it breaks, and it is what separates brokers who build something durable from those who grew fast but built light.

“Volatility does not create structural weakness. It reveals it. The brokers that keep performing under pressure are the ones that treated infrastructure as a strategic investment, not an operational cost. That distinction shows up clearly when markets move fast, in execution consistency, in spread stability, and in whether withdrawals happen on time. In this market, resilience is no longer a support function. It is part of the trading proposition.”

— Milica Nikolic, Exness CY Director

What traders prioritize now

That change in behavior is shaping a more mature market. Experienced traders increasingly look for consistency during high-impact news, stable spreads on instruments such as gold and indices, and withdrawals that remain predictable even when activity surges. These are practical demands, not abstract ones.​

Flexibility during volatility matters too. Conditions that give traders room to manage uncertainty rather than compounding it, have become part of how serious brokers are evaluated. Features like negative balance protections are not footnotes. In fast-moving markets where margin pressure can build quickly, they are part of what makes a platform genuinely usable under stress.

In that sense, the market has become more selective. A broker is no longer judged only by what it offers in a campaign or on a homepage. It is judged by how consistently it performs when timing, pricing, and access all come under strain.​ Meeting those expectations depends less on marketing claims and more on the strength of the systems behind them.

Infrastructure as an edge

This is why infrastructure has become a competitive advantage in its own right. Pricing still matters, but pricing without liquidity depth and execution quality is fragile. A tight spread means less if it disappears the moment volatility rises.​

Infrastructure thinking now sits much closer to the center of broker selection. The ability to maintain consistent conditions during high-impact events, such as precise execution, reduced slippage, and tight and stable spreads in fast-moving instruments like gold, has shifted from a technical consideration to a commercial one. Serious traders have always known this. It’s the problem Exness has built its infrastructure around, because in a market where volatility is the baseline, the brokers that perform when conditions are hardest are the ones that serious traders and partners choose to stay with.

That includes the less visible parts of the business. Monitoring systems, performance telemetry, and the ability to build for stressed conditions rather than calm ones are becoming more important because they shape the end experience in moments that matter most. For serious brokers, these are no longer back-end considerations. They are part of the product itself.​ For traders, that leads to a simple conclusion: the best time to judge a broker is when the market is under pressure.

A different standard

For traders, the takeaway is straightforward: Calm markets can make many brokers look similar; volatile markets tend to separate them. That is why the more useful test is not how a platform behaves on an easy day, but how it performs when the market becomes difficult.​

In 2026, the brokerage industry looks more mature because traders are asking sharper questions and paying closer attention to consistency over time. The firms that stand out are not simply the ones that grew fast. They are the ones that built the capacity to keep performing when volatility turns growth into a test of discipline.​

Jane Street asks court to reject Terraform claims tied to UST-LUNA crash

0

Jane Street asked a U.S. court to dismiss a lawsuit brought by the bankruptcy estate of Terraform Labs, rejecting claims that the trading firm helped trigger the 2022 collapse of the TerraUSD (UST) stablecoin and its sister token Luna.

In two filings submitted Thursday to the Southern District of New York, Jane Street and several employees said the case is an attempt to shift blame for the failure of the Terra ecosystem, which erased roughly $40 billion in value within days.

The firm urged the court to dismiss the complaint with prejudice, which would prevent Terraform from pursuing the same claims again.

“This case is an attempt by the estate of Terraform Labs to extract cash from Jane Street to foot the bill for a fraud that Terraform itself perpetrated on the market,” the defendants wrote.

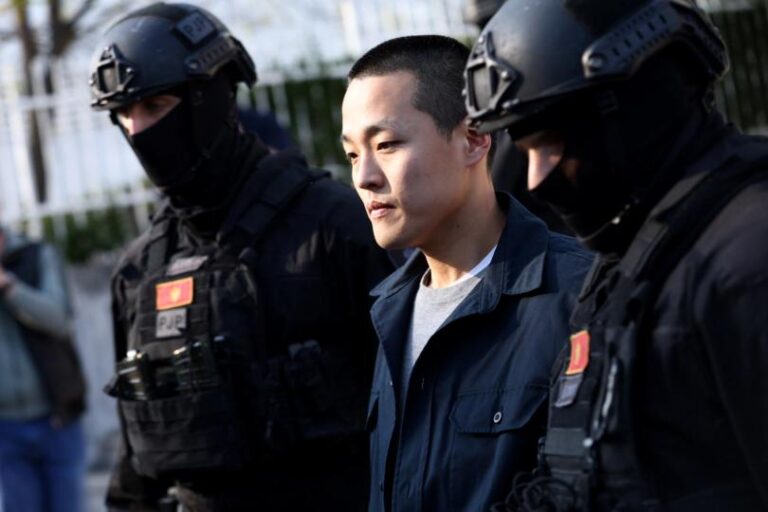
Jane Street argued that the core issues behind Terra’s collapse have already been settled in court. It pointed to criminal and civil cases against Terraform founder Do Kwon, who pleaded guilty to conspiracy and wire fraud and is serving a 15-year prison sentence. A jury also found Kwon and Terraform liable for securities fraud. According to the filing, Kwon said he was “alone responsible for everyone’s pain.”

Terraform’s lawsuit, filed in January by administrator Todd Snyder, accuses Jane Street of insider trading that sped up the collapse. Snyder alleges the firm used nonpublic information from Terraform insiders to trade ahead of major moves, including large withdrawals from the Curve liquidity pool that preceded UST losing its dollar peg.

For example, the complaint claims Terraform withdrew 150 million UST on May 7, 2022, and that a wallet linked to Jane Street pulled 85 million UST minutes later, sparking market panic. Jane Street disputes that narrative and denies any role in the collapse.

Jane Street maintains that “Terraform’s fraud scheme — in which Jane Street had no involvement — has already been prosecuted, adjudicated, and punished.”

Terraform Labs, founded in 2018, filed for bankruptcy in January 2024. Its downfall rippled across the crypto sector, contributing to failures at several firms exposed to the project. The court’s decision on Jane Street’s motion could shape how responsibility for that collapse is assigned.

Researcher wins 1 bitcoin (BTC) for largest quantum attack on elliptic curve yet

0

The quantum attack Bitcoin has spent years treating as tomorrow’s problem just got a little less theoretical.

Quantum security startup Project Eleven said it awarded its 1 bitcoin Q-Day Prize to independent researcher Giancarlo Lelli on Friday after he broke a 15-bit elliptic curve key on publicly accessible quantum hardware, deriving a private encryption key from its public counterpart.

The bounty is worth roughly $78,000 at current prices. It is said to be the largest public demonstration of the attack class that could one day threaten bitcoin, ether (ETH) and most major blockchains.

Elliptic curve cryptography is the math that lets a crypto wallet prove it controls funds without revealing its private key. A public key can be visible to everyone, but deriving the corresponding private key is supposed to be impossible in practical terms.

Quantum computers running Shor’s algorithm, a quantum technique first proposed in 1994, challenge that assumption by attacking the underlying logic that secures those signatures.

Lelli’s result does not mean bitcoin is close to being cracked. Bitcoin uses 256-bit elliptic curve security. A 15-bit key has a search space of 32,767 possibilities, tiny by comparison. The prize was designed to measure whether quantum attacks on real cryptography-based products are moving from white papers into public hardware experiments.

The previous public break was a 6-bit demonstration by Steve Tippeconnic in September 2025 using IBM’s 133-qubit quantum computer. Lelli’s 15-bit result expanded that by a factor of 512 in seven months.

A bit is the smallest unit of information in a regular computer, a qubit is the quantum computing equivalent.

Read more: A simple explainer on what quantum computing actually is, and why it is terrifying for bitcoin

Theoretical resource estimates have dropped even faster. A Google Research paper last month put the cost of a full 256-bit attack below 500,000 physical qubits, down from earlier estimates in the millions.

“The resource requirements for this type of attack keep dropping, and the barrier to running it in practice is dropping with them,” Project Eleven CEO Alex Pruden said.

Pruden noted the winning submission came from an independent researcher working on cloud-accessible hardware, not a national laboratory or a private quantum chip.

The concern is sharpest for wallets whose public keys are already visible on-chain. Project Eleven estimates roughly 6.9 million bitcoin sit in such addresses, about one-third of total supply, including Satoshi Nakamoto’s estimated 1 million bitcoin untouched since the network’s earliest years. Any quantum computer capable of breaking 256-bit ECC could work through those wallets at leisure.

Bitcoin developers have proposed migration paths including BIP-360, a Bitcoin Improvement Proposal that would add quantum-safe address types. Ethereum, Tron, StarkWare, and Ripple have each published post-quantum transition plans.

Fifteen bits is not 256 bits, but is the latest in a rapidly heating up point of interest for bitcoin developers and the broader community.

British Business Bank Commits Record £100m to Apposite Capital’s new Healthtech Fund

0

The British Business Bank has made a £100million cornerstone commitment to Apposite Healthcare Growth I, a new fund aimed at supporting the expansion of UK-based health technology companies. The move represents the Bank’s largest fund commitment to date, as well as its first investment with specialist healthcare and life sciences investor Apposite Capital.

The scale-up capital shortage

Apposite Healthcare Growth I will focus on backing innovative businesses operating across a range of critical sub-sectors, including:

The new fund was launched to directly address the ongoing shortage of scale-up capital available for UK life sciences companies that are approaching a critical growth inflection point. By investing in companies developing market-leading technologies and services designed to improve patient outcomes, the fund aims to help these businesses compete globally and create highly skilled domestic jobs.

Bridging the funding gap

The £100 million anchor investment aligns closely with the British Business Bank’s broader strategy to create deeper pools of scale-up funding. As the largest investor in UK venture and venture growth capital funds, the Bank frequently makes cornerstone commitments to help funds achieve a successful first close, providing them with the necessary scale to execute their investment strategies effectively.

Currently, the British Business Bank intends to deliver a major step change in its support for UK scale-ups, actively targeting over 60 per cent of its venture and growth investment flow toward this crucial business stage. The institution also aims to support the launch of 10 new-to-market growth-stage funds over the next five years by writing larger cheques to leading fund managers.

Expert perspectives
Christine Hockley, managing director and co-head of funds, British Business Bank

Christine Hockley, managing director and head of commercial equity funds at the British Business Bank, highlighted the strategic need for this capital injection.

“The UK needs growth stage funding, and the Bank is stepping up to deliver this,” Hockley stated. “Working with the UK’s venture capital community, we are looking to support the creation of growth stage funds capable of writing significant cheques into the next generation of UK unicorns.”

Hockley added that by writing larger cheques and signaling these commitments to institutional investors, the Bank intends to mobilise the private sector and provide these funds with the firepower they require.

Mark Andrews, investment director of funds and life sciences at the British Business Bank, noted the specific difficulties faced by the life sciences sector.

“The need for scale up funding is especially pronounced in life sciences,” Andrews explained. “However, there remains a shortage of later-stage funds, meaning that many promising life sciences companies cannot fulfil their potential in the UK and may embark on premature or sub-optimal exits.”

Backing the next generation
Sam Gray, managing partner at Apposite Capital

Sam Gray, managing partner at Apposite Capital, views the commitment as a vital catalyst for transformative growth across the sector.

“The UK is home to an extraordinary depth of scientific research, entrepreneurial talent, and innovative companies, yet many businesses face a persistent gap in scale-up funding,” Gray said. “This fund will bridge that gap, enabling high potential companies to accelerate their growth, commercialise transformative technologies, improve health outcomes and support economic growth.”

The move has also garnered strong government support. Peter Kyle, secretary of State for Business and Trade, emphasised that the investment actively delivers on the promise to back the UK’s most ambitious companies.

“This record investment into Apposite Capital delivers on that promise by giving it the financial firepower to support the UK’s most exciting healthcare tech firms scale, develop cutting edge medical products and diagnostics, and improve healthcare right across the country,” Kyle said.