Home Blog Page 396

Visa lanza Visa Agentic Ready, un programa para impulsar el comercio agéntico en América Latina y el Caribe

0

Decenas de emisores en América Latina y el Caribe ya están probando pagos iniciados por agentes de IA de forma segura, a escala y sobre la infraestructura en la que las personas ya confían.

Visa (NYSE: V) anunció hoy el lanzamiento de Visa Agentic Ready en América Latina y el Caribe, un programa global diseñado para ayudar al ecosistema de pagos a prepararse para la próxima era de comercio agéntico. El programa se basa en Visa Intelligent Commerce, el portafolio de iniciativas de Visa que habilita experiencias de comercio seguras, impulsadas por inteligencia artificial a escala.

Visa Agentic Ready es un programa global creado para ayudar a los bancos emisores y socios de pagos a prepararse para el comercio iniciado por agentes de IA. El programa permite a los participantes:

  • Probar pagos iniciados por agentes en entornos controlados y reales, utilizando tarjetas activas y comercios reales.
  • Validar flujos clave de pago, incluyendo la inscripción de tarjetas, la tokenización, la autenticación y la autorización de transacciones.
  • Evaluar mecanismos de confianza, seguridad y control a medida que los agentes de IA actúan en nombre de consumidores y empresas.
  • Identificar brechas operativas y de preparación antes de que las transacciones lideradas por agentes escalen de manera masiva.
  • Colaborar con Visa y comercios seleccionados para comprender cómo se comportan en la práctica las transacciones iniciadas por agentes.
  • Prepararse para un despliegue global a medida que el comercio impulsado por agentes se expande en los distintos mercados.

“A medida que los agentes de IA influyen cada vez más en la forma en que las personas compran, los pagos deben evolucionar al mismo ritmo”, afirmó Catalina Tobar, Líder de Productos de Crecimiento y Alianzas de Visa América Latina y el Caribe. “Visa Agentic Ready ayudará a los emisores de la región a prepararse para pagos iniciados por agentes que sean seguros y escalables, construidos sobre una infraestructura en la que las personas ya confían”.

Diseñado para América Latina y el Caribe, basado en fundamentos existentes

América Latina y el Caribe ofrece un entorno sólido para la prueba y la colaboración, con una alta adopción de tokenización, passkeys y autenticación avanzada, capacidades ya bien establecidas en la red global de Visa. En la región, los tokens de Visa han reducido el fraude en un 70%1 y han incrementado las autorizaciones en un 9%2. Con el 50% del comercio electrónico regional ya tokenizado, Visa trabaja para alcanzar el 100% de adopción y así respaldar una nueva era de comercio seguro impulsado por IA.

Visa Agentic Ready opera sobre la capa de confianza de Visa, que integra tokens, identidad, gestión de riesgos y controles para habilitar pagos iniciados por agentes de forma confiable en múltiples canales y casos de uso. Este trabajo ayuda a los emisores a extender protecciones conocidas a experiencias impulsadas por IA, utilizando tokenización y autenticación biométrica para asegurar que los pagos iniciados por agentes estén claramente vinculados a una persona real, con consentimiento y control en cada momento clave.

De la preparación a la escala real

Llevar el comercio agéntico a escala requiere coordinación en todo el ecosistema de pagos. Visa ya ha incorporado a decenas de clientes al programa y se espera que se sumen más a medida que continúe su expansión.

A través de pruebas controladas en condiciones de operación con comercios seleccionados, los participantes pueden validar cómo funcionan los pagos iniciados por agentes en entornos reales, generando confianza a medida que estas experiencias pasan del concepto a la realidad.

Este trabajo respalda la visión más amplia de Visa sobre un comercio inteligente y programable, en el que credenciales confiables y capacidades de red permiten que los pagos respondan de manera segura y flexible a la intención, el contexto y los controles del consumidor. A medida que una mayor parte del proceso de compra se automatiza, Visa contribuye a que los agentes puedan actuar de forma fluida en representación de las personas, manteniendo siempre a los usuarios firmemente en control.

Entre los primeros socios emisores que están probando con éxito el programa Visa Agentic Ready se encuentran: Banco de Chile, BancoEstado, Banco do Brasil, Banco Industrial, Banco Macro, Banco Popular Dominicano, Banco Santa Cruz, Bancolombia, BBVA, BCP, Bradesco, Consorcio Chile, Banco Galicia, Banco ICBC, Naranja X, Pomelo, Banco Promerica Republica Dominicana, Banco Santander, Scotiabank y XP.

Asimismo, otros socios que están trabajando activamente con Visa para avanzar en sus capacidades hacia la preparación agéntica incluyen: Afirme, Aval, Banco de Bogotá, Banco Popular de Colombia, Davivienda e Interbank.

Visa Agentic Ready replica lanzamientos recientes del programa en Europa y Asia-Pacífico, y se basa en el impulso de Visa Intelligent Commerce con un amplio conjunto de agentes y socios en Norteamérica, para hacer realidad el comercio impulsado por IA para personas y empresas en todo el mundo.

Citas de socios

  • “La participación de Banco do Brasil en la primera transacción agéntica refuerza nuestro compromiso con la innovación responsable y con la evolución del ecosistema de pagos. Estamos siguiendo de cerca las transformaciones impulsadas por la inteligencia artificial y trabajando para garantizar que estas nuevas experiencias se desarrollen con seguridad y confianza para nuestros clientes”. Pedro Bramont, director de Soluciones de Pagos y Servicios de Banco do Brasil
  • “En Banco Industrial, nuestra prioridad es liderar la innovación para ofrecer experiencias digitales que simplifican el proceso de compra y la vida de nuestros clientes. Integrarnos a Visa Agentic Ready nos permite habilitar a los agentes de IA como un aliado estratégico en el día a día de los consumidores, sin comprometer nunca la integridad de sus transacciones”. Juan Bernardo Rivera, gerente general de tarjetas de Banco Industrial
  • “En Grupo Cibest seguimos impulsando la creación de experiencias digitales cada vez más simples, seguras y relevantes en cada interacción de pago. Nos sumamos al programa Visa Agentic Ready, que nos prepara para acompañar una nueva era en la que nuestros tarjetahabientes Visa podrán comprar a través de agentes de inteligencia artificial. Con este paso, confirmamos nuestra visión de ofrecer transacciones más inteligentes y conectadas con las necesidades del futuro”. Liliana Vásquez, vicepresidenta de pagos, flujos y seguros de Grupo Cibest
  • “La evolución hacia el comercio agéntico marca un punto de inflexión en la forma en que las personas interactúan con los pagos. En Banco Macro, participar del programa Visa Agentic Ready refuerza nuestro compromiso con impulsar la innovación de manera responsable, probando nuevas capacidades que combinan inteligencia artificial, seguridad y escalabilidad. Este tipo de iniciativas nos permite prepararnos para el futuro de los pagos digitales, siempre poniendo la confianza y la experiencia del cliente en el centro”. Banco Macro
  • “Desde la perspectiva del Banco Popular Dominicano, Visa Agentic representa una apuesta innovadora que aprovecha el potencial de la inteligencia artificial para redefinir la manera en que nos relacionamos con nuestros clientes. Nos permite ofrecer soluciones personalizadas, seguras y ágiles, optimizando procesos y facilitando pagos, beneficios y el control financiero con mayor eficiencia y conveniencia, lo que refuerza nuestro compromiso con la excelencia, la experiencia de consumo y la evolución digital. Con Visa Agentic, avanzamos hacia una nueva era de compras inteligentes y servicios financieros de vanguardia”. Austria Gómez, vicepresidente de área tarjetas de Banco Popular Dominicano
  • “En Banco Santa Cruz vemos el programa Visa Agentic Ready como un hito en la evolución del comercio digital, donde la inteligencia artificial comienza a integrarse de forma activa en la experiencia de pago. Ser parte de esta fase piloto nos entusiasma y refuerza nuestro compromiso de anticiparnos a las tendencias, fortaleciendo nuestras capacidades para habilitar un ecosistema de pagos más ágil, seguro y centrado en el cliente. Continuamos avanzando con una visión de innovación responsable, convencidos de que esta evolución debe construirse sobre la confianza y la protección de nuestros clientes”. Rafael Jiminian, vicepresidente ejecutivo de negocios de Banco Santa Cruz
  • “En BBVA queremos ayudar a particulares y comercios a avanzar en el nuevo entorno del comercio agéntico con confianza y sin fricciones. A medida que las transacciones se delegan cada vez más en agentes digitales, la confianza, la seguridad y el control del usuario serán fundamentales. Con nuestra participación en el programa Agentic Ready de Visa, reforzamos nuestro compromiso de ofrecer experiencias de pago basadas en inteligencia artificial que sean sencillas, seguras y fiables, al tiempo que ayudamos a los clientes a mantener el control sobre sus decisiones de compra”. Luis Simões, responsable de experiencia y propuesta de valor minorista en BBVA
  • “Bradesco se está preparando para el comercio agéntico, ya que entendemos que será el futuro de las transacciones, con decisiones inteligentes y pagos transparentes”. Guilherme Jorge de Oliveira, gerente de producto del Grupo en Bradesco
  • “Ser pioneros en pagos digitales forma parte del ADN de Galicia. Participar del programa Visa Agentic Ready es una evolución natural de nuestra estrategia: desde la adopción temprana de pagos con QR, pasando por wallets y pagos NFC, hasta la incorporación de nuevos canales y experiencias conversacionales con inteligencia artificial. Este primer paso es fundamental para prepararnos hacia pagos a través de agentes de forma simple y segura”. Lucas Solari, responsable de pagos digitales en Banco Galicia
  • “Ser parte de Visa Agentic Ready representa un paso clave en la estrategia de ICBC de acompañar la evolución tecnológica del ecosistema de pagos de forma segura y a escala. Estamos convencidos de que el desarrollo de experiencias impulsadas por inteligencia artificial requiere estándares sólidos, colaboración con socios estratégicos y un enfoque claro en la protección del cliente. Este programa nos permite avanzar en esa dirección y prepararnos para la próxima generación de transacciones digitales”. Banco ICBC
  • “Validar con éxito el flujo de punta a punta en esta prueba junto a Visa confirma que nuestra infraestructura ya es capaz de soportar la próxima evolución del consumo: los pagos agénticos. En Naranja X no innovamos por la tecnología en sí, sino para eliminar fricciones. Estamos preparando todo el proceso para que el usuario pueda delegar tareas rutinarias en agentes inteligentes con la misma seguridad y confianza con la que hoy usa sus tarjetas como medio de pago. Este avance es un paso concreto hacia esa dirección, donde el tiempo y el alivio financiero de las personas son la verdadera prioridad”. Matías Torre, líder de producto en Naranja X
  • “El comercio agentivo ya es una realidad. Para los emisores en América Latina, la pregunta no es si va a llegar, sino si su infraestructura está lista para acompañar este cambio. En Pomelo, ya contamos con la tecnología para impulsar a quienes quieren liderar esta nueva etapa”. Hernan Corral, Cofundador & CPO, Pomelo
  • “En Banco Promerica, como pioneros en pagos digitales y referentes en innovación financiera, somos parte activa de la evolución del comercio electrónico que está transformando la forma en que las personas compran y pagan. Nuestra participación en el programa Visa Agentic Ready refleja cómo nos anticipamos de manera ágil a estas tendencias y a las nuevas necesidades de nuestros clientes, integrando soluciones basadas en inteligencia artificial que elevan la experiencia de pago. De esta manera, impulsamos transacciones más inteligentes y seguras, alineadas con los altos estándares que distinguen nuestra propuesta de valor”. Carlos Julio Camilo, presidente ejecutivo de Banco Promerica Republica Dominicana
  • “La evolución del comercio impulsado por la inteligencia artificial representa una transformación significativa en la forma en que los consumidores interactúan con los pagos. En Santander, vemos el avance de los agentes como una oportunidad para ofrecer experiencias aún más simples, seguras y personalizadas, manteniendo al cliente en el centro de las decisiones. Participar en Visa Agentic Ready refuerza nuestro compromiso de probar y escalar innovaciones que combinan tecnología, confianza y control, preparando a nuestros clientes para esta nueva etapa del comercio digital”. Gustavo Santos, director de Tarjetas y Banca de Uso Diario en Santander Brasil
  • “En Santander México fuimos los pioneros en realizar con Visa pagos gestionados íntegramente por agentes de IA, validando la seguridad, fluidez y posibilidades de crecimiento de estas operaciones, y por ello seguiremos impulsando las pruebas que nos lleven a la adopción del comercio agéntico”. Laura Cruz, directora general adjunta de estrategia, innovación y experiencia del cliente en Santander México
  • “El pago agéntico marca un punto de inflexión en la evolución de los pagos digitales. En Santander estamos orgullosos de ser pioneros en esta nueva etapa, participando activamente en pruebas globales y locales junto a Visa que permitirán llevar este modelo a escenarios reales de forma segura y escalable. Creemos que la innovación tiene valor cuando mejora la experiencia de las personas, y por eso nuestro foco está en que esta evolución combine simplicidad, confianza y automatización inteligente, siempre con control, seguridad, transparencia y protección para el cliente”. Humberto Panighini, líder de medios de pago en Santander Argentina
  • “En Scotiabank México estamos impulsando activamente la evolución del comercio digital basado en inteligencia artificial, pasando del concepto a la ejecución real dentro de entornos regulados. Ser parte del programa Visa Agentic Ready refleja nuestra ideología de liderar la adopción responsable del comercio agéntico, colaborar con socios estratégicos y preparar al Banco para una nueva generación de transacciones impulsadas por IA, siempre con la seguridad, la confianza y el cliente en el centro”. Luis Alfredo González, SVP & CIO banca internacional en Scotiabank
  • “En Scotiabank, impulsamos la innovación para que nuestros clientes vivan experiencias de pago más simples y seguras. Esto ya no es el futuro del ecommerce, es el presente, donde los agentes de IA facilitan compras personalizadas, siempre bajo el control del usuario. Scotiabank se suma al programa Visa Agentic Ready. Así, reforzamos nuestro compromiso con la confianza, la protección y la adopción de tecnologías que marcan tendencia en la industria”. Carla Temoche Nuñez del Prado, vicepresidenta líder de retail banking, Scotiabank Peru
  • “La evolución de los pagos se apoya en la automatización inteligente, lo que permite recorridos más autónomos, fluidos y seguros para nuestros millones de clientes. Ser parte del programa Visa Agentic Ready representa un paso importante hacia un cambio transformador en la forma en que las personas interactúan con los pagos y sus experiencias de compra. Esta iniciativa demuestra claramente el compromiso de XP con la excelencia en el servicio a sus clientes”. Ciro Moreira, líder de tarjetas de XP Inc.
  • “Agentic es un cambio estructural en la forma en que los clientes descubren, deciden y pagan. Para el Banco de Bogotá, representa una oportunidad tangible de capturar más valor en experiencia del cliente, emisión y aceptación, con capacidades para reducir fricción, fortalecer engagement, optimizar top of wallet e interchange, y habilitar nuevas oportunidades de crecimiento para comercios”. Jose Wolff, vicepresidente de producto y estrategia digital del Banco de Bogotá
  • “En Banco Davivienda, nuestro ADN innovador nos impulsa a anticiparnos a las necesidades de nuestros clientes con experiencias de tecnología de punta. Al ser parte del programa Visa Agentic Ready lideraremos la transición hacia el comercio agéntico en la región, asegurando que la experiencia de nuestros clientes y comercios sea sencilla, confiable y se realicen bajo los más altos estándares de seguridad y eficiencia que siempre nos han caracterizado”. Laura Gómez, vicepresidenta medios de pago Davivienda
  • “En Banco Popular creemos que los agentes de inteligencia artificial son una oportunidad para incrementar la digitalización de nuestros clientes 50+ facilitando la interacción de compras en comercios no presentes de una forma segura. Los agentes funcionan como un asistente personal que ayudará no solo a elegir a los productos, viajes, servicios de acuerdo con los parámetros definidos por el cliente si no que ejecutará el proceso de compra y acompañará cualquier proceso de postventa como devoluciones. La IA integrada con el conocimiento del cliente nos permitirá entregar recomendaciones basadas en sus hábitos y preferencias y generar mayor bienestar y satisfacción de nuestros clientes. Esta colaboración con Visa permite que esto se realice bajo una infraestructura a la vanguardia y con los mayores estándares de seguridad”. Luis Fernando Gomez Falla, vicepresidente banca de personas y experiencia al cliente, Banco Popular Colombia
Celsius Founder Lands $10 Million FTC Settlement—And A Crypto Ban For Life

0

Trusted Editorial content, reviewed by leading industry experts and seasoned editors. Ad Disclosure

Alex Mashinsky, the founder of the crypto lender Celsius, has settled with the US Federal Trade Commission (FTC). The high-profile case stems from allegations that Mashinsky and Celsius violated multiple areas of federal law, including claims tied to securities and commodities rules.

Celsius Founder’s New Limits

Under the terms described in the FTC’s latest filing, Mashinsky has been permanently restrained and placed under an injunction prohibiting him from advertising, marketing, promoting, offering, or distributing any product or service that could be used to deposit, exchange, invest, or withdraw assets. 

The restriction applies whether the activity is carried out directly or through an intermediary. The language is broad, aiming to prevent the Celsius founder from operating or assisting in activities that would connect consumers to financial offerings involving crypto assets.

The settlement also includes a major monetary component. The filing states that the $4.72 billion judgment has been entered in favor of the FTC against Mashinsky as monetary relief. 

It further notes that Mashinsky’s liability is joint and several with any other defendants, to the extent additional liability is ordered later. In addition, Mashinsky is ordered to pay the FTC $10 million. 

While the settlement resolves this portion of the dispute, it does not necessarily cap the FTC’s broader options. The agreement is described as part of the continuing legal fallout tied to Celsius’s 2022 collapse, and it preserves the FTC’s ability to pursue the larger judgment if Mashinsky is found to have misstated or omitted assets in financial disclosures.

From ‘No Risk’ To 12 Years In Prison

The allegations that led to the fallout center on how Celsius users were “duped” into moving their cryptocurrency onto the Celsius platform. 

The regulator says Mashinsky and Celsius represented that deposits were “safer” than keeping funds in a bank or other traditional financial institution, and that customer assets were protected because Celsius allegedly generated profits without exposing consumers to risk. 

The FTC claims those assurances were false, including the assertion that Celsius earned money through secured crypto loans made to other exchanges while presenting the arrangement as carrying no risk to depositors.

The FTC also alleged that the crypto lender falsely advertised that a $750 million insurance policy covered customers’ assets. In addition, it alleges that customers were told they could withdraw their funds at any time, despite how Celsius ultimately functioned during the period leading up to its collapse.

Mashinsky’s legal exposure has also continued to escalate in criminal court. In May 2025, he was sentenced to 12 years in prison after pleading guilty to commodities fraud and securities fraud. 

Celsius
The daily chart shows CEL’s crash over the past year. Source: CELUSDT on TradingView.com

At the time of writing, Celsius’ native token, CEL, was trading at $0.017, marking a nearly 99.80% decline for the cryptocurrency since the network’s fallout in 2022.

Featured image from OpenArt, chart from TradingView.com 

Editorial Process for bitcoinist is centered on delivering thoroughly researched, accurate, and unbiased content. We uphold strict sourcing standards, and each page undergoes diligent review by our team of top technology experts and seasoned editors. This process ensures the integrity, relevance, and value of our content for our readers.

WLFI Token Price Drops 14% After Controversial Token Unlock Proposal Goes to Vote

0

The native token of Trump-family-linked World Liberty Financial dropped nearly 14% on Wednesday as a controversial governance proposal that would place over 62 billion WLFI tokens under new multiyear vesting schedules went to a community vote.

The proposal was first submitted to the World Liberty governance community on April 15 and officially went live for voting on Wednesday. It proposes locking more than 62 billion WLFI tokens held by early investors and insiders for two years before gradually being released over a span of two to three years. 

Voting runs until May 7. At the time of writing, 99.95% of votes are in favor of the proposal, and the quorum requirement of 1 billion WLFI tokens has already been met, with 6 billion tokens in favor and 3.2 million against.

“This is one of the most significant governance proposals in WLFI history,” World Liberty Financial said in an X post on Wednesday, adding: “62,282,252,205 locked WLFI tokens [are] subject to this proposal. None of it touches the market for a minimum of 2 years if passed.”

Despite nearly 100% of voting power being allocated to the “yes” vote, the proposal has been met with strong criticism from some members of the community.

Cointelegraph previously reported that figures such as Moonrock Capital founder Simon Dedic likened the proposal to a rug pull and questioned the two-year unlocks coinciding with the remainder of Donald Trump’s term as US president. Tron founder Justin Sun, who holds a significant amount of WLFI, also labeled the proposal one of the “most absurd” he’s ever seen.

In the replies to World Liberty’s latest X post announcing that the vote had gone live, the majority of comments were critical of the proposal.

Source: World Liberty Financial 

The unlocking schedule for early investors involves a two-year cliff followed by a two-year linear vest, while insiders such as founders, team members and advisers have a two-year cliff and three-year linear vest.

The proposed schedule has faced backlash for its length, while the voting process has also been criticized because those who don’t vote will have their tokens locked up indefinitely.

Related: Visa adds Polygon, Base support as stablecoin settlement run rate hits $7B

The World Liberty Financial team said this structure was designed to give a “more clear, bounded picture of governance preferences” and to keep tokens in the hands of those who are “genuinely committed” to the future of the project.

According to data from CoinGecko, WLFI was priced at $0.06367 at the time of writing, down 13.6% over the past 24 hours. Overall, it is down 72.8% since hitting the open market. 

Cointelegraph has reached out to World Liberty Financial for comment.

Magazine: Will the CLARITY Act be good — or bad — for DeFi?

Cointelegraph is committed to independent, transparent journalism. This news article is produced in accordance with Cointelegraph’s Editorial Policy and aims to provide accurate and timely information. Readers are encouraged to verify information independently.

Crash risk rises as bond yields surge

0

Ouch.

That is how Holger Zschaeptiz, one of the most widely followed macro commentators on X, reacted after the yield on the 30-year U.S. Treasury note (government bond) rose to 5% early today, hitting the highest since July 2025. This level has been tested only twice over the past two decades.

His reaction also sums up the mood of several crypto analysts who see rising yields as a headwind for bitcoin , the world’s biggest cryptocurrency by market value and a macro asset.

“At this point, the dynamic is simple. As long as yields remain attractive and [Fed’s monetary policy] stays tight, capital has a real alternative to risk. This continues to pressure assets like crypto, depending on liquidity and momentum,” Diana Pires, chief business officer at sFOX, said in an email to CoinDesk. sFOX is a San Francisco-based cryptocurrency prime dealer and trading platform designed for institutional investors, hedge funds, and businesses.

Bitcoin is already under pressure alongside an uptick in the Dollar Index (DXY). As of writing, BTC traded at $75,670, down 2% over 24 hours, and the DXY hovered above 99, looking to extend Wednesday’s 0.5% gain.

Here’s why rising bond yields typically hurt BTC and other risk assets. When the U.S. government needs to borrow money, it issues bonds, and the yield on those bonds is the annual return the bond investors earn. So, when yields rise, bonds become more attractive. A 30-year Treasury yielding 5% is an almost risk-free return.

Therefore, every dollar sitting in bitcoin is a dollar not earning that 5% yield. That tradeoff typically leads to capital rotation out of non-yielding risk assets, such as bitcoin and other risky assets like technology stocks. Rising yields also typically weigh on gold, which fell over 1% to a one-month low of $4,540 on Wednesday and last changed hands near $4,564.

“Rising Treasury yields and a stronger dollar [have] historically pressured crypto valuations by tightening financial conditions,” Vikram Subburaj, CEO of India-based FIU-registered Giottus exchange, said.

Note that the 30-year yield is not the only one rising. The 10-year yield, which serves as a benchmark for borrowing costs across the economy, is also elevated. Together, they point to financial tightening, a situation where borrowing gets costly, disincentivizing risk-taking in both financial markets and the economy.

Bond yields are also rising in the U.K. and other parts of the world.

Fed dissenters push back against easing

The central bank left rates unchanged between 3.5% and 3.75%, as expected. What was not expected was the internal dissent. Three out of 12 voting officials pushed back against easing language in the statement, a development that has caught markets off guard.

That’s pushed up expectations for higher-for-longer interest rates, which is showing up in bond yields.

“The Fed’s decision to keep rates steady wasn’t the shocker, but those three dissenters calling for a strike on any easing guidance threw a bucket of ice on the market’s pivot party. It’s a classic hawkish signal, and as Bitcoin is usually an indicator of risk, Bitcoin is feeling it,” Matt Mena, senior crypto research strategist at 21shares, said in an email.

ING characterized the so-called hawkish dissent by three officials as a warning shot aimed at incoming Fed Chair Kevin Warsh, Donald Trump’s pick to replace outgoing Chairman Jerome Powell. “They perhaps want to make it clear that they will not be easily swayed to his way of thinking that rates in time can be lowered,” ING analysts said.

Interestingly, the policy statement released Wednesday contained no clear bias toward easing, reinforcing the message that the Fed is in no hurry to pivot.

Oil rally is lifting inflation expectations

The bond yield surge is not just about the Fed. Early Thursday, oil prices surged to their highest since 2022, with Brent briefly topping $125 per barrel, after Trump mulled extending the blockade of Iranian ports. Moreover, oil prices have been elevated, hovering largely between $80 to $120 since the Iran war began in late February.

As a result, energy prices at gas stations are surging, pushing long-term inflation expectations higher, as CoinDesk noted early this week.

All of that is pushing yields higher.

“Inflation is not convincingly back to target, and the Fed is not signaling a near-term shift. Markets may want clarity on cuts, but the Fed is not giving yet. Until that changes, flows will keep favoring yield and safety over volatility. For crypto, that means the macro backdrop remains a headwind, not a tailwind,” Pires said.

Tamara Taps Lean Technologies’ Open Banking to Boost Credit Approvals by 32%

0


Lending Middle East & Africa


Tamara, the largest buy now, pay later (BNPL) provider in the Kingdom of Saudi Arabia (KSA), has partnered with Lean Technologies to significantly expand access to credit for consumers who fall outside traditional financial scoring models.

According to a newly published case study detailing the results of the multi-year partnership, the collaboration leverages Lean’s Open Banking data to provide Tamara with enhanced visibility into real income and cash flow.

Serving the underserved

Historically, legacy credit models have struggled to accurately assess the financial health of non-traditional workers. By utilizing Open Banking insights, Tamara is now able to reliably serve customers who are typically much harder to evaluate, including:

The integration of real-time financial data has translated into substantial growth for the BNPL provider’s lending capabilities. The partnership has resulted in a 32 per cent overall increase in approval rates. Furthermore, Tamara has seen a massive 60 per cent uplift in credit eligibility specifically for its non-salaried customers.

A broader market shift

According to Lean Technologies, these results point to a much broader shift currently taking place within the regional market. As alternative data becomes more accessible and reliable, access to credit is steadily beginning to expand beyond the restrictive confines of traditional credit models.

Lean Technologies currently operates across the region to facilitate these data connections. The firm is regulated in the UAE by the ADGM Financial Services Regulatory Authority to provide Third Party Services, and is permitted by the Saudi Central Bank to test its innovative services under the local Regulatory Sandbox environment.


Bitcoin Long-to-Short Ratio Shows Pro Traders Cautious Over Fed, Inflation

0

Key takeaways:

  • Negative Bitcoin funding rates indicate bearishness, yet whales maintain steady long-to-short ratios at major exchanges.
  • Inflation concerns and tech corporate earnings remain the biggest drivers for Bitcoin traders’ sentiment.

Bitcoin (BTC) faced rejection at $77,800 on Wednesday, then retested the $76,000 level. This movement followed a correction in the S&P 500 Index as the war in Iran reached its 60-day mark, driving crude oil prices toward $118. While demand for leveraged bearish Bitcoin futures positions increased, the long-to-short ratio of whales at major exchanges indicates a different trend.

S&P 500 Index futures (left) vs. Bitcoin/USD (right). Source: TradingView

Bitcoin’s lack of bullish momentum above $78,000 mirrors the S&P 500 Index’s struggle near 7,200. Trader skepticism stems in part from the inflationary impact of high energy prices, which diminishes consumer spending and corporate earnings through higher logistics costs. Additionally, investors are questioning the profitability of technology companies’ investments in AI, according to Yahoo Finance.

Bitcoin futures show bulls lacking confidence

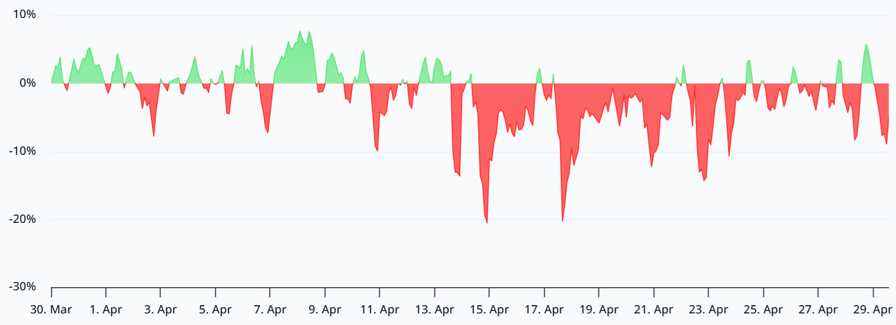
Setting aside the specific reasons for investor caution, the Bitcoin perpetual futures funding rate turned negative on Wednesday. This followed a brief neutral-to-bullish period on Tuesday. In a healthy market, this rate usually stays between 6% and 12% to cover capital costs, which means buyers typically pay a fee to maintain their positions. A negative rate suggests a shift toward sellers.

Bitcoin perpetual futures annualized funding rate. Source: Laevitas

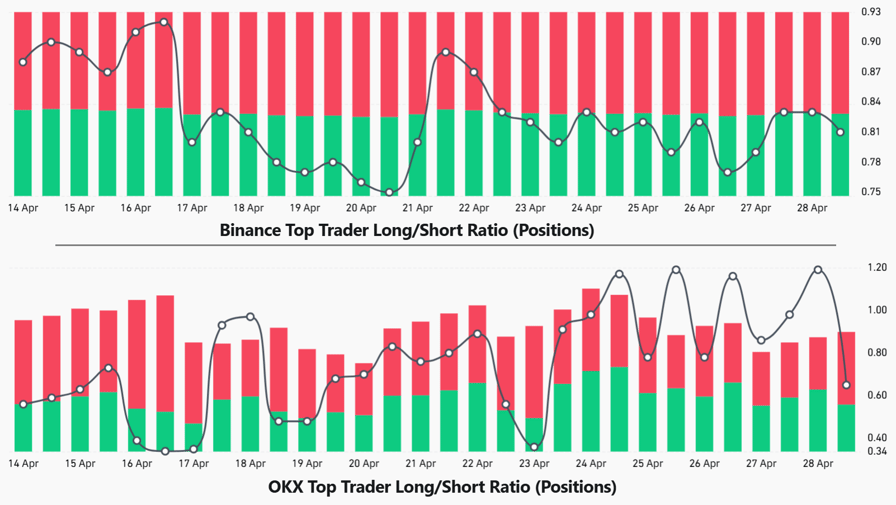
The Bitcoin perpetual futures funding rate has remained mostly negative over the past two weeks, indicating increased demand for leveraged short positions. While this data initially suggests a lack of confidence among buyers, a closer examination of whale positioning is necessary. The top traders’ long-to-short ratio across exchanges includes spot, margin, and futures data, offering a more comprehensive perspective.

Top traders’ long-to-short ratio and Binance and OKX. Source: Coinglass

The long-to-short ratio for professional traders on Binance was 0.80, showing a minor improvement from the 0.75 level recorded on Tuesday, though it remains slightly bearish. At OKX, top traders have briefly signaled bullish sentiment several times since Friday, but these shifts have been temporary. Nevertheless, there is no evidence that whales are turning increasingly bearish, as the long-to-short ratio has held steady throughout the past week.

The latest US Federal Reserve statement after Wednesday’s meeting observed that “inflation is elevated, in part reflecting the recent increase in global energy prices.” The FOMC chose to keep interest rates at their late 2025 levels, even though four members supported a 0.25% cut. According to CNBC, this marks the first time four FOMC members have dissented since October 1992.

Related: Bitcoin’s recent rally is largely fueled by Strategy purchases: Bitwise’s Hougan

Bitcoin bulls’ lack of conviction should not be mistaken for bearishness, particularly as Strategy (MSTR US) continues its accumulation. Over the last four weeks, Strategy acquired 56,235 BTC, a move supported by the issuance of its perpetual preferred security, STRC. The company currently holds 818,334 BTC, exceeding the position of BlackRock’s IBIT exchange-traded fund (ETF).

Professional traders remained unmoved by Bitcoin’s decline to $75,000 on Wednesday, as indicated by exchange long-to-short ratios. However, the persistent negative funding rate in Bitcoin futures suggests that sentiment remains cautious. Macroeconomic and tech corporate earnings remain the biggest driver for Bitcoin traders’ sentiment.

This article is produced in accordance with Cointelegraph’s Editorial Policy and is intended for informational purposes only. It does not constitute investment advice or recommendations. All investments and trades carry risk; readers are encouraged to conduct independent research.

Cyber risk tops the global people risk agenda, according to Marsh’s 2026 People Risks report

0

Organizations and their people are operating under sustained uncertainty because of rising cyber threats, rapid adoption of artificial intelligence (AI), and skilled labor shortages, according to the 2026 People Risks report released today by Marsh (NYSE: MRSH), a global leader in risk, reinsurance and capital, people and investments, and management consulting.

In 2026, resilience depends on how well organizations invest in their people: building the right skills, supporting health and financial security, and redesigning work so humans and technology can perform at their best together.Share

Drawing on insights from more than 4,500 HR and Risk professionals across 26 markets, the report highlights that technology disruption is driving the top people risks, the workforce-related factors that can amplify or mitigate enterprise risk and impact organizational resilience and performance.

Companies that actively manage these risks are better positioned to gain a competitive edge. When asked about the positive outcomes organizations realized by successfully managing and mitigating people risks, 40% of respondents said they increased workforce productivity and efficiency, and 36% said they achieved faster progress on strategic initiatives such as AI adoption.

“People risks cannot be secondary concerns, as they impact the health and well-being of the workforce and the business,” said Hervé Balzano, Mercer’s President of Health and Benefits and Mercer Marsh Benefits’ Global Leader. “In 2026, resilience depends on how well organizations invest in their people: building the right skills, supporting health and financial security, and redesigning work so humans and technology can perform at their best together.”

Technological change and disruption are top of mind

Inadequate cyber threat literacy ranks as the number one people risk globally, underscoring that cyber resilience depends as much on human behavior as it does on technology. Technology skills shortages, such as those in cyber and AI, follow closely at number three, reflecting a growing gap between digital ambition and workforce readiness.

While organizations continue to invest heavily in AI, the most significant threat may be translating that spending into real productivity, innovation and performance gains. Mindset barriers to AI adoption now rank among the top global people risks. Forty percent of HR and Risk professionals are concerned that their organizations are investing in and adopting AI without adequate training and upskilling.

“AI will only deliver value when organizations rethink how work is done and how people are supported,” commented Ravin Jesuthasan, Mercer’s Global Leader for Transformation Services. “Treating AI as a simple add-on to existing work processes creates real risk and inefficiency. The organizations pulling ahead are those redesigning work, upskilling their workforce, addressing AI anxiety and pairing human judgment with machine capability.”

Leadership gaps and labor shortages amplify risk

Labor shortages, particularly in digitally-savvy talent, remain one of the most persistent global threats, ranking second overall and topping the list in industries such as manufacturing, energy, retail and construction. The pressure is particularly acute in aging and super-aging societies, where shrinking working-age populations are colliding with a rising demand for specific skills.

At the same time, the report identifies inadequate leadership skills as the single biggest risk multiplier, triggering or worsening issues like mental health deterioration and unsafe working conditions, which put productivity, performance, and reputation at risk.

Traditional leadership models are proving ill-suited for today’s volatile environment. Mercer’s recent 2026 Global Talent Trends report confirms that executives’ and employees’ views on effective leadership are evolving; employees place increasing value on empathy, communication, and honesty while executives emphasize risk awareness, strategic execution, and accountability in leaders. This misalignment on what constitutes good leadership threatens to erode cultures, employees’ sense of satisfaction, and organizational performance.

Financial stress and health risks undermine performance

Financial insecurity is now a material organizational risk, ranking fourth globally. According to respondents, employees’ rising living costs and debt burdens are directly linked to lower employer retention and engagement, as well as potential misconduct in organizations.

Financial strain also extends to employee health and well-being. Employees continue to delay care due to affordability and access issues, quietly eroding workforce resilience. HR and Risk professionals expect the situation to worsen, with more than half (58%) saying health and benefits costs are almost certain or likely to increase.

“Despite concerns about rising benefit costs and growing mental health challenges, HR and Risk professionals are deprioritizing health-related risks as they are overshadowed by more immediate concerns,” shared Amy Laverock, Mercer Marsh Benefits’ Global Advisory Specialties Leader. “This highlights a concerning disconnect. Organizations are attempting to separate health outcomes from risk management, when they are inherently intertwined.”

Risk maturity delivers a measurable advantage

Organizations that report more advanced approaches to managing risk also consistently report having more effective people risk mitigations in place. Additionally the report shows, companies with strong collaboration between the Risk and HR functions have significantly more effective risk mitigations in place today — translating into stronger decision-making and greater stability.

“Forward-looking organizations recognize that their workforce is not just a source of risk, but their greatest strategic asset,” Ms. Laverock added. “Those that act now — investing in leadership and technology skills, as well as employee health and financial security — will be best equipped to turn uncertainty into advantage.”

the hidden driver of token performance

0

Welcome to our institutional newsletter, Crypto Long & Short. This week:

  • Jordan Brewer on the missing piece in token markets: institutional-grade investor relations.
  • Martin Burgherr on crypto markets maturing, becoming more efficient and lower risk for institutions.
  • Top headlines institutions should pay attention to by Francisco Rodrigues.
  • Collector Crypt: revenue recovery meets token re-rating in Chart of the Week.

-Alexandra Levis


Expert Insights

Guide, deliver, repeat: the hidden driver of token performance

By Jordan Brewer, investment analyst, Runa Digital Assets

In early March, just three months after a Solana Breakpoint mainstage appearance by Ranger Finance co-founder Fathur Rahman, and two months post-ICO, tokenholders forced the liquidation of the protocol’s treasury. How does a 14x oversubscribed ICO unravel so quickly? The answer: poor investor relations.

Institutional-grade investor relations remains the missing piece in token markets. Crypto has spent years in a venture-style framework, but protocols now seek public market investors to provide more durable capital. A key part of investor relations is a regular investor call where management walks through forward guidance — teams at Maple Finance and EtherFi are leading here. These calls are solid, but this is just the start, and the stakes are high. Done well, token valuations are rewarded; done poorly, the downside is steep.

It pays to give guidance (as long as you beat it)

Research shows the value of forward guidance isn’t just in providing it, it’s in its accuracy. Bartov, Givoly, and Hayn (2002) found that firms that consistently meet or beat their own guidance enjoy a measurable stock price premium over firms that don’t. This premium compounds for “habitual beaters,” meaning the market increasingly trusts and rewards management teams that repeatedly deliver. Additionally, beating guidance is a leading indicator of future stock performance, regardless of whether the beat was genuine or a result of earnings or expectations management. Skinner and Sloan (2002) also demonstrated the inverse: growth stocks that disappoint on earnings expectations experience an asymmetrically large negative price response, far exceeding the upside reward of a positive surprise. Guidance accuracy is a proxy for management credibility, and credibility is a direct input to valuation multiples.

Crypto is beginning to produce its own version of this dynamic. In December 2024, when Maple’s AUM was $460 million and their ARR was $4 million, Maple set guidance of $4 billion in AUM and $25 million in ARR for 2025 and later raised guidance to $5 billion in AUM and $30 million in ARR. Maple delivered, hitting $5 billion in AUM and $28 million in 30 day annualized revenue in October (see table below). That’s a guide-and-deliver cadence that any public market investor would recognize and reward. From December 2024 to June 2025, the SYRUP token price rose from $0.10 to a high of $0.60, outperforming competitors like AAVE by 475%.

Chart: Maple Finance

EtherFi is a good example of this dynamic. On their March 2026 tokenholder call, the team projected a 55% reduction in customer acquisition cost while raising their advertising budget 420% throughout 2026, which would imply 11x year over year customer growth. That’s the kind of specific guidance that gives investors something concrete to hold them to.

However, guidance without delivery is just marketing. Investor relations in crypto doesn’t end with a dashboard, that’s where it starts. Guidance and accountability are at the heart of credibility for protocol teams, and it is credibility that builds conviction in public investors.


Principled Perspectives

Institutions are separating custody from execution in crypto

By Martin Burgherr, chief clients officer, Sygnum Bank

There is a quiet but significant shift underway in how institutional capital moves through crypto markets. Major trading firms are increasingly separating where they hold assets from where they execute trades. More than a tactical change, it signals a broader evolution in digital asset market structure.

For most of crypto’s institutional history, there has been a basic architectural assumption: to access liquidity, you keep capital on the exchange. Historically, if you want to trade on an on-chain options exchange or run strategies across multiple venues, you wire the collateral to each exchange and leave it there. The model works, until you ask what it costs.

That cost is not just counterparty risk, though that matters too. It is capital inefficiency. Every dollar posted as margin on an exchange sits idle, earns nothing and cannot be redeployed. For an institutional trading desk managing hundreds of millions in positions, the opportunity cost is enormous — and in a rising-rate environment, it is getting harder to justify.

The infrastructure is catching up

The separation of custody and execution is not theoretical. Firms including Wintermute and Nomura’s digital asset arm Laser Digital are already operating this way, using collateral held in regulated bank custody while maintaining full access to exchange liquidity. BlackRock’s BUIDL tokenized money market fund, which sits at roughly $2.5 billion AUM, is now accepted as off-exchange collateral. The infrastructure is not being built by startups. It is being built by the institutions that intend to use it.

Chart: BlackRock USD

When collateral moves into regulated custody, it can take a different form. U.S. Treasuries or tokenized money market fund shares can serve as trading collateral while earning yield. The collateral does not just sit in a vault — it remains productive while still backing trading activity. Capital that previously sat inert can now generate returns, reducing the effective cost of maintaining trading positions. This is not a marginal efficiency gain. It fundamentally changes the economics of running an institutional crypto trading operation.

A maturing market structure

Crypto is beginning to follow a familiar pattern. Traditional finance solved this problem long ago — equities trade on exchanges, assets settle through custodians. The two functions live in different places, governed by different entities. That separation is what makes institutional participation possible at scale.

According to EY-Parthenon’s 2026 institutional investor survey, 73% of institutional investors plan to increase their digital asset allocations this year, with respondents getting more selective about counterparty risk. The infrastructure is scaling to meet them. The migration is already underway.


Headlines of the Week

By Francisco Rodrigues

This week’s headlines highlight that while the bridges between traditional finance and the crypto sector keep on growing, the devastation caused by smart contract exploits is hitting the market.

  • U.S. military runs a Bitcoin node, sees crypto as ‘power projection’ vs China: Admiral Samuel Paparo, head of U.S. Indo-Pacific Command, told Congress that INDOPACOM is operating a live node on the Bitcoin network for cybersecurity testing and views the protocol as a tool of American power projection against China.
  • Aave raises nearly 80% of the $200 million it needs to cover bad debt left by Kelp DAO exploit: The DeFi United recovery initiative has gathered roughly $160 million of the $200 million needed to recapitalize rsETH and erase the bad debt, with Mantle and the Aave DAO supplying 55,000 ETH, around $127 million, of the total.
  • More than 100 crypto firms urge Senate to move on U.S. market structure bill: A coalition including Coinbase, Ripple, Kraken, Andreessen Horowitz and Paradigm wrote to the Senate Banking Committee pressing for a markup of the Clarity Act, warning that without a federal crypto framework, investment and jobs will move offshore to jurisdictions like the EU that already have one.
  • JPMorgan says persistent security flaws curb DeFi’s institutional appeal: Wall Street’s largest bank told clients that repeated bridge and infrastructure exploits, headlined by the KelpDAO attack that wiped roughly $20 billion in TVL within days, and flat ETH-denominated growth are pushing capital toward Tether’s USDT and keeping institutions on the sidelines.
  • EU’s largest measures against Russia yet include escalation of crypto sanctions evasion: Brussels’ 20th sanctions package imposes a sectoral ban on all Russia-based crypto service providers and DeFi platforms, prohibits transactions in the digital ruble and the RUBx stablecoin, and designates the Kyrgyz exchange TengriCoin, the first time a third-country VASP has been hit for facilitating the Garantex–Grinex–A7A5 evasion network.

Chart of the Week

Collector Crypt: revenue recovery meets token re-rating

After peaking in September 2025, Collector Crypt’s weekly revenue pulled back sharply before grinding back to ~$1 million/week since March — with the CEO’s revenue-funded buyback programme providing a mechanical bid under CARDS throughout the recovery. The recent price spike was then turbo-charged by a community update on April 24 claiming $146.9 million Q1 revenue and $8.6 million profit, though the token remains 73% below its all-time high.

Chart: Collector Crypto

Listen. Read. Watch. Engage.

  • Listen: Did you hear? Consensus Miami is heating up. Recently added speakers include: U.S. Senator Kirsten Gillibrand, U.S. Senator Ashley Moody, and Donald Trump Jr., Co-Founder, World Liberty Financial. Grab 20% off your ticket today!
  • Read: In Crypto for Advisors, Vincent Chok from First Digital unpacks the rise of “agentic finance,” where #AI agents are moving beyond advice to execute financial transactions.
  • Watch: CoinDesk’s Public Keys from NYSE with host Jennifer Sanasie. Brett W. Redfearn, President of Securitize, joins to discuss the $30 billion in tokenized assets on chain, Michael Reinking from NYSE gives a digital assets macro outlook, and AVAX One CEO Jolie Kahn explains a treasury strategy around Avalanche.
  • Engage: David LaValle will be speaking at June’s ICI Conference in Nashville. Let’s connect onsite! 

Looking for more? Receive the latest crypto news from coindesk.com and market updates from coindesk.com/institutions.


Note: The views expressed in this column are those of the author and do not necessarily reflect those of CoinDesk, Inc., CoinDesk Indices or its owners and affiliates.

MoonPay Folds Sodot Into New Institutional Platform

0

Former acting CFTC Chairman Caroline Pham will run the new business, which bundles key management, custody, execution, and white-label stablecoin issuance into a single stack.

MoonPay on Wednesday said it has acquired Israeli key management infrastructure firm Sodot and launched MoonPay Institutional, a new business targeting financial institutions, asset managers, trading firms, and exchanges moving into digital assets.

The unit will be led by Caroline D. Pham, the former acting Chairman of the U.S. Commodity Futures Trading Commission, who joined MoonPay as CEO of Moon Global Markets and also serves as the company’s Chief Legal Officer and Chief Administrative Officer.

Sodot, founded in 2023 by Ido Sofer, Shalev Keren, Matan Hamilis, and Elichai Turkel, builds self-hosted multi-party computation (MPC) and trusted execution environment (TEE) products for managing private keys and API credentials. The company says its platform has secured more than $50 billion in transactions and protected over 10 million wallets.

The full Sodot team, technology, and customer base are moving over, and MoonPay said it intends to expand the company’s Israeli operations.

Institutional Stack

MoonPay Institutional combines wallet infrastructure and key management built on Sodot’s MPC and TEE stack, custody through MoonPay Trust Company (a New York Limited Purpose Trust Company regulated by the NYDFS), a Crypto API Vault for managing exchange and venue credentials, on-chain trade execution and cross-chain collateral mobility, and aggregated OTC and DeFi liquidity across Ethereum, Solana, Base, Arbitrum, BSC, Hyperliquid, Uniswap, and what MoonPay describes as more than 200 additional networks and protocols.

The stablecoin and payments layer offers white-label issuance, reserve management, and cross-border settlement in over 120 fiat currencies, with existing integrations spanning PayPal, Paysafe, and Deel. MoonPay’s payments network reaches over 7,500 merchants, wallets, and apps and an estimated 100 million users, building on a string of recent moves, including its acquisition of stablecoin infrastructure firm Iron in March 2025, the USDT Mastercard launch with Tether, and the PYUSDx app-specific stablecoin platform with M0.

“We built MoonPay to be the world’s leading crypto payments network. Our institutional arm is the next stage, and together with Sodot’s infrastructure, it will allow us to bring this platform to financial services firms now entering the digital asset space,” said CEO and founder Ivan Soto-Wright in a press release.

Demand for Infrastructure

MoonPay framed the launch against a sharp pickup in institutional demand for digital asset infrastructure.

Citing Federal Reserve research, the company said stablecoin transaction volume reached $33 trillion in 2025, with Q1 2026 alone topping $28 trillion, and total stablecoin market capitalization has crossed $317 billion, up more than 50% since early 2025.

It also pointed to Nomura Securities data showing that more than two-thirds of institutional investors now want exposure to DeFi yields, and to a Goldman Sachs survey indicating that 71% of institutional asset managers plan to increase digital asset exposure over the next 12 months.

This article was written with the assistance of AI workflows. All our stories are curated, edited and fact-checked by a human.

Hyperliquid’s HYPE token could be its prediction market weapon, Arthur Hayes says

0

Leading decentralized exchange Hyperliquid’s push into prediction markets is about who captures the upside, not just cheaper trading, according to Arthur Hayes, co-founder of BitMEX exchange and CIO of Maelstrom fund.

CoinDesk reported earlier that Hyperliquid is preparing a zero-fee-to-open model for event trading under HIP-4. The Hyperliquid Improvement Proposal (HIP)-4 is a proposal that introduces event trading on Hyperliquid.

Hayes said that structure is only the first layer. In a note to CoinDesk, he argued that the real differentiator is HYPE, Hyperliquid’s exchange token, which he said allows users to benefit from platform activity in a way Polymarket and Kalshi currently do not.

“HIP-4 will quickly become a dominate prediction market because of Hyperliquid’s large user base, much cheaper trading fees, and very robust tech infrastructure,” Hayes told CoinDesk. “Users who own the $HYPE token can directly profit from their usage of HIP-4.”

Polymarket is expected to launch a token, often referred to as $POLY.

On Gate, premarket perpetual contracts tied to a potential $POLY token are trading around $14, implying a fully-diluted valuation of roughly $14 billion. HYPE, by comparison, has an FDV of about $38 billion, according to CoinGecko data.

Pre-listing markets are often highly speculative and can be thinly traded, meaning any implied valuation should be treated with caution and may not reliably reflect actual market demand.

The argument also comes down to geography. Polymarket registered with the CFTC last July and is rebuilding its U.S. business, putting compliance at the center of its strategy.

However, in Asia, it is still grappling with how regulators classify its product. It is geoblocked in Singapore, Thailand, and Taiwan, partially restricted in Japan. Meanwhile, in Hong Kong, prediction markets more broadly are on the radar of gambling regulators

Hyperliquid faces no equivalent constraint, and its user base skews toward Asia, where crypto-native trading is already deep.

The contrast is clearest with Kalshi.

As a CFTC-regulated exchange, Kalshi’s model is built around compliance and licensing, not token incentives, which likely rules out the kind of value-accrual layer Hayes is pointing to.

That makes it the most direct test of his thesis. Users can trade event outcomes on Kalshi, but they have no path to the upside of the platform itself. In traditional markets, that kind of upside is typically accessed via equity, such as an IPO, though for now, Kalshi users’ participation is limited to trading on the platform.

Across the three platforms, the split is structural: Hyperliquid already ties usage to a token, Polymarket appears to be moving in that direction, and Kalshi’s model likely prevents it altogether.