Home Blog Page 195

Whale Opens $22.3M SPCX Long as Synthetic Price Hits 30% premium

0

SpaceX’s IPO is already spilling into crypto markets, where one whale has opened a $22.3 million leveraged long on SPCX, a synthetic pre-IPO perpetual contract tied to Elon Musk’s aerospace company.

Key takeaways:

  • The whale is already sitting on more than $1.15 million in unrealized profit.
  • Synthetic SPCX is trading near $175, roughly 30% above SpaceX’s $135 IPO price.

Whale’s paper profits are over $1.15 million already

The whale’s position, visible on data resource Hypurrscan, shows the trader holding a 2x isolated long on “xyz:SPCX” worth about $22.29 million.

Address 0x9cc1… open perpetual positions as of Friday. Source: Hypurrscan

The whale entered near $168, while SPCX recently traded around $175, leaving the position with roughly $1.15 million in unrealized profit. It had spent just over $500 in funding fees.

Synthetic SPCX trades at 30% premium ahead of IPO

SpaceX has priced its IPO at $135 per share to raise $75 billion by selling about 555.6 million shares, bringing the company’s valuation to around $1.77 trillion. The stock is expected to trade under the ticker SPCX on Nasdaq.

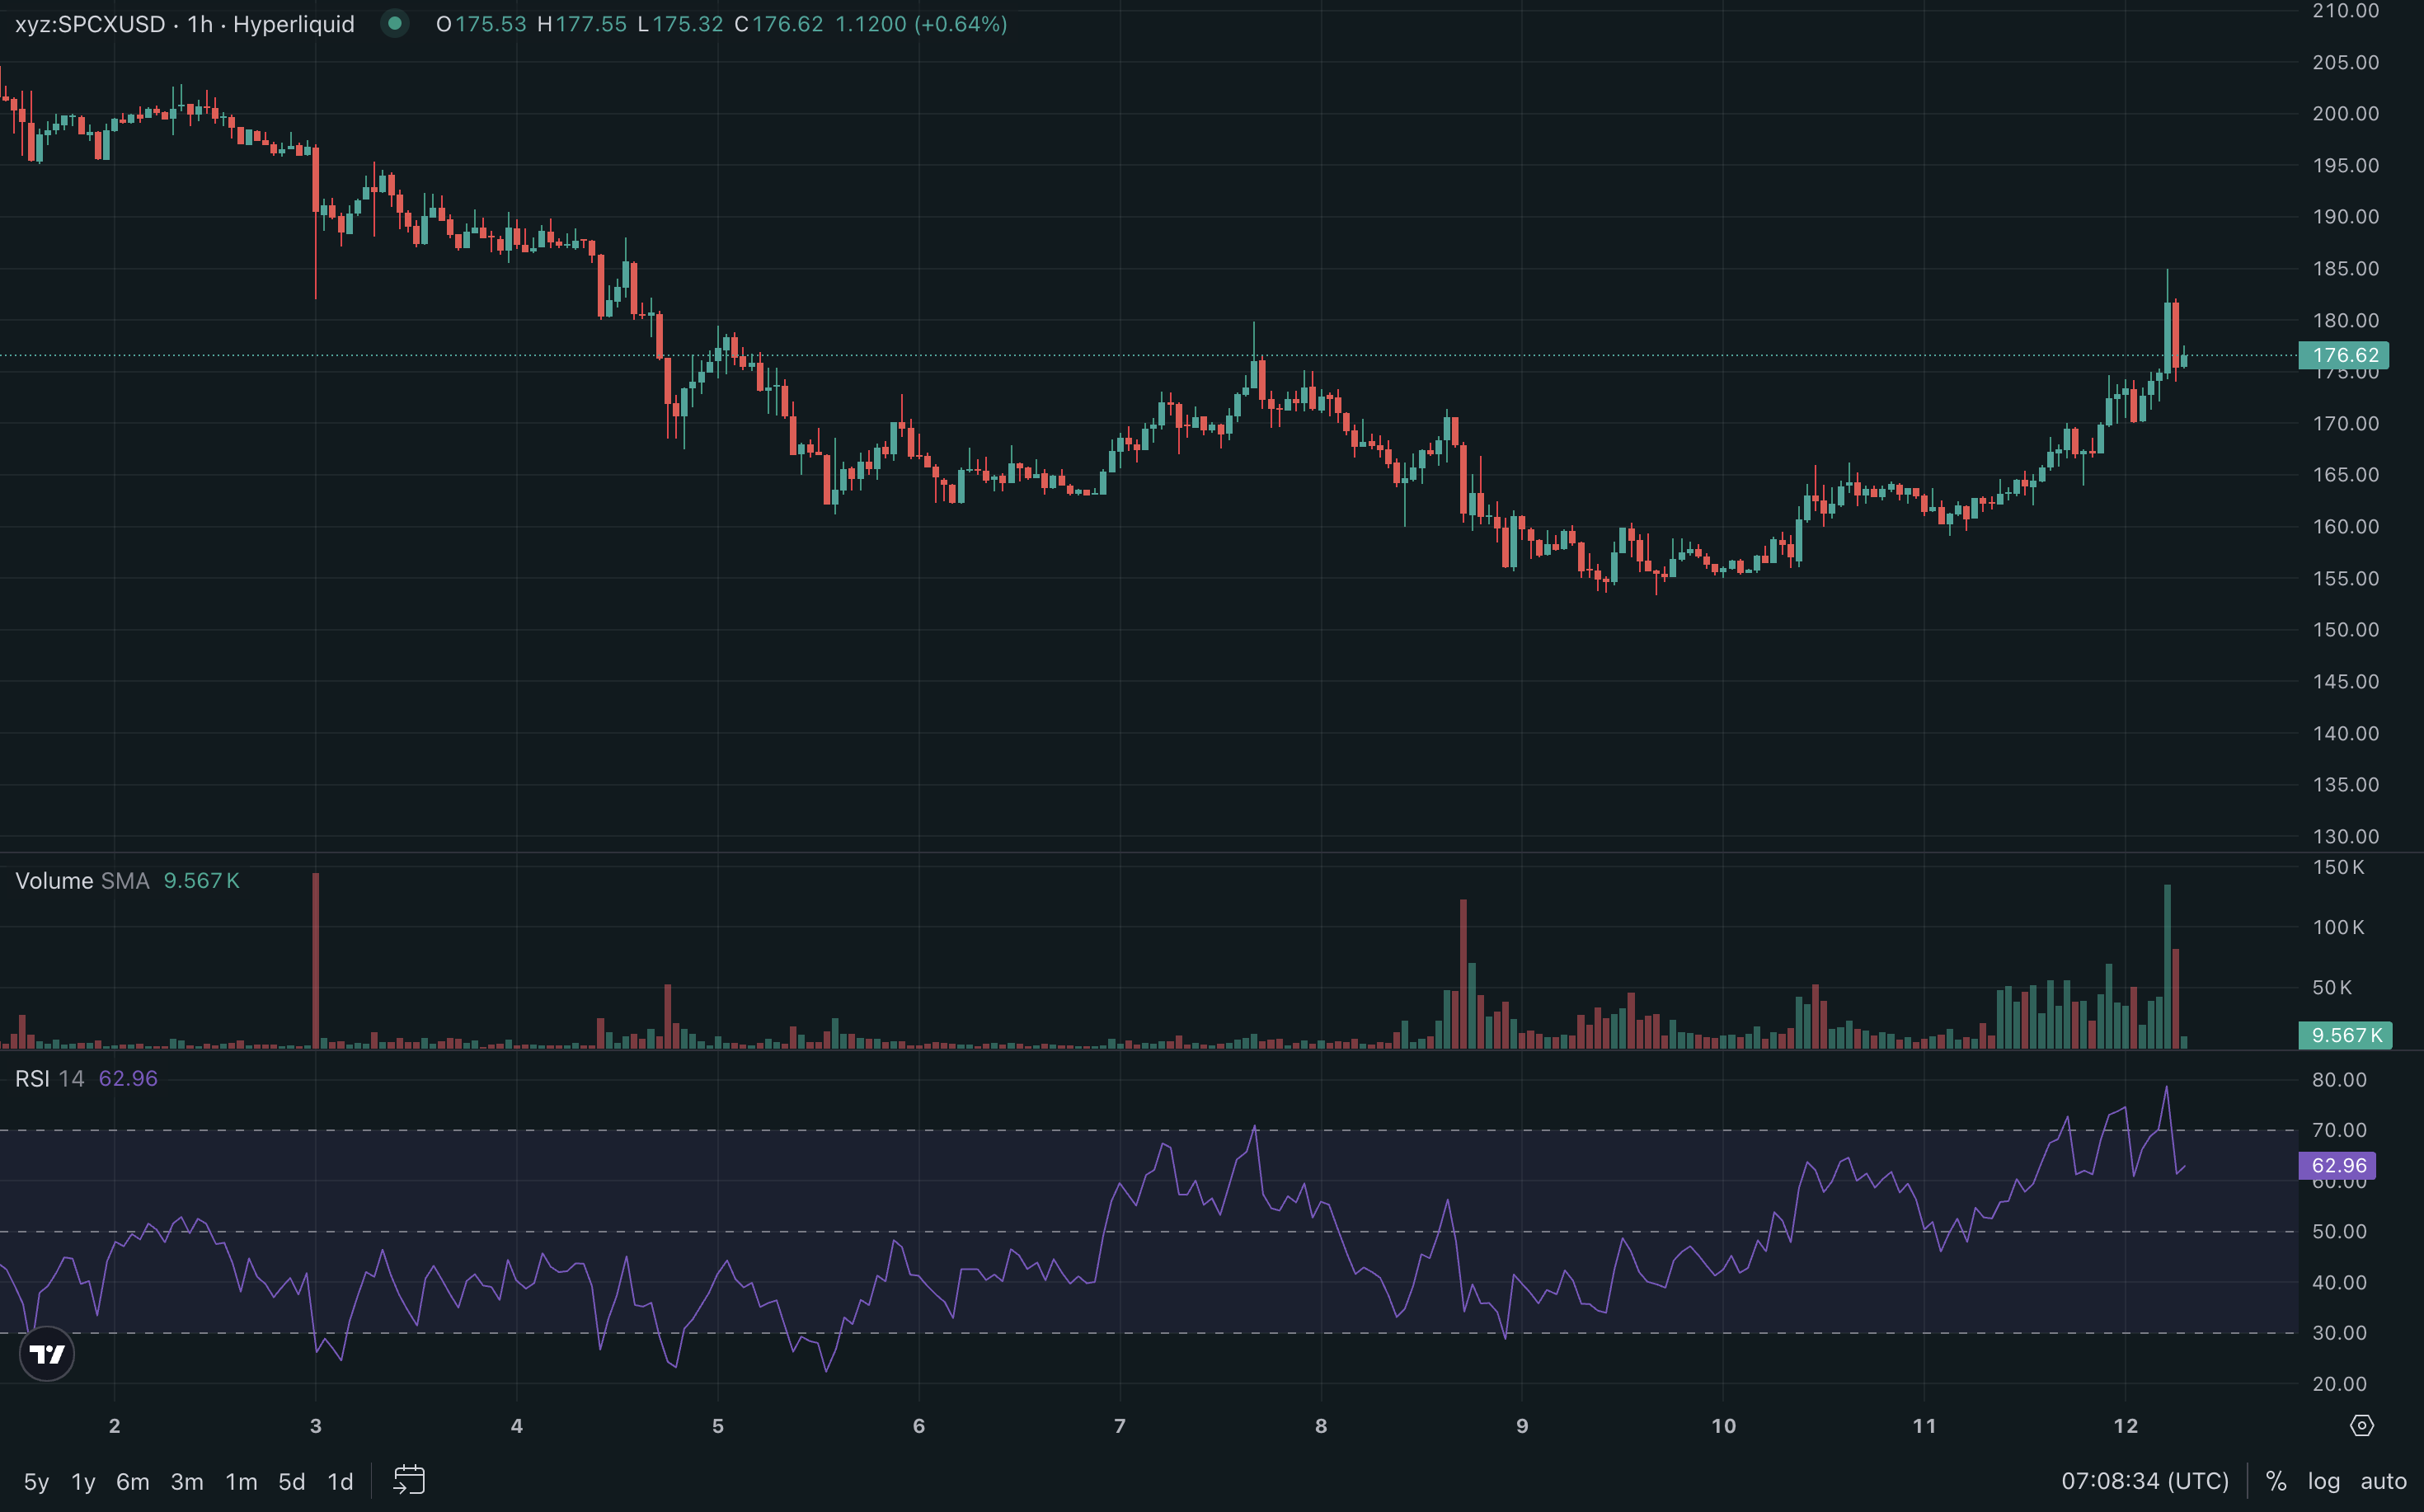
At around $175, the synthetic SPCX market is trading about 30% above the IPO price. In other words, crypto traders are already pricing in a strong first-day rally before regular equity markets fully absorb the listing.

SPCX/USDC hourly chart. Source: Hyperliquid

Other secondary markets are pointing in the same direction. For instance, IG International derivatives implied a SpaceX valuation of about $2.4 trillion, more than 35% above the valuation set by the IPO price.

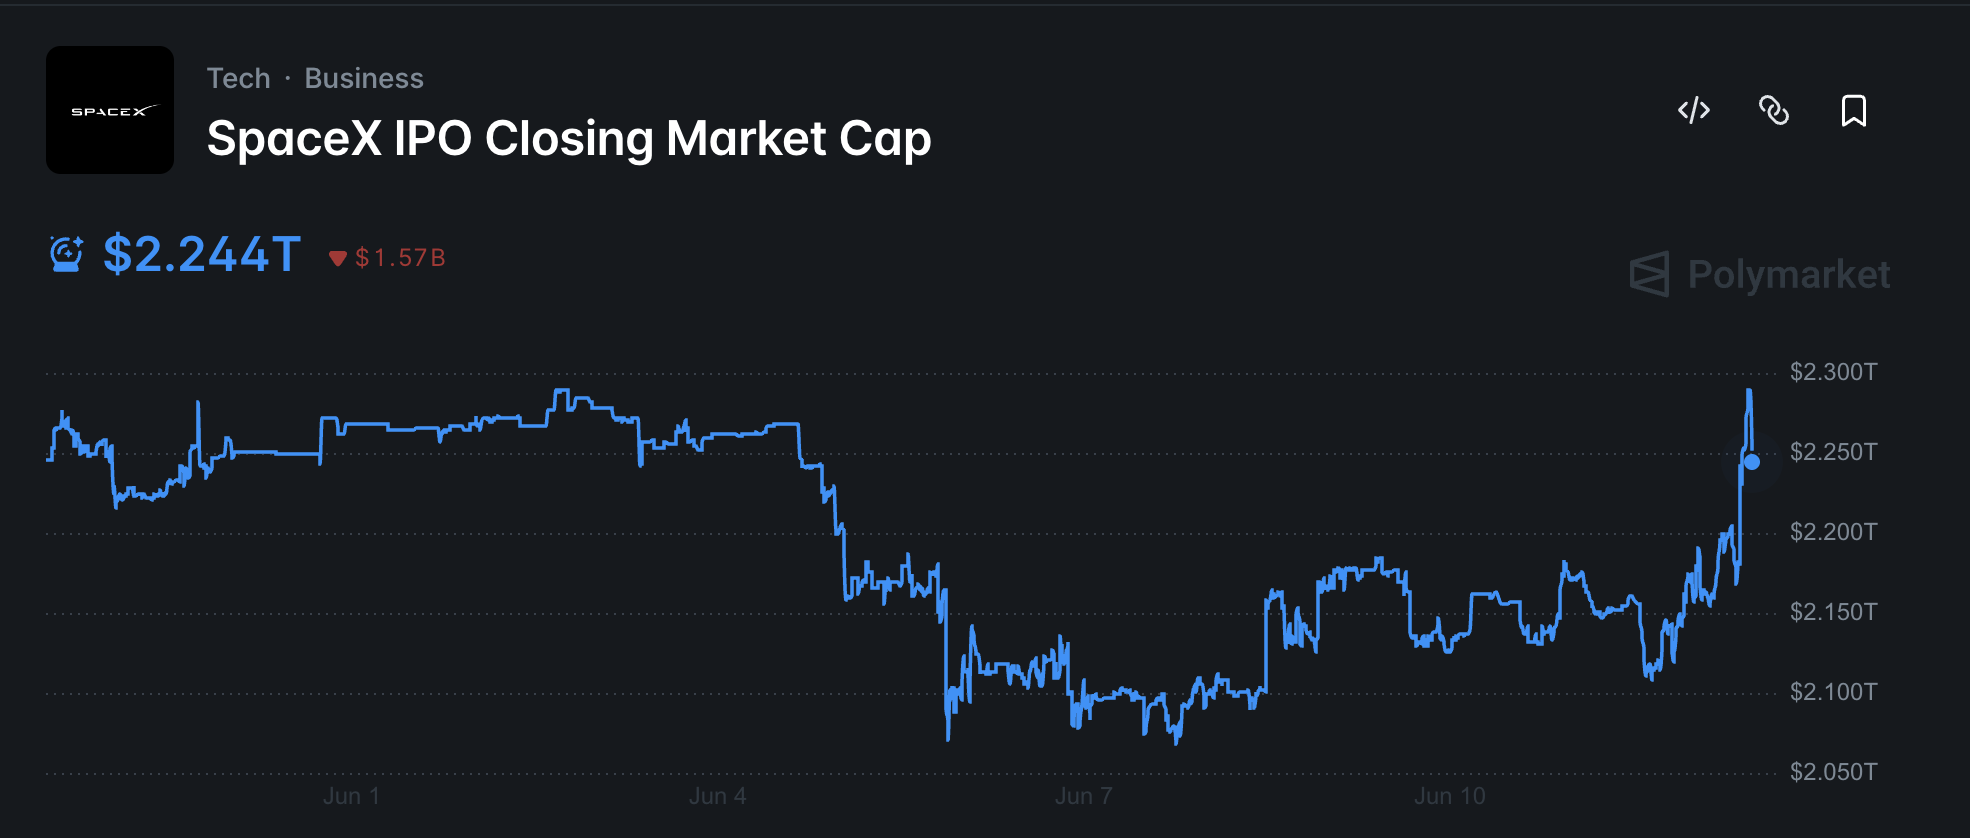
Polymarket traders put 56% odds on SpaceX closing its first trading day in the $2 trillion–2.5 trillion market cap range.

SpaceX IPO closing market cap. Source: Polymarket

History of IPOs warns of a strong SPCX correction after debut

The 30% SPCX premium points to strong opening demand, but IPO history argues against chasing the first trade.

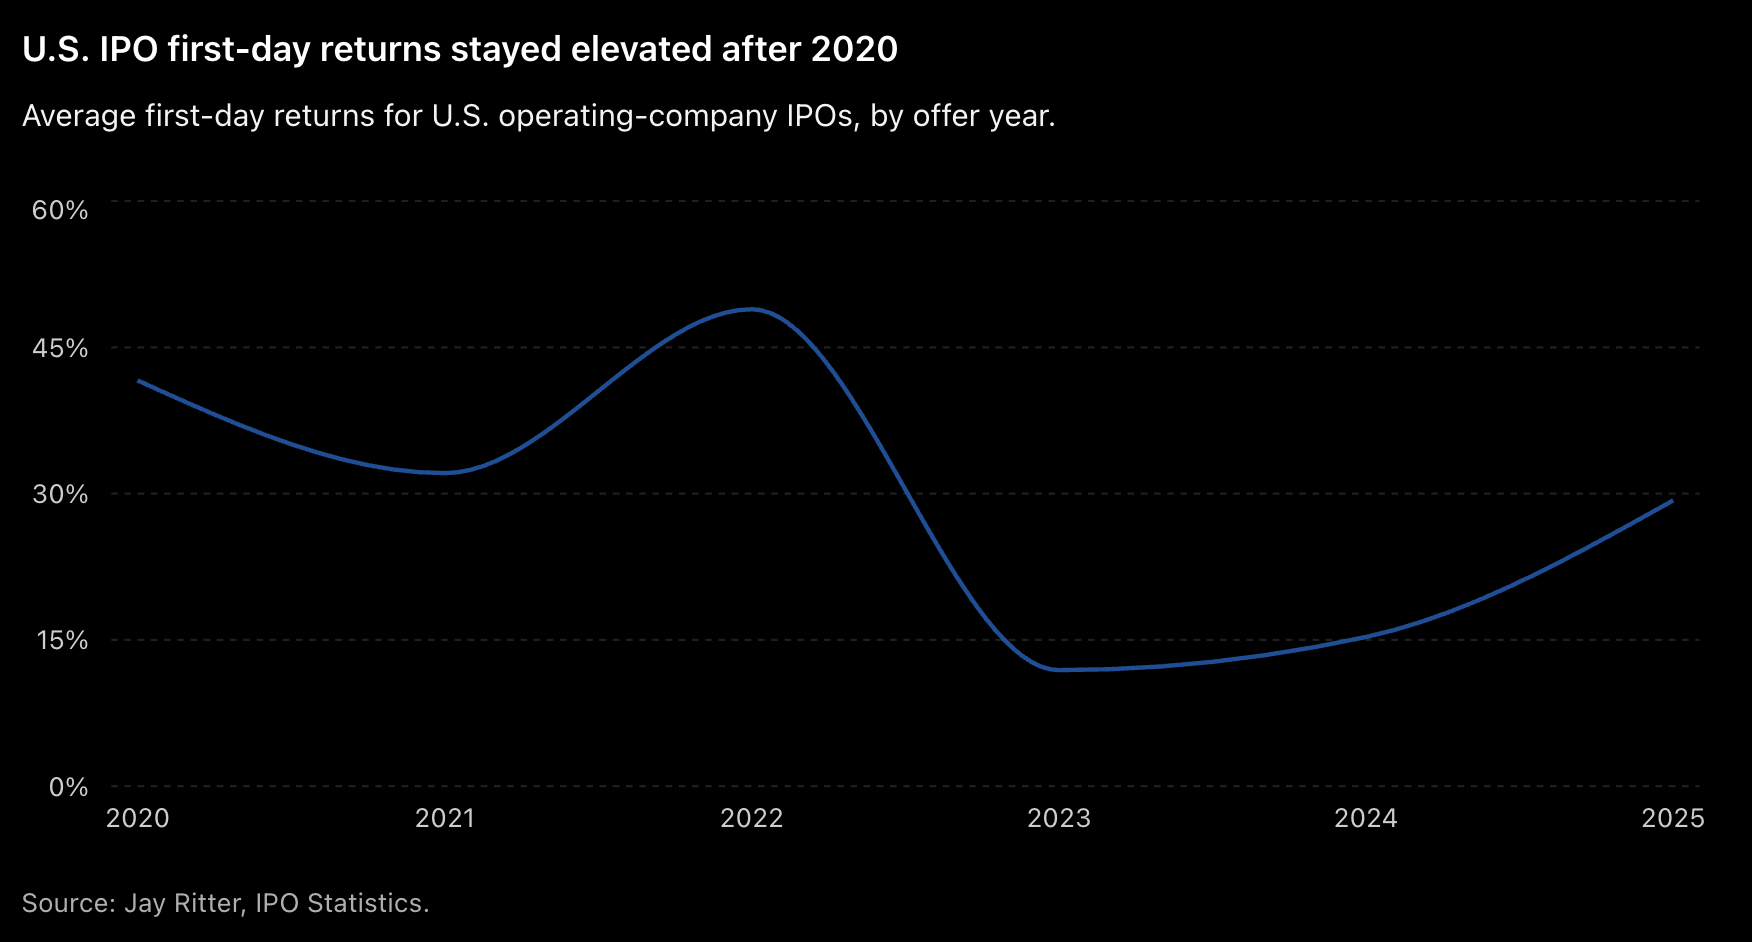
US IPOs from 2020 to 2025 averaged roughly 30% first-day gains, according to Jay Ritter’s IPO database. However, that upside mostly benefits investors who receive shares at the offer price.

US IPO average first-day returns. Source: Jay Ritter/IPO Statistics

Buyers who enter after the opening print often face a weaker setup, particularly after the initial euphoria fades.

Ritter’s long-run IPO data show that companies with positive first-day returns averaged a 29.6% debut gain from 2001 to 2024, but then underperformed the market by 8.5 percentage points over the next three years.

Related: SpaceX IPO nears 4 times oversubscribed, squeezing crypto and tech

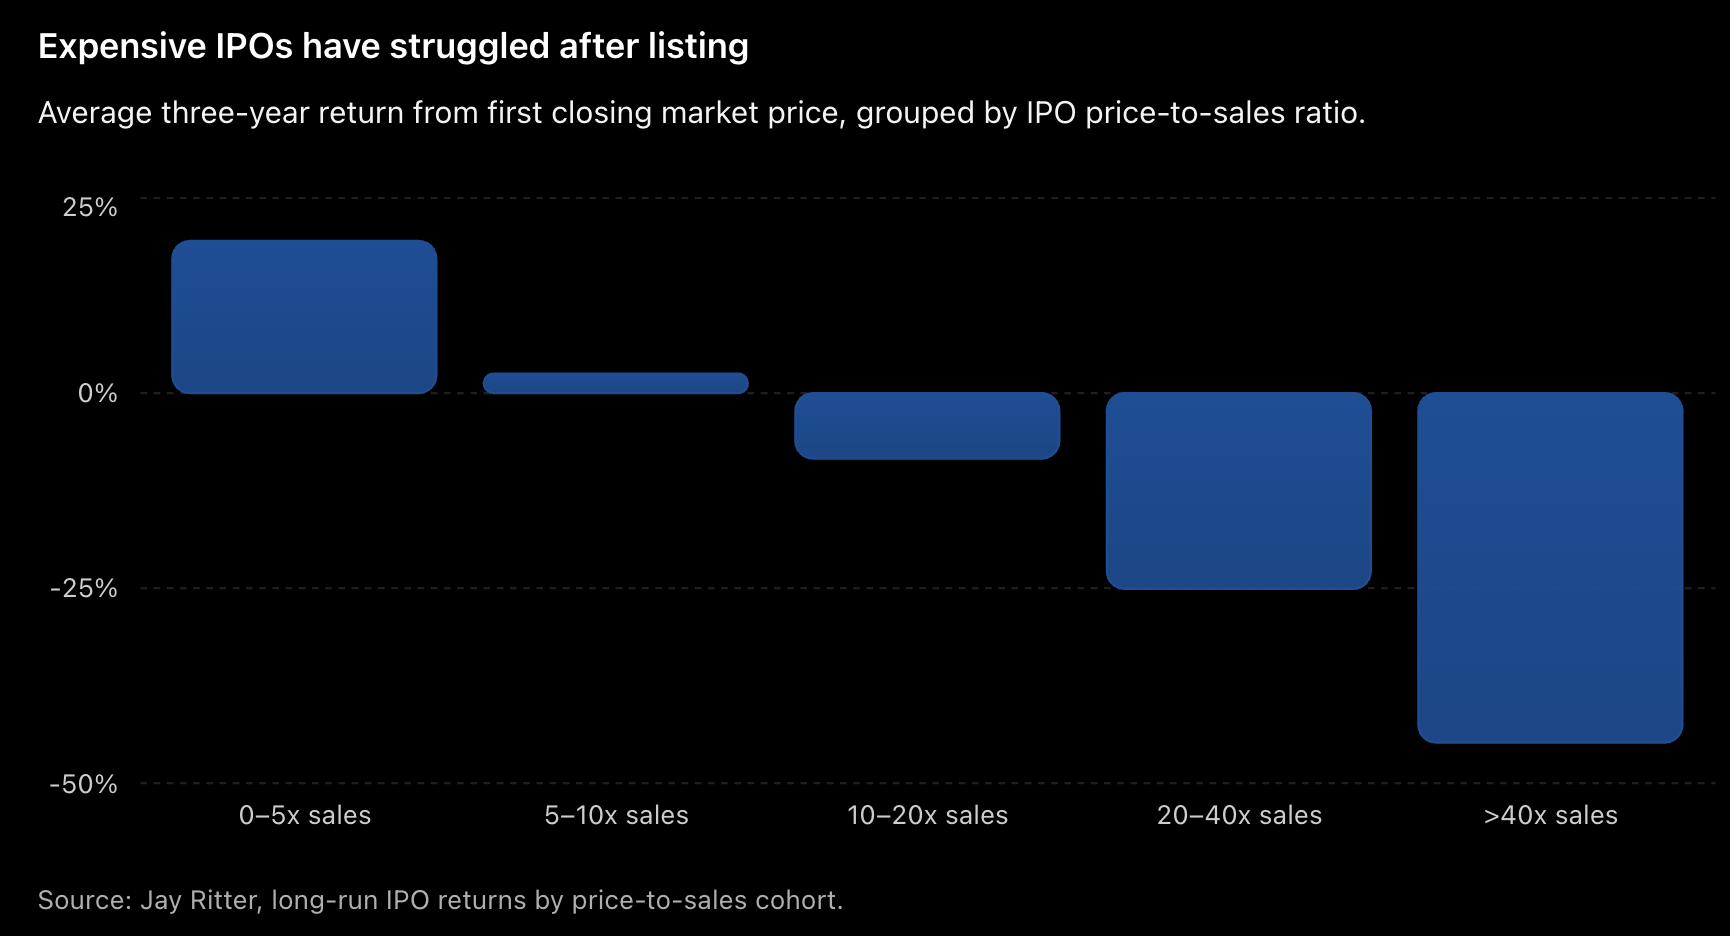
High-valuation IPOs have performed even worse. Among IPOs with trailing sales above $100 million and price-to-sales ratios above 40, buyers at the first close saw an average three-year return of -44.8%.

Long-run IPO returns by price-to-sales ratio. Source: Jay Ritter

SpaceX is going public at nearly 94 times the trailing sales, making it one of the most oversubscribed IPOs ever.

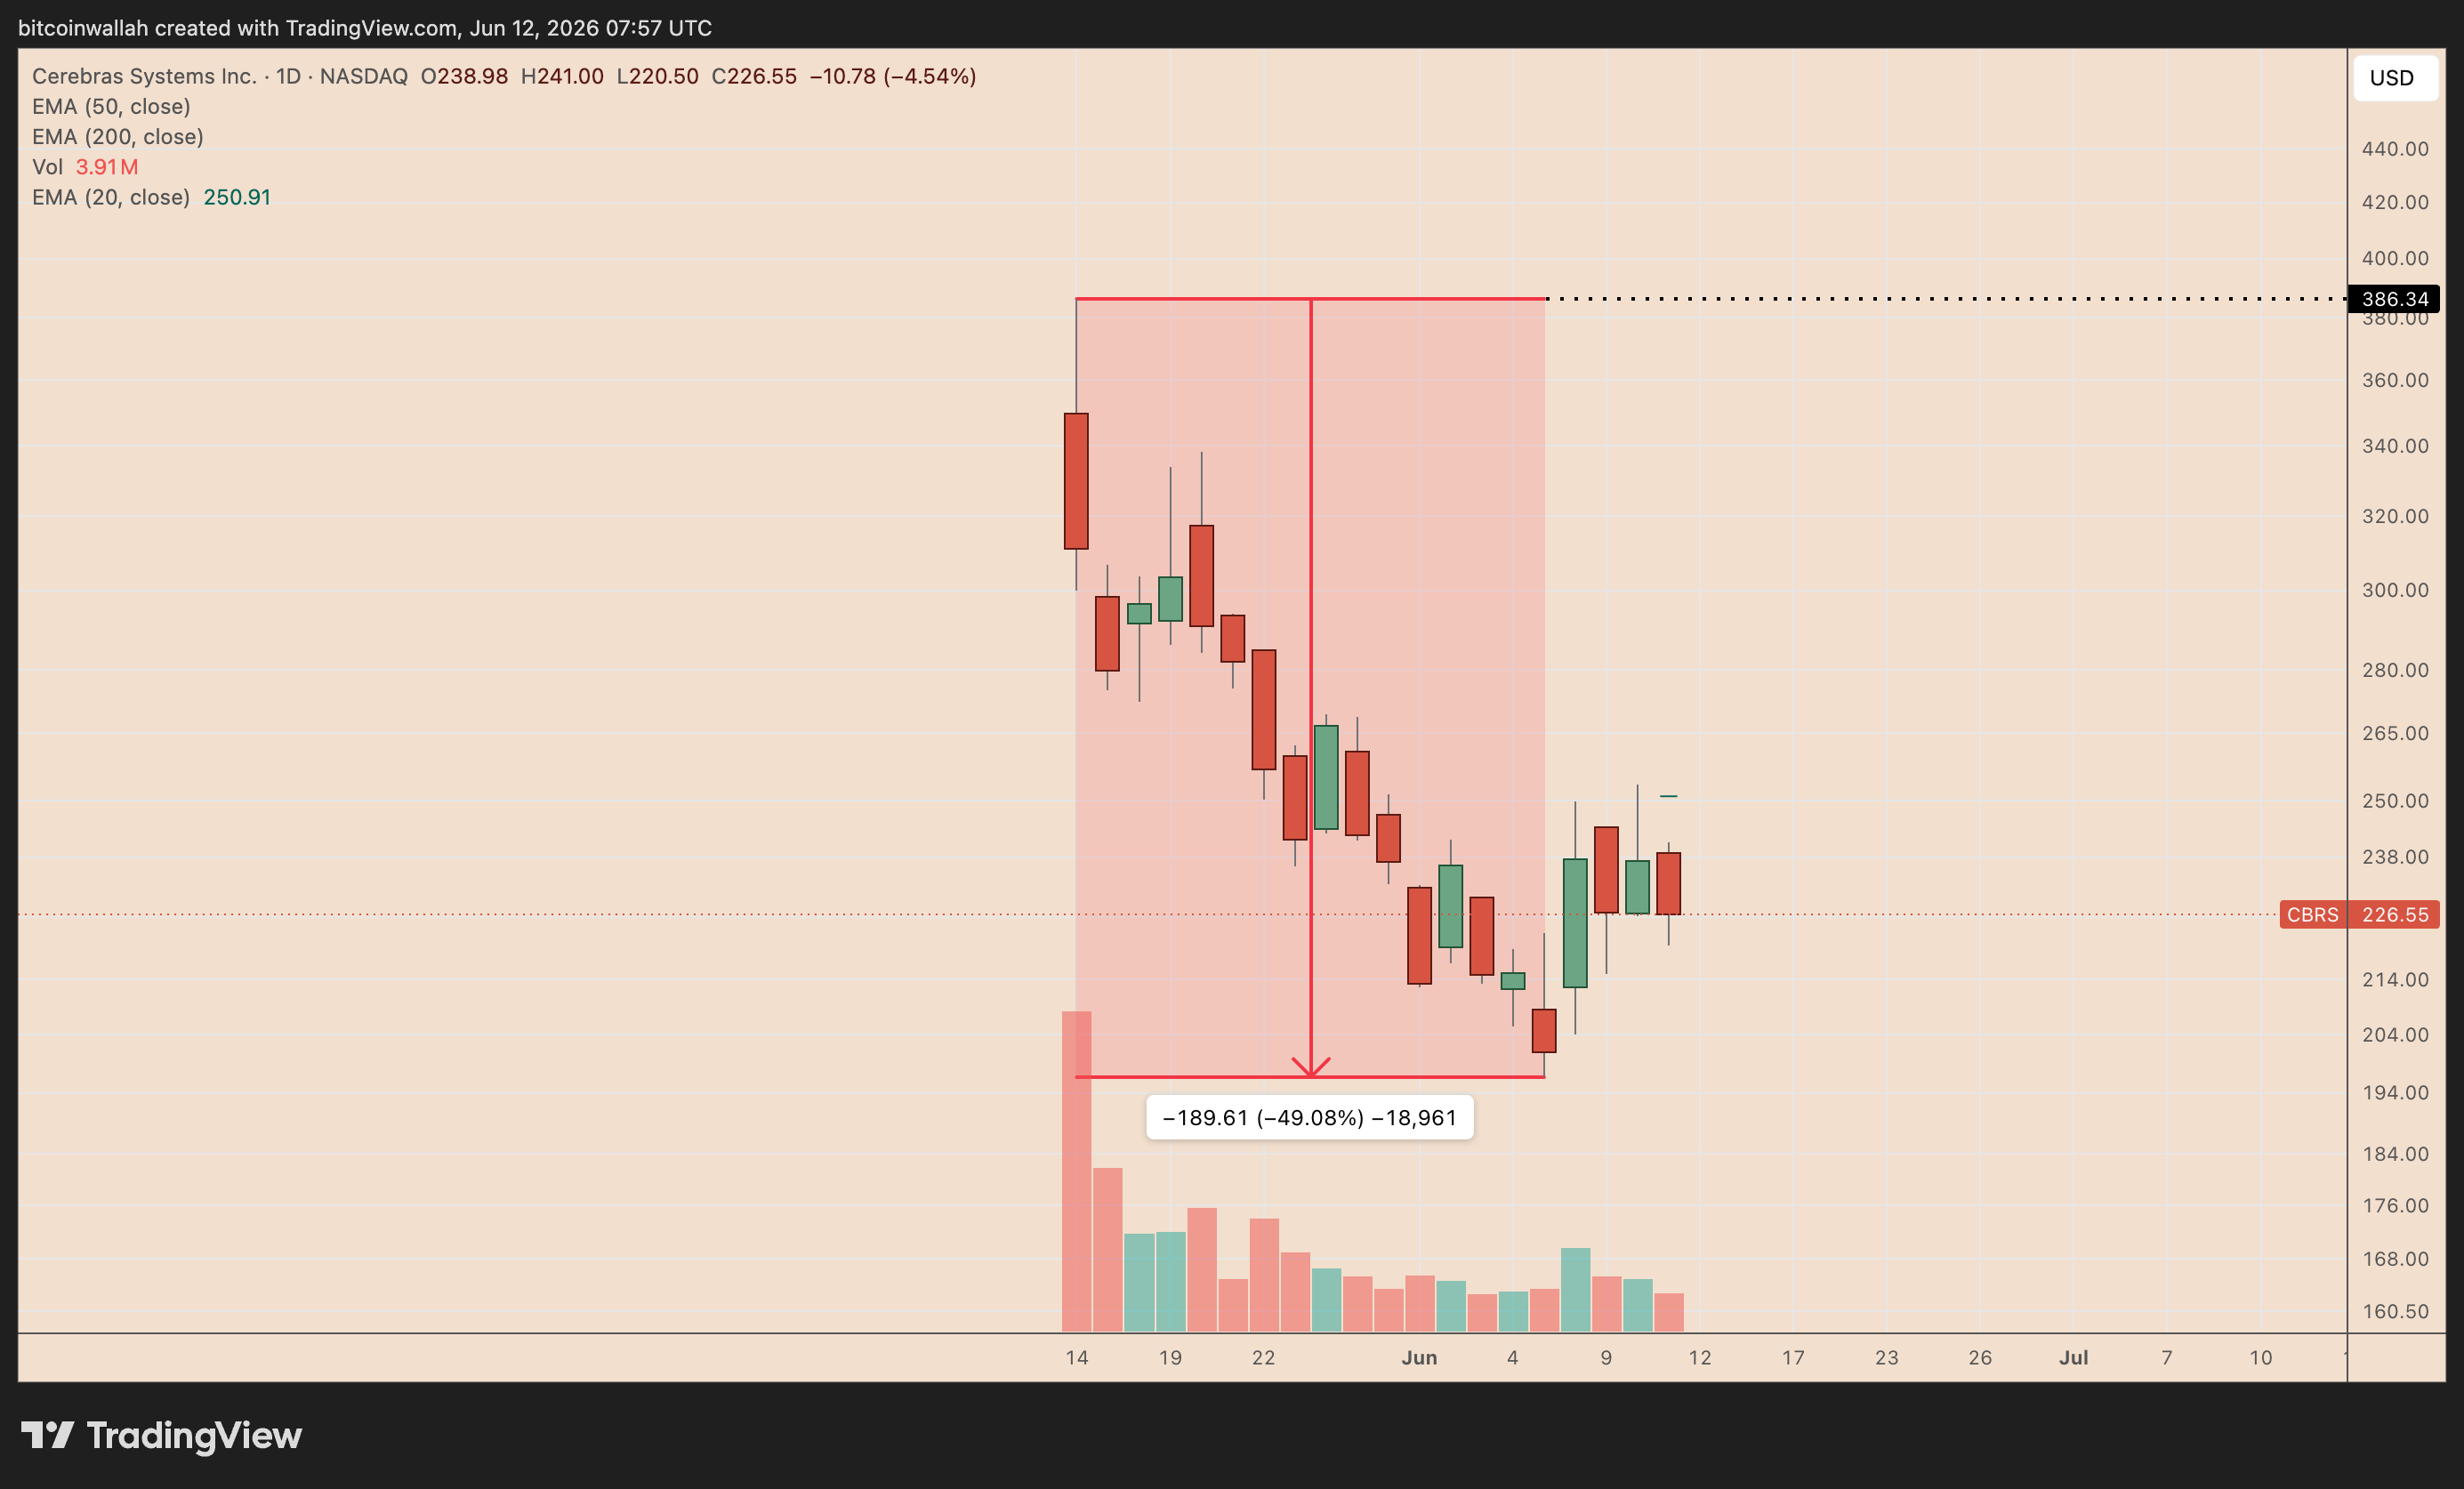
Recent listings showed the same risk. Nasdaq-listed Cerebras (CBRS), a semiconductor company, priced its IPO at $185, opened at $350 and closed its first day near $311, but later fell to around $197, a roughly 50% drop from its first-day peak.

CBRS daily chart. Source: TradingView

Rivian (RIVN) and Uber (UBER) also struggled after strong early attention, with lockup expirations adding pressure as insiders and early investors became free to sell.

SpaceX is overvalued

Several prominent voices have warned that SPCX could fall after the debut.

Morningstar’s Nicholas Owens valued the company at just $780 billion, roughly 55% below the IPO price, calling it significantly overvalued and advising investors to wait for the stock to settle.

NYU professor Aswath Damodaran put the fair value around $1.25–1.3 trillion and described the $135 offer price as “rich.”

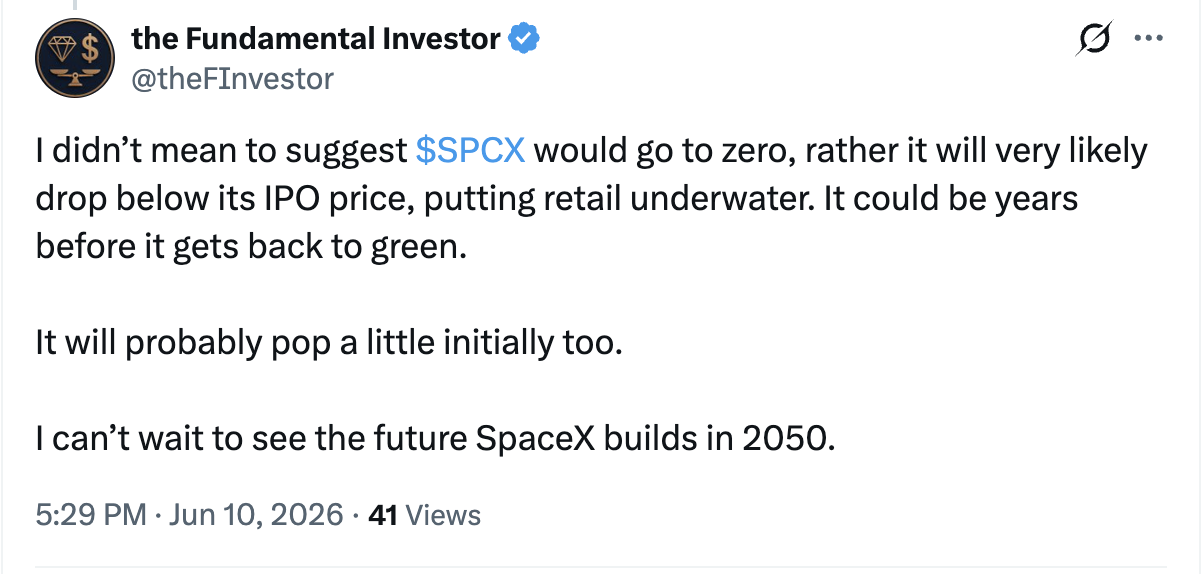
In a Wednesday post, analyst The Fundamental Investor said the stock is very likely to drop below the IPO price, potentially leaving early retail buyers underwater for years.

Source: X

The whale’s liquidation level sits near $93.27. The position could incur an estimated loss of about $9.4 million if SPCX falls to that level.

Gensler Files Brief Arguing Sports Prediction Markets Fall Outside CFTC Swap Rules

0

Former CFTC and SEC chair Gary Gensler filed an amicus brief with the Sixth Circuit arguing that sports-event prediction markets are not swaps under Dodd-Frank, directly contradicting the CFTC’s own position in the KalshiEX v. Ohio appeal.

Gary Gensler, the former chair of both the CFTC and the SEC, filed an amicus brief Thursday with the Sixth Circuit Court of Appeals arguing that sports-event prediction markets are not federally regulated swaps under Dodd-Frank. The brief sides with state regulators against Kalshi, one of the largest prediction-market platforms, in the latest round of the federal-versus-state jurisdiction battle over prediction markets.

Gensler filed the brief in KalshiEX LLC v. Matthew Schuler, a case Kalshi brought in October to block Ohio regulators from enforcing the state’s gambling laws against it. Chief Judge Sarah Morrison of the US District Court for the Southern District of Ohio denied Kalshi’s request for a preliminary injunction in March, and the company appealed to the Sixth Circuit.

The fight turns on whether sports-event contracts qualify as swaps, which fall under the CFTC’s exclusive jurisdiction. If they do, state gambling laws cannot reach them. Courts have split on the question, raising the prospect of Supreme Court review of a market that, by the CFTC’s own count, saw trading volume across registered prediction markets exceed $25 billion in 2025.

Gensler Breaks With the Agency He Led

The filing puts Gensler at odds with the CFTC. The Commission filed its own amicus brief in the same case on May 12, asserting exclusive jurisdiction over prediction markets and arguing that states cannot treat swaps traded on a designated contract market as illegal gambling. Gensler’s brief counters that sports-event contracts fall outside the statutory definition of a swap, which he argues centers on hedging economic risk.

Gensler led the CFTC’s implementation of Dodd-Frank as chair from 2009 to 2014 and helped draft the law’s swap provisions. His brief argues that Congress never intended Dodd-Frank to displace state authority over sports betting. Reading the swap definition to cover sports bets, he writes, would mean every off-exchange wager placed since October 2012 has been illegal, a result he says no one in Congress or the courts contemplated.

A Multi-Front Legal Battle

The Sixth Circuit case is one of several moving through the courts at once. The Third Circuit ruled in April that New Jersey could not shut down Kalshi’s prediction markets, the first federal appeals court to hold that the Commodity Exchange Act preempts state gambling laws for sports-event contracts. A Ninth Circuit panel hearing Nevada’s cases against Kalshi, Crypto.com and Robinhood appeared more receptive to the states’ arguments at an April hearing.

The CFTC has gone on the offensive against the states, suing Wisconsin and Rhode Island to block enforcement. Separately, the New York Attorney General sued Coinbase and Gemini over unlicensed prediction-market activity.

The Special Rule Question

The CFTC published a notice of proposed rulemaking on event contracts in the Federal Register on June 10, proposing a framework to determine whether contracts involve enumerated activities such as gaming and are contrary to the public interest. Gensler filed his brief the following day.

That rulemaking rests on Dodd-Frank’s “Special Rule,” which Gensler’s brief addresses directly. He argues the rule does not define gaming contracts as swaps but instead gives the CFTC authority to bar regulated exchanges from listing them. That reading, if adopted, would cut against Kalshi’s claim that Congress placed sports betting under exclusive federal jurisdiction.

ETH Futures Bearish, But Staking, Corporate Demand Show Strength

0

Key takeaways:

  • While bearish ETH futures trends and spot ETF outflows signal weak institutional appetite, staking demand prevents further decline.
  • Falling exchange deposits and accumulation by BitMine indicate holder confidence in ETH’s long-term value.

Ether (ETH) price failed to reclaim the $1,700 level over the past week, tracking a broader weakness across cryptocurrency markets. This correction contrasts sharply with the bullish momentum seen in the US stock market. Traders worry that Ether’s appeal has faded due to sluggish on-chain activity and a distinct lack of demand for bullish leveraged positions.

ETH futures annualized funding rate. Source: Laevitas

The ETH perpetual futures annualized funding rate flipped negative on June 5, meaning shorts are paying premiums to keep their positions open. Bullish traders remain uncomfortable adding risk despite a 30% price correction over the past five weeks. The ETH futures aggregate open interest has also dropped significantly, indicating a pullback in institutional activity.

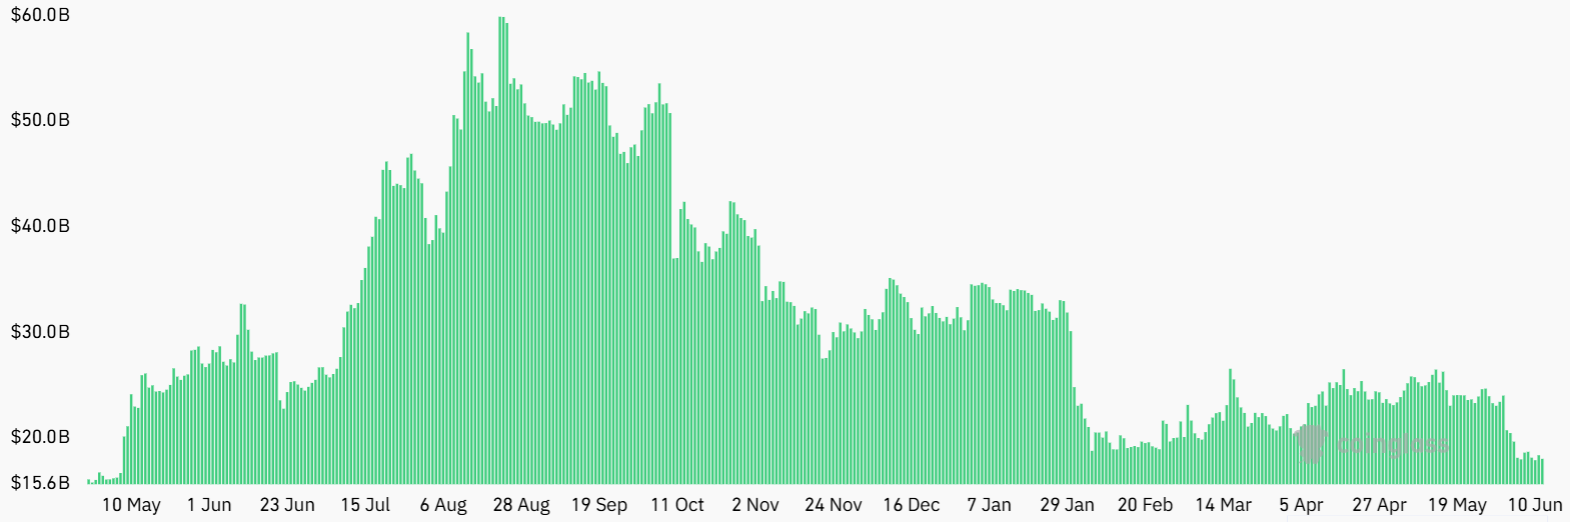
ETH futures aggregate open interest on major exchanges, ETH. Source: CoinGlass

Total exposure on ETH futures has fallen 30% in a month, hitting a 13-month low. This shrinking institutional appetite is evident in US-listed Ether spot exchange-traded funds, which posted $323 million in net outflows over two weeks.

ETH staking demands contrast with weak on-chain activity

Regardless of whether the decline in ETH futures demand can be pinned to record-breaking demand for the SpaceX (SPCX US) IPO, the impact on trader sentiment remains negative. Declining Ethereum on-chain activity has likely fueled this ETH price downtrend.

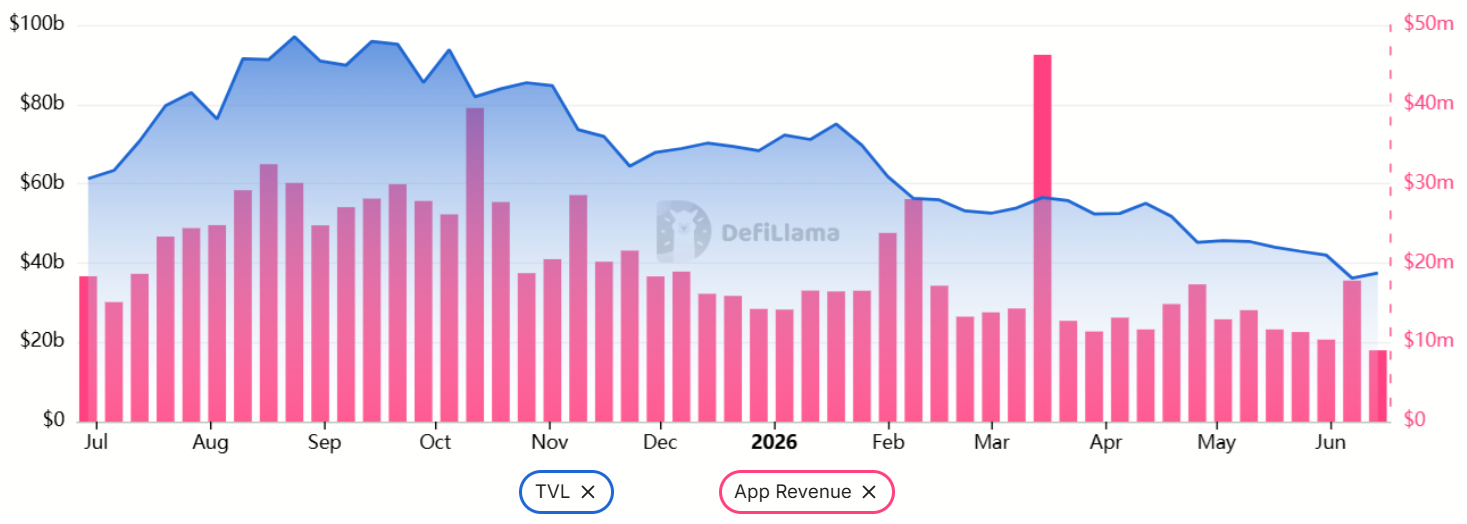
Ethereum Total Value Locked vs. weekly DApp revenue, USD. Source: DefiLlama

The total value locked (TVL) on the Ethereum network dropped 33% in two months to $37.5 billion. Concurrently, decentralized application (DApp) revenues plunged 43% in May compared to the previous six months. This reduced on-chain volume is typically associated with lower network fee generation and falling ETH utility.

Curiously, rising demand for Ethereum staking contrasts sharply with the bearishness in ETH derivatives. Staking approval for US-listed ETFs and aggressive accumulation by BitMine (BTMN US) vastly outpaced outflows during the period, despite a modest 2.7% yield.

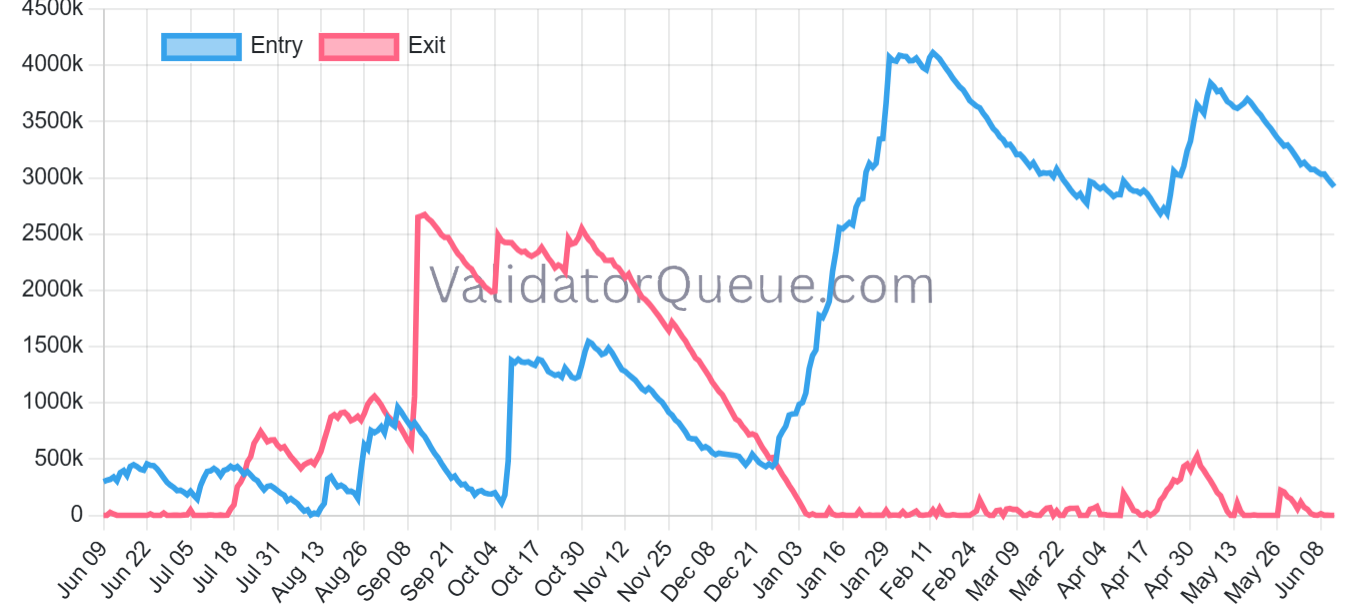
ETH staking validator queue, ETH. Source: ValidatorQueue

The entry queue for ETH staking validators currently sits at 50 days, totaling over 2.9 million ETH. In contrast, the exit queue has zero wait time, a major sign of strength, given that 39.5 million ETH are currently staked. While there is no guarantee that stakers will lock up their tokens forever, this metric signals deep confidence in Ethereum’s long-term prospects.

Related: ETH futures traders lean into $1.6K range lows: Will Ether lead market recovery?

ETH estimated balance on exchanges, ETH. Source: Glassnode

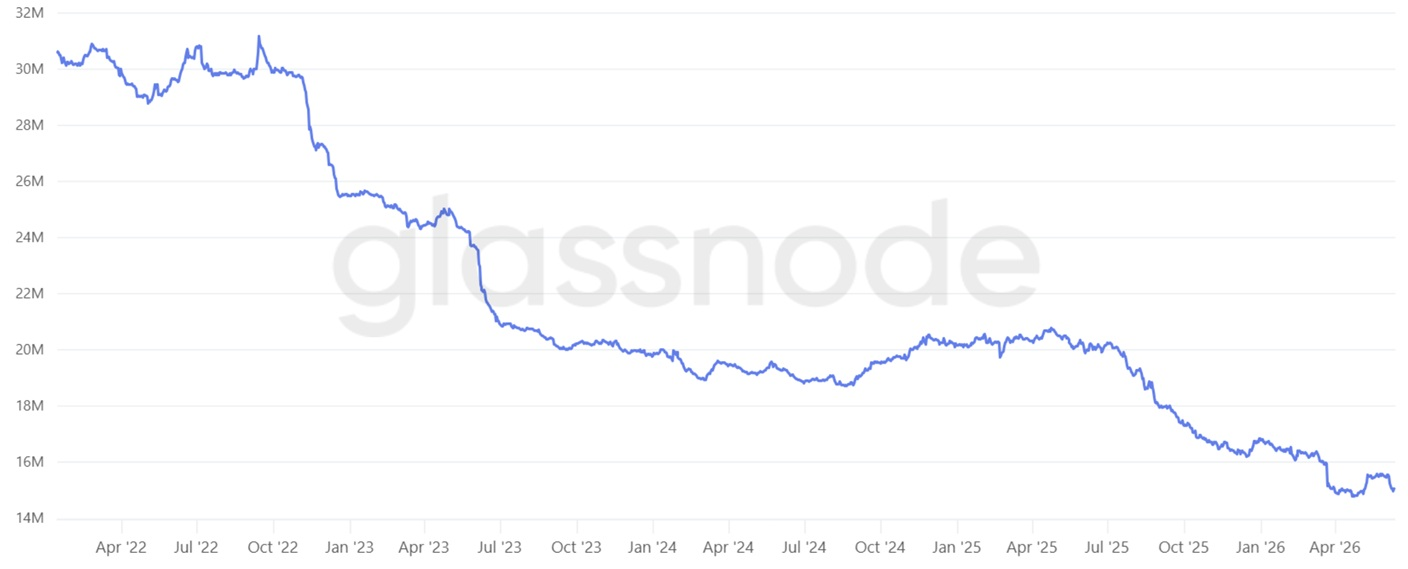
Meanwhile, exchange-held ETH deposits dropped to 15.05 million from 16.15 million three months ago, pointing to heavy accumulation. This shift was partly driven by BitMine, which added 337,078 ETH to its balance sheet over the past 30 days, according to CoinGecko data.

Ultimately, weak demand for bullish ETH leverage shouldn’t be misread as a sign of rising downside risk. As long as staking metrics stay solid and spot ETF outflows remain reasonably contained, the odds of an ETH price crash to $1,500 look slim.

Polish President Vetoes Crypto Bill for Third Time ahead of MiCA Deadline

0

Polish President Karol Nawrocki vetoed a cryptocurrency regulatory bill for the third time, which sought to implement Europe’s Markets in Crypto Assets Regulation (MiCA) in the country.

Nawrocki said Thursday he supports regulating the cryptocurrency market but argued that the government incorporated only one of 16 key amendments proposed by his office. He said that the text was nearly identical to the previous two drafts he refused.

The third veto of the bill delays Poland’s alignment with the EU-wide regulatory framework just weeks before the end of MiCA’s transitional period on July 1. Following the end of the grace period, crypto asset service providers will be required to hold a MiCA license or stop servicing EU clients.

Poland is currently the only EU member state without a domestic MiCA implementation. Following the July 1 deadline, Poland-based crypto asset service providers without a MiCA license may lose the legal basis to serve EU customers.

Related: MiCA architect says EU should prioritize tokenization over DeFi rules

Polish Prime Minister Donald Tusk slammed the veto in a Thursday X post, writing: “It sounds unbelievable, but the president has vetoed the cryptocurrency bill again. He seems more entangled in it than everyone thought.”

Source: Donald Tusk

Political deadlock deepens over crypto bill

The decision adds to Poland’s political standoff on how the country should oversee crypto assets. It comes nearly two months after Poland’s parliament failed to reverse the second veto issued by President Nawrocki.

Lawmakers fell short of the 263 votes needed to override the veto in an April vote on the bill, which is backed by Tusk’s government and seeks to align Poland with MiCA.

Nawrocki has reportedly defended his opposition by citing concerns about excessive regulation, limited transparency and the potential burden on small businesses.

Government officials warned that delays leave consumers and businesses exposed to fraud and abuse.

The third veto comes as scrutiny of Poland’s crypto sector intensifies. Prosecutors are investigating one of Poland’s largest crypto exchanges, Zondacrypto, for suspected fraud and money laundering involving 2,000 customers with alleged links to Russian organized crime.

Zonda CEO Przemysław Kral has denied accusations of misappropriating funds.

Magazine: Crypto wanted to overthrow banks, now it’s becoming them in stablecoin fight

Cointelegraph is committed to independent, transparent journalism. This news article is produced in accordance with Cointelegraph’s Editorial Policy and aims to provide accurate and timely information. Readers are encouraged to verify information independently.

CFTC Sues New Mexico to Block State Gaming Laws From Reaching Federally Regulated Prediction Markets

0

The federal derivatives regulator filed suit Thursday in federal court seeking to bar New Mexico from enforcing state gaming laws against CFTC-registered prediction-market exchanges, making New Mexico the eighth state to face federal litigation over the question of exclusive jurisdiction.

The Commodity Futures Trading Commission filed suit Thursday in federal court against New Mexico, seeking to prevent the state from applying its gaming laws to CFTC-registered prediction-market exchanges.

The CFTC’s complaint seeks a declaratory judgment that federal law grants the agency exclusive authority to regulate event contracts and requests a permanent injunction barring New Mexico from enforcing state gaming statutes against its registrants. The filing comes roughly a week after New Mexico sued CFTC-registrant KalshiEX LLC in state court, alleging its sports-event contracts amount to unlawful online sports betting.

“New Mexico is the latest state seeking to nullify black letter law and decades of judicial precedent by imposing state gaming laws on federally regulated derivatives exchanges subject to the CFTC’s exclusive jurisdiction,” CFTC Chairman Michael S. Selig said in the press release. “The CFTC has the expertise and responsibility to protect its exclusive jurisdiction over commodity derivatives, and that’s exactly what we’ll continue to do.”

New Mexico Attorney General Raúl Torrez filed the state-court action on June 4, alleging Kalshi operated an unlicensed sportsbook and allowed users aged 18 to 20 to participate despite the state’s minimum gaming age of 21. The state sought an injunction blocking sports-related event contract trades and a declaration that such contracts qualify as sports wagering under New Mexico law.

The CFTC’s position rests on the Commodity Exchange Act, which the agency says preempts state laws purporting to regulate designated contract markets. New Mexico becomes the eighth state to face federal litigation over the issue. The CFTC first sued Arizona, Connecticut, and Illinois in April, then extended its campaign to New York, Minnesota, Rhode Island, and Wisconsin. The Defiant previously covered the Wisconsin filing when it expanded the jurisdictional arc in late April.

The litigation intensifies an already crowded federal-state standoff. Former CFTC and SEC Chair Gary Gensler filed an amicus brief this week at the Sixth Circuit arguing sports prediction markets fall outside CFTC swap rules, directly contradicting the agency’s own position. The CFTC separately published proposed rules on event contracts this week covering enumerated activities including sports.

The outcome of the state-court disputes and parallel federal litigation will determine whether prediction markets operate under a single federal regulatory framework or face a patchwork of state-level gaming enforcement.

Blockworks Acquires Messari In Deal Highlighting Crypto’s Data Consolidation Race

0

Blockworks, the New York-based crypto data and investor relations platform, has acquired rival Messari in a deal that underscores the growing consolidation pressure reshaping the digital asset industry — and the steep valuation resets facing once high-flying crypto startups.

The acquisition brings together two of the industry’s largest crypto information businesses. Messari, founded in 2018, built a comprehensive data platform covering more than 40,000 digital assets, along with APIs, market intelligence, research tools, and AI-powered workflows used by funds, exchanges, regulators, and developers. 

Blockworks, also founded in 2018, has focused on the issuer side of crypto capital markets, offering standardized disclosures through its Token Transparency Framework and a full-stack investor relations platform for onchain assets.

Blockworks paid more than $10 million for Messari — a steep discount from Messari’s approximately $300 million valuation when it raised a $35 million Series B led by Brevan Howard’s crypto arm in 2022, with Point72 Ventures also among its backers, according to the Wall Street Journal. 

The markdown reflects both Messari’s recent difficulties — including the 2024 departure of co-founder and longtime CEO Ryan Selkis and subsequent staff reductions — and broader headwinds gripping the crypto sector.

“This acquisition connects the two sides of the market,” said Jason Yanowitz, co-founder of Blockworks. “Issuers maintain a trusted record of their business, and investors, exchanges, and regulators consume that record through research, APIs, and automated workflows.”

Blockworks raise to consolidate fragmented crypto data market

The deal was funded in part through Blockworks’ recently closed Series A extension, which valued the company at $192 million. That round was co-led by ParaFi and Reciprocal Ventures and included participation from Coinbase Ventures, among others. 

Blockworks said it raised capital specifically to consolidate crypto’s fragmented data and information market, drawing comparisons to how Wall Street’s information layer eventually coalesced around dominant platforms like Bloomberg, FactSet, and S&P Global.

Messari CEO Diran Li, who took over following Selkis’s departure and had been repositioning the firm as an “AI-first company,” will join Blockworks as a senior leader under co-founders Yanowitz and Michael Ippolito.

The deal arrives as crypto M&A activity remains elevated despite challenging market conditions. Crypto companies have completed 144 deals totaling $11.8 billion in transaction value so far in 2026 — up roughly 3.5% from the same period last year — according to data from advisory firm Architect Partners. 

Still, Eric Risley, founder of Architect Partners, warned that sustained pressure on trading volumes and token prices could force more distressed sales. “We are in the midst of the creation of the haves and the have-nots,” Risley said, per WSJ. 

Both Blockworks and Messari executives said the combined platform would prioritize deeper data coverage, stronger APIs, enhanced compliance workflows, and AI-native research tools as digital assets increasingly migrate onchain.

‘Peirce Out’: A Decade of Dissent

0

She arrived at the SEC in 2018 as a Republican commissioner with light crypto baggage and left this week as the regulator whose quotes had narrated the industry’s regulatory story. A retrospective on eight years of dissent.

Hester Peirce delivered her farewell remarks at the U.S. Chamber of Commerce on Tuesday and called the speech “Peirce Out.” She is leaving Washington after nearly thirty years for a teaching post at Regent University School of Law in Virginia Beach in November. Her second commissioner term expired in June 2025; she had been serving in a holdover capacity since.

Peirce arrived at the Commission on January 11, 2018, at a moment when crypto was both very large and almost entirely unregulated. Bitcoin had just printed an all-time high. Initial coin offerings had attracted billions of dollars the previous year, and Chairman Jay Clayton had issued a public statement on cryptocurrencies and ICOs the month before Peirce was sworn in, warning that “by and large, the structures of initial coin offerings that I have seen promoted involve the offer and sale of securities.” The SEC had already begun a first wave of enforcement actions against ICO issuers but had not articulated how, or whether, decentralized networks could come into the regulatory perimeter. Peirce inherited that gap and would spend eight years describing it.

She came to the role with the resume of a securities-law institutionalist who happened to be deeply skeptical of how the institution operated. A Case Western Reserve economics undergraduate and a Yale Law graduate, she clerked for Judge Roger Andewelt on the U.S. Court of Federal Claims, practiced at WilmerHale, then worked as a staff attorney in the SEC’s Division of Investment Management before serving as counsel to SEC Commissioner Paul Atkins during his 2002-2008 term. She left for the Senate Banking Committee under Ranking Member Richard Shelby, then conducted financial-regulation research at the Mercatus Center at George Mason University until her own commissioner appointment. Atkins, the colleague she had served two decades earlier, would later be confirmed as her chair.

The Crypto Mom Moment

The label arrived in her first summer. On July 26, 2018, the Commission rejected the Winklevoss brothers’ second application for a spot bitcoin exchange-traded product. Peirce dissented in writing, in language that would become her signature register.

“I reject the role of gatekeeper of innovation,” she wrote in her dissent, “a role very different from (and, indeed, inconsistent with) our mission of protecting investors, fostering capital formation, and facilitating fair, orderly, and efficient markets.” Investors, she added, “are generally better judges about these things than we are.” She posted the dissent to her then-young X account that afternoon with a one-line caption.

Crypto Twitter christened her Crypto Mom within hours. The moniker stuck because the dissent did something her colleagues’ approvals had not: it located the agency’s bitcoin posture inside a recognizable framework about regulatory humility. The Winklevoss order had rejected the ETP on market-integrity grounds. Peirce’s dissent argued the agency was applying a merit standard it did not apply to other commodity-based products. The two views would frame the Commission’s spot-bitcoin debate for the next five and a half years.

The dissent also began Peirce’s career-long practice of attaching wordplay titles to her statements. “Kraken Down,” “Outdated,” “Out, Damned Spot!”, “Rendering Innovation Kaput,” “Dealer, No Dealer?”, and “Peirce Out” were all hers. Industry counsel learned to read SEC speech indexes for her name not just for substance but for tone.

Safe Harbor That Wasn’t

If the Winklevoss dissent was Peirce’s diagnosis, the Token Safe Harbor was her treatment plan. On February 6, 2020, in a Chicago speech delivered at the Blockress conference, she proposed Securities Act Rule 195, a three-year grace period during which crypto network developers could distribute tokens without registering the offering as a securities sale, provided they met disclosure and good-faith decentralization conditions. The speech opened, characteristically, with a long anecdote about being stranded with an empty gas tank on a rainy night in New Jersey. The road-trip metaphor would become a recurring Peirce device, surfacing again five years later when she titled her opening statement as Crypto Task Force chair “The Journey Begins.”

The speech was unusual for what it conceded. “The fear of running afoul of the securities laws is real,” Peirce told the audience. “Given the SEC’s enforcement activity in this area, these fears are not unfounded.” The acknowledgement, from a sitting commissioner, that the agency’s own posture was deterring legitimate development was a position no Chair had taken.

The proposal had a difficult timing. The SEC had filed SEC v. Telegram the previous October over the TON token sale, won an injunction halting the offering in March 2020, and would file SEC v. Ripple in December. Each of those cases pressed the opposite view: that the Howey investment-contract test, applied case by case, was the right framework. Peirce updated her proposal as Safe Harbor 2.0 on April 13, 2021, adding semi-annual disclosure updates and an exit-report requirement. “Now, as a new Chairman is coming into the SEC with a new agenda,” she wrote, “is the perfect time for the Commission to consider afresh how our rules can be modified to accommodate this new technology in a responsible manner.”

The new Chairman was Gary Gensler. The Commission never put Rule 195 on its rulemaking agenda. The proposal became, for the next five years, the cleanest counterfactual that industry counsel could point to.

Five Years of Dissent

Gary Gensler took the Chair on April 17, 2021, four days after Peirce released Safe Harbor 2.0. The two arrived at the crypto question with opposite priors. Gensler, in his first major crypto speech at the Aspen Security Forum that August, said the bluntest version of his view: “Right now, we just don’t have enough investor protection in crypto. Frankly, at this time, it’s more like the Wild West. This asset class is rife with fraud, scams, and abuse in certain applications.” He told the audience that many tokens “may be unregistered securities” and that the Commission would use the Howey test plus enforcement to bring them in. Peirce had, two years earlier, used a different image for the same regulatory landscape.

The two postures collided steadily. On March 31, 2022, the SEC’s accounting staff issued Staff Accounting Bulletin 121, which required public companies that custodied crypto for users to record a corresponding liability on their balance sheet at fair value. Banks would, in practical effect, find crypto custody capital-prohibitive. Peirce dissented in a statement titled “Response to Staff Accounting Bulletin No. 121.” “SAB 121 is yet another manifestation of the Securities and Exchange Commission’s scattershot and inefficient approach to crypto,” she wrote. The bulletin had circumvented the formal rulemaking process and bound regulated entities through staff interpretation. Congress passed a resolution to overturn it in May 2024 that President Biden vetoed; SEC staff finally rescinded it in January 2025 under the new administration.

The next flashpoint was Wahi. In July 2022, the SEC charged a former Coinbase product manager and his associates with insider trading on the Coinbase exchange. To support the charge, the complaint identified nine of the traded tokens as securities. None of those tokens’ issuers had been registered, charged, or notified that their tokens were so categorized. The Commission had labeled nine projects securities by litigation footnote.

Peirce’s clearest articulation of the worldview difference came a month before, in a June 2022 speech titled “On the Spot.” “Enforcement actions short-cut the regulatory process,” she said. “A preferable approach would have been, once we identified crypto lending as implicating the securities laws, to commence a rulemaking or invite crypto lenders and other members of the public to come in and discuss the appropriate path forward.” She returned to this argument across the next three years, almost verbatim, against every major enforcement action.

Then FTX collapsed. The November 2022 implosion of Sam Bankman-Fried’s exchange was, by any reading, the strongest argument for the Gensler position. Yet Peirce, two months later, in a speech at Duke titled “Outdated,” held the same line: the framework the agency had used pre-FTX was the wrong one, and FTX did not retroactively make enforcement-only the right answer. She framed the SEC’s response as the same misdiagnosis with more urgency. The institutional momentum after FTX was the opposite. Through 2023, the Commission filed enforcement after enforcement against U.S. crypto businesses, with Peirce dissenting in public each time.

The Kraken settlement on February 9, 2023 produced the dissent that became her best-known. Kraken shut down its U.S. retail crypto staking service and paid a $30 million penalty for offering it without registration. Peirce’s statement, titled “Kraken Down,” was the sharpest of her tenure: “A paternalistic and lazy regulator settles on a solution like the one in this settlement: do not initiate a public process to develop a workable registration process that provides valuable information to investors, just shut it down.” She added: “Using enforcement actions to tell people what the law is in an emerging industry is not an efficient or fair way of regulating.” She posted the statement to her X account the same day.

Two months later, in April 2023, the Commission proposed amendments redefining “exchange” under the Exchange Act in language broad enough to sweep DeFi liquidity protocols into the registration regime. Peirce’s dissent was titled “Rendering Innovation Kaput.” Then, on consecutive days in June 2023, the SEC filed SEC v. Binance and SEC v. Coinbase, naming the two largest crypto exchanges serving U.S. users in the same week, on overlapping unregistered-securities theories. The double filing was treated by industry as the climax of regulation-by-enforcement.

The dissents accumulated. The Wahi complaint, the LBRY summary-judgment order, the Kraken settlement, the Exchange definition proposal, the Coinbase and Binance suits, and the Commission’s February 2024 dealer-rule expansion (which the rule’s text could plausibly extend to DeFi automated market makers) all proceeded over her objections. When LBRY announced it would not appeal and would wind down, Peirce filed a follow-on dissent in October 2023 titled “Overdue”: “This case illustrates the arbitrariness and real-life consequences of the Commission’s misguided enforcement-driven approach to crypto.” Her audience was not the room. The dissents read like memoranda to a future Commission that might want to know what the dissenter had said.

That posture had a cost. Peirce was, through 2022 and 2023, the only crypto-supportive voice on the Commission with a vote. The industry had no other regulator to appeal to inside the agency. Compliance counsel were left reading her dissents in lieu of guidance. Crypto firms that wanted to register, she argued at one point, had no usable path. The industry’s frustration with that gap was the political opening that eventually closed in November 2024.

Vindicated by a Court

The clearest substantive win of Peirce’s tenure came from a court. In August 2023, the D.C. Circuit ruled that the SEC’s denial of Grayscale’s spot-bitcoin ETP conversion was arbitrary and capricious, having approved bitcoin futures ETPs without adequately explaining why a spot product was different. Five months later, on January 10, 2024, the Commission approved 11 spot bitcoin ETPs in an omnibus order. Peirce voted yes.

Her concurring statement, titled “Out, Damned Spot! Out, I Say!”, was the I-told-you-so version of the Winklevoss dissent. “We squandered a decade of opportunities to do our job,” she wrote. “If we had applied the standard we use for other commodity-based ETPs, we could have approved these products years ago, but we refused to do so until a court called our bluff.” She added: “I am not celebrating bitcoin or bitcoin-related products; what one regulator thinks about bitcoin is irrelevant. I am celebrating the right of American investors to express their thoughts on bitcoin by buying and selling spot bitcoin ETPs.”

The ETF approval, the spot-ether ETP approval that followed four months later, and the Grayscale ruling that forced the underlying turn were the trio that closed the Clayton-Gensler era of categorical resistance to spot crypto products. Peirce had argued the position for six years. She did not get to claim the victory; she got to write the statement.

The Task Force

The political reset came in November 2024. President Trump won the election; Brian Armstrong, the chief executive of Coinbase, publicly endorsed Peirce for SEC chair the next day.

The job ultimately went to Paul Atkins, the same Atkins Peirce had served as counsel during his 2002-2008 commissioner tenure. Gensler announced his departure effective January 20, 2025; Acting Chairman Mark Uyeda, on January 21, announced a Crypto Task Force and named Peirce its leader. For the first time in seven years, Peirce was holding the pen rather than writing the dissent.

Her opening statement on February 4, 2025, titled “The Journey Begins,” framed the work in the same road-trip imagery she had used since the Safe Harbor speech. “On that last trip,” she wrote, “the Commission refused to use regulatory tools at its disposal and incessantly slammed on the enforcement brakes as it lurched along a meandering route with a destination not discernible to anyone. It took us a long time to get into this mess, and it is going to take us some time to get out of it.”

The next sixteen months delivered, by SEC standards, an unusual cadence of output. The Commission dismissed its civil case against Coinbase on February 27, 2025. Peirce’s accompanying statement called the earlier campaign “a large-scale regulation-by-enforcement initiative” that “harmed the American public, adversely affected the industry, and impeded the ability of the Commission’s skilled and dedicated professional staff to use their expertise as it was intended to be used.” Cases against Binance, Kraken, and others were unwound through the year. The Task Force issued staff statements clarifying that several categories of crypto activity, including memecoins and certain staking activities, sat outside the Commission’s securities jurisdiction. By December, the Division of Trading and Markets had issued a no-action letter clearing the Depository Trust Company to develop securities tokenization services.

The Atkins-era SEC also resumed a tokenization-focused rulemaking conversation under the banner of Project Crypto, with Peirce’s task force coordinating the substantive output.

What She Leaves

The Peirce that left this week was, by any honest accounting, more vindicated than thwarted. Spot bitcoin and ether ETPs trade. The enforcement actions she protested have been dropped or settled. The Task Force she chairs has become the locus of the agency’s crypto rulemaking, the direction she had argued for in 2020. Several proposals she has championed, including a federal innovation exemption for tokenized equities, are in active consideration.

Not all of it landed. The Token Safe Harbor itself, the proposal that made her a household name in the industry, was never adopted as a rule. The version of decentralization-graduation it described would have been one path through the Howey thicket; the path the Commission is now charting under Atkins relies on different mechanisms, including no-action relief and staff guidance. Some of her sharpest dissents, particularly on the SEC’s pay-to-play rule for investment advisers and on the Consolidated Audit Trail market-surveillance program, remain unresolved.

The most immediate consequence of her departure is institutional. With Peirce gone and Commissioner Caroline Crenshaw having left in January 2026, the Commission is left with two sitting members. The agency can operate at that number, but a two-person Commission has no modern precedent and would deadlock on contested rulemakings. The crypto-policy direction Peirce helped set in 2025 will be carried, in the short term, by an even thinner bench.

In her farewell, Peirce did not give the speech over to crypto. She catalogued unfinished work across the SEC’s full portfolio, from climate disclosure to the Foreign Corrupt Practices Act, and closed with a call for bipartisan ground on what she called the “boring basics.” But she did single out the past eighteen months of crypto work as an example of the Commission “tie[ing] our crypto regulatory and enforcement activities to the statutes we administer.” It is the line she had been arguing since 2018. The retrospective version reads less like a thesis than a verdict.

She is moving to the beach.
Bitcoin’s ‘Higher Floor’ Thesis Puts $40K Bottom in Play: Galaxy Research

0

New research from Galaxy Digital suggests that Bitcoin’s cycle low could form at higher price levels than previous bear markets due to the absence of speculation. The analysis places the potential bottom between $62,000 and the network’s realized price at $53,600.

Galaxy head of research Alex Thorn analyzed every Bitcoin cycle top and bottom and noted that the four-year cycle continues to track closely with BTC’s historical timing. The peak-to-trough declines have steadily narrowed across market cycles, falling from 85% and 84% in earlier periods to 77% in 2022 and 51% in 2026. 

Bitcoin’s four-year cycle peak-trough analysis. Source: Galaxy Research/X

Thorn argued that Bitcoin’s October 2025 top differed from previous cycle peaks. Only two of eleven traditional topping indicators flashed, while the widely followed Pi Cycle Top indicator failed to trigger for the first time. Bitcoin’s MVRV ratio, which compares market value to realized value, peaked at 2.29, compared with 2.93 to 5.91 in prior cycles. The analyst said, 

“The key insight: a calm top RAISES the floor. Because October’s top was so muted, the network’s cost basis sits at 43.7% of ATH, vs ~34%, 21%, and 17% in prior cycles.”

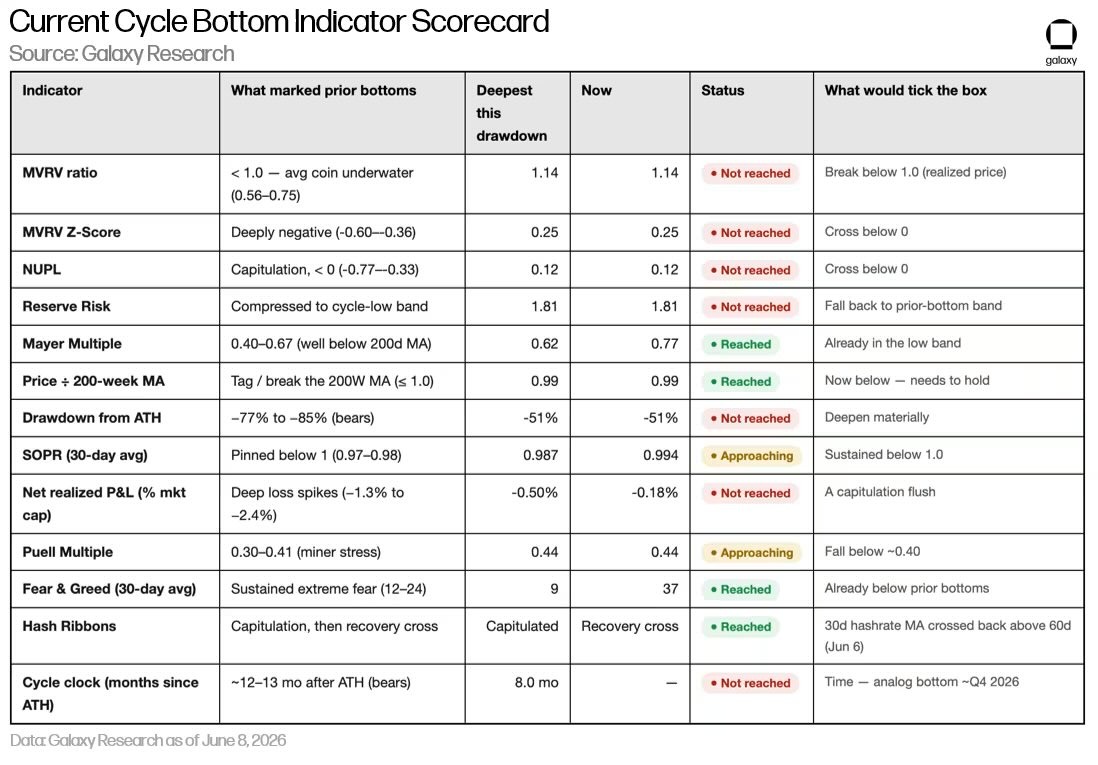
The report also found that several key bottoming signals are still absent. Only four of thirteen indicators have triggered so far, with most of the stronger signals yet to appear.

BTC cycle bottom indicator list. Source: Galaxy Research/X

Historical timing also points to the possibility of a bottom ahead. The previous cycle bottoms formed roughly 12 to 13 months after the market peak, while the current drawdown is about eight months old.

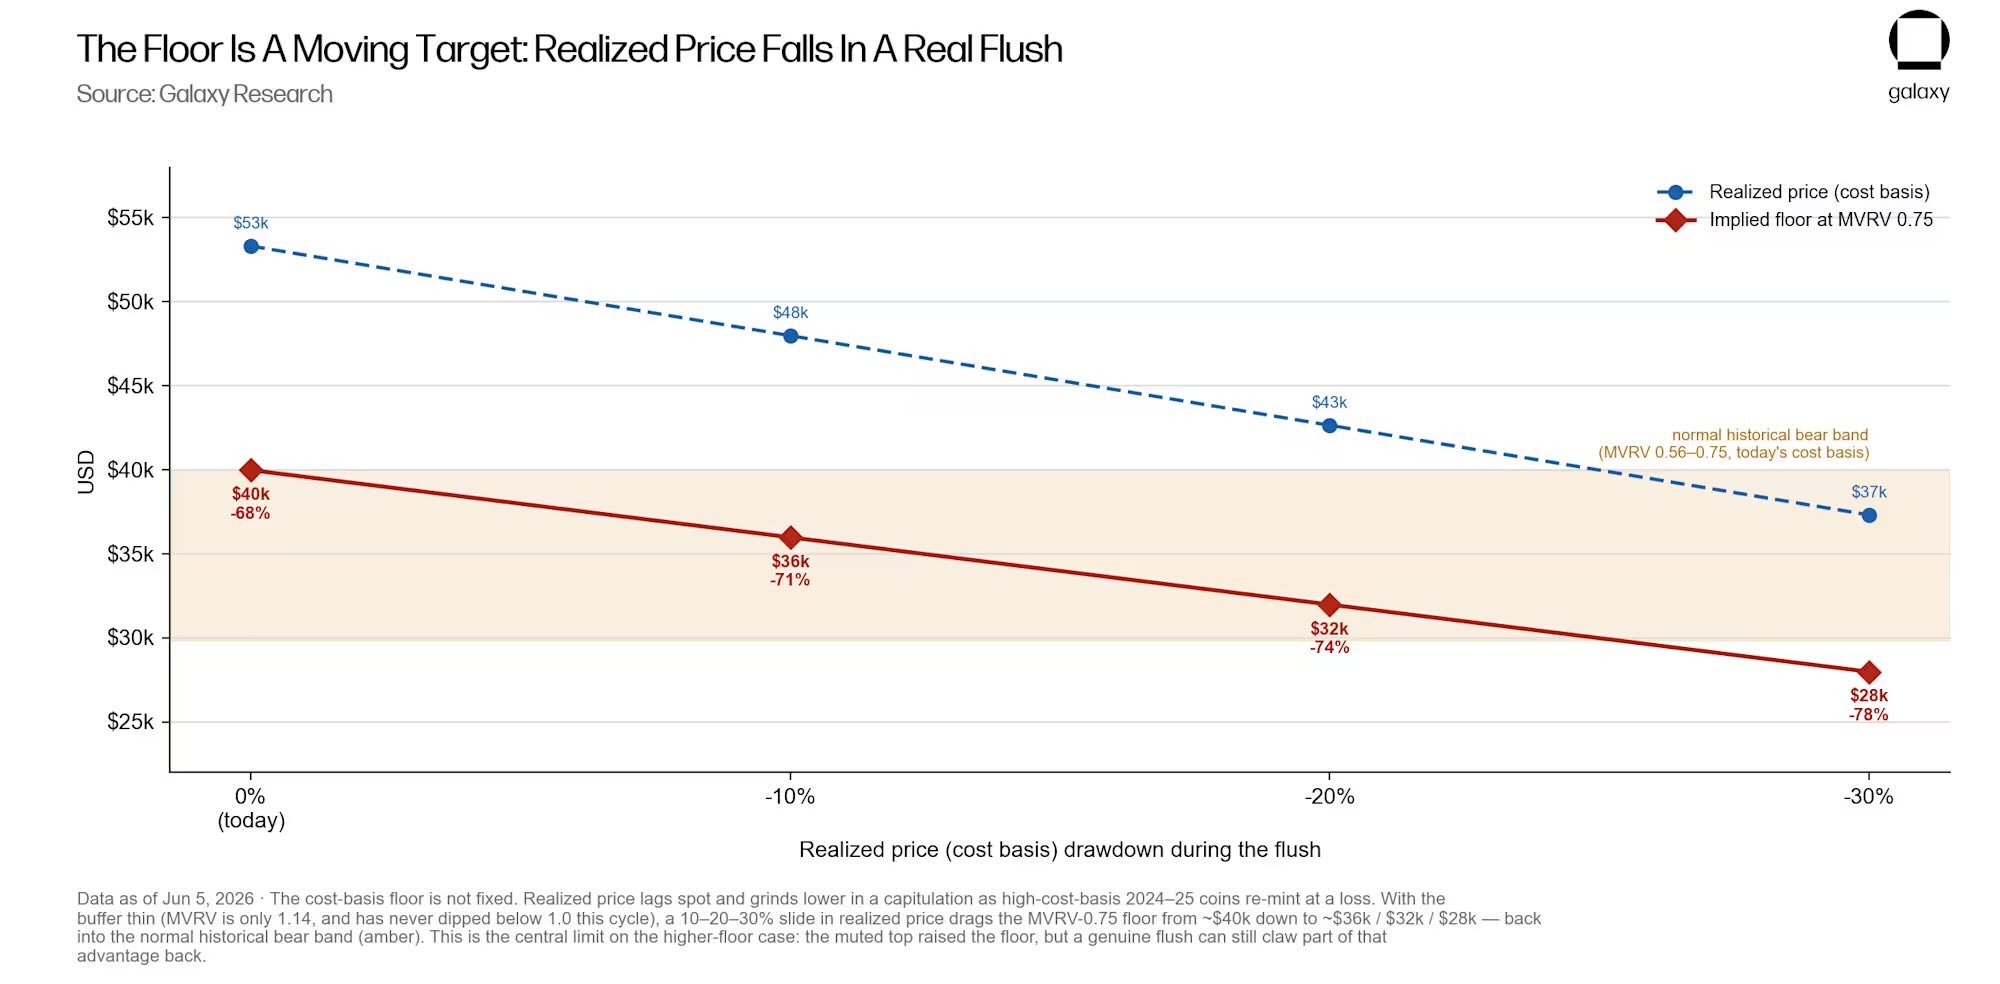
Thorn noted that, based on the current cost basis of $53,600, Galaxy estimates a base-case bottom range of $40,000 to $46,000. A deeper “washout scenario” points to $30,000-$37,000, while a shallower decline could hold near $51,000-$54,000. Despite the scenarios, Thorn also warns, 

“The catch: the floor can move. cost basis is reflexive. in a real panic, coins change hands at a loss and drag the average down. A 10-30% cost basis decline pulls the implied floor from ~$40k back toward $28k.”

Bitcoin bottom range based on realized price analysis. Source: Galaxy Research

Related: Big Tech crash, oil volatility rattles markets: Will Bitcoin hold above $60K?

Bitcoin demand still trends lower: CryptoQuant

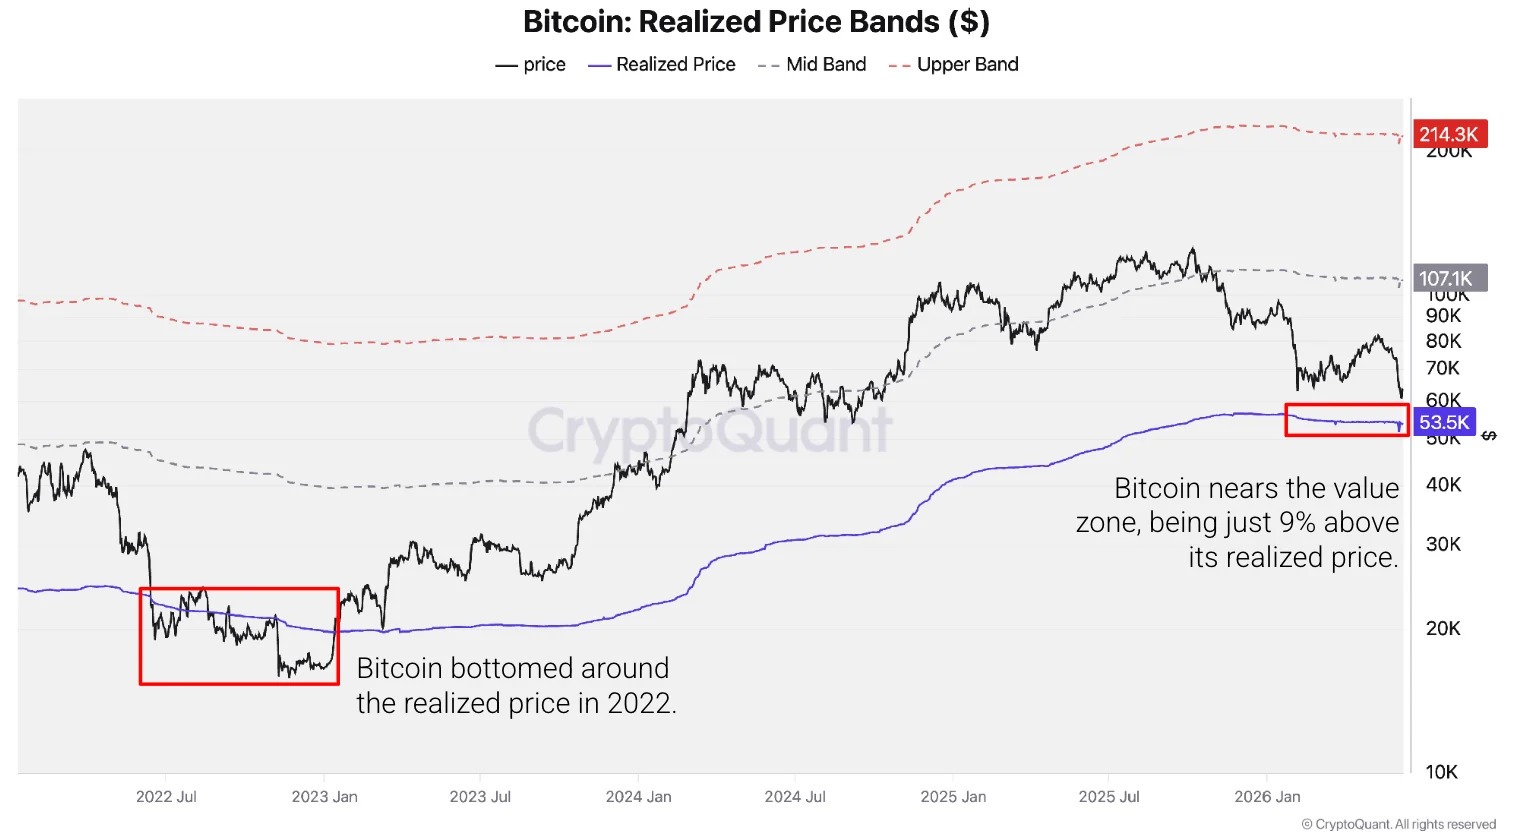
Onchain analysis from CryptoQuant currently places Bitcoin inside a valuation zone historically associated with major bear-market lows. BTC recently traded near $59,000, leaving it roughly 9% above its realized price of $53,600. 

Bitcoin value zone based on realized price bands. Source: CryptoQuant

Past cycle bottoms, including the November 2022 FTX-driven sell-off, formed at or slightly below the realized price, suggesting the bottom range may again fall below the cost basis of $53,600 and overlap with Galaxy’s base projection between $46,000 and $40,000. 

Demand data paints a more cautious picture. CryptoQuant reported a combined weekly decline of 652,000 BTC across speculative futures demand and apparent spot demand, marking the sharpest contraction since January 2022. The firm’s one-year demand gauge has also turned negative, signaling fewer BTC buyers than a year ago.

Related: Bitcoin surfs SpaceX IPO at $64K as trader warns key BTC price support may crumble

LG Electronics is taking advertisements onchain. Arbitrum helped

0

Blockchain is no longer just a story of Wall Street banks and brokers leveraging the technology to optimize finance. Now, corporates are embracing distributed ledger to streamline business operations.

LG Electronics, the South Korean consumer electronics giant spanning TVs, laptops, and home appliances, with annual global revenue of over $60 billion, is building a blockchain-based advertising network and has chosen Arbitrum to help build it out.

LG told Fortune it has developed its own layer-2 blockchain network in collaboration with Arbitrum, a layer 2 protocol that enables low-cost, high-speed transactions on Ethereum.

LG’s move is part of a broader trend of corporations seeing operational potential in blockchain technology. Walmart has used the technology to transform food safety and reduce the time needed to trace a product through its supply chain to just 2.2 seconds, down from over six days. IBM has built blockchain-based supply chain solutions, while Microsoft has integrated blockchain into its Azure cloud platform for enterprise applications.

SpaceX’s crypto-traded IPO was sharply falling. It now points upward to a $2.4 trillion valuation

0

Blockchain-based prediction markets have recently emerged as the go-to-place for investors to bet on the SpaceX IPO, offering a decentralized alternative to traditional pre-IPO markets. Unlike private equity deals that require accreditation and high minimums, these onchain markets are accessible to retail investors with minimal capital, creating 24/7 price discovery on IPO odds.

At Wednesday’s level near $157, SPCX implied only a roughly 16% premium to the $135 IPO price, down from about 60% when the contract briefly traded near $216 in May. At $183, the implied premium is back near 36%.

Other shadow markets are now pointing the same way. Bloomberg reported Friday that IG International derivatives implied a SpaceX valuation of about $2.4 trillion, more than 35% above the $1.77 trillion valuation set by the IPO price.

Elsewhere, Polymarket traders put 70% odds on SpaceX closing its first trading day above $2 trillion.

The reversal comes as pre-IPO SPCX has shown caution in the market, falling by about 30% over the past few weeks. It suggested traders still expected SpaceX to trade above the offer price, but not at the explosive premium implied by the bookbuild. And Friday’s bounce now says that discount is closing.