Home Blog Page 177

Fable’s Shutdown Hands Crypto Its Case for Decentralized AI

0

Anthropic’s most powerful public model came with guardrails users called too broad — then the US government switched it off entirely. Crypto’s builders say that is exactly why AI should run on networks no company or state controls, and traders have started to bid up the tokens betting on it.

Crypto investors and builders say the censorship of Anthropic’s Fable 5 proves their long-running argument: that AI should run on decentralized networks no company or government can switch off.

The model shipped with guardrails so broad that many users complained, by Anthropic’s own account, and would quietly degrade its answers when asked to help train other AI. Then on June 12 the US government forced Anthropic to disable Fable 5 and its more powerful sibling Mythos 5 for every user, after an export control directive barred access by any foreign national, the company said in a statement. The order covered foreign nationals inside and outside the US, including Anthropic’s own employees, and left other models such as Claude Opus 4.8 untouched.

For a corner of crypto that has spent years building AI on blockchains, the takedown was a live demonstration of its pitch.

“Their access to AI is at will,” said Jake Brukhman, founder and chief executive of CoinFund, one of the earliest US crypto investment firms, on a Defiant panel. “It’s at the pleasure of big private companies like Anthropic and OpenAI … and the whim of the government.” When the order hit one company, he noted, the effect was a near-global shutdown.

The episode sharpens a question that has trailed the AI boom: whether the most capable models should sit with a handful of US firms and the government that can rein them in. Crypto’s answer is that decentralized networks can keep AI running, private and beyond any single authority. The harder question, which even its own investors press, is whether those systems can match the centralized labs at all.

Decentralized AI Tokens Outrun Bitcoin Since the Shutdown

Traders moved first. The broad crypto AI sector is worth about $22 billion, according to CoinGecko, a fraction of the roughly $965 billion that recent funding rounds have ascribed to Anthropic alone. Within that sector, the tokens most closely tied to decentralized AI jumped after the June 12 order, even as bitcoin slipped 0.8% over the past week.

Bittensor’s TAO, the largest pure-play decentralized AI token, led the move. It rose as much as 30% within 12 hours of the shutdown and roughly 39% over the following days, touching a three-week high near $283. It has since pared much of that to about $236, up 11% over the week, CoinGecko data show.

Smaller compute and agent tokens ran further: Akash’s AKT added 18% and decentralized-agent project Morpheus’s MOR gained 16% over the same stretch, against gains of 1.7% in ether and 4.3% in SOL.

The rally is partly ideological. Grayscale, the asset manager, told clients the shutdown demonstrated “centralized control over advanced AI technologies” and pointed to Bittensor as an open, permissionless alternative. Erik Voorhees, founder of the privacy-focused AI app Venice, tied the order to his product directly, posting “There’s a reason we built Venice.”

The sector remains small and concentrated. The largest token in CoinGecko’s AI category, Chainlink, is an oracle network rather than a decentralized AI project; the recognizable pure-plays are NEAR and Bittensor, followed by compute and agent networks an order of magnitude smaller.

Project Token Market cap Since shutdown (7d)
NEAR Protocol NEAR ~$2.9B +8%
Bittensor TAO ~$2.3B +11%
Render RENDER ~$0.9B +4%
Venice VVV ~$0.7B +2%
Artificial Superintelligence Alliance FET ~$0.4B +1%
Akash Network AKT ~$0.2B +18%
Morpheus MOR ~$0.02B +16%

Source: CoinGecko, as of June 18. Figures move quickly; refresh at filing.

Beyond the liquid tokens sit the projects trying to do the hardest part — training models across distributed machines — most of them still private. Brukhman pointed to Pluralis, Gensyn, Bagel and Prime Intellect among the startups CoinFund and others are backing, alongside research efforts such as Nous and Macrocosmos.

Why Crypto Calls It Censorship

The case rests on more than one government order. Anthropic had kept Mythos out of general release over concerns it could boost hacking, limiting it to a select group of companies under a cybersecurity program called Project Glasswing. It released Fable 5 publicly with safeguards meant to block the underlying model’s most sensitive cyber uses — safeguards “so strong that many users have complained that they are overly broad,” the company acknowledged. Fable also degrades its own performance on tasks that look like training a rival model.

Illia Polosukhin, co-founder of NEAR Protocol and a co-author of “Attention Is All You Need,” the 2017 paper that introduced the architecture behind modern large language models, said the layered restrictions amount to controlling what people can ask rather than what they do. Blocking a model is “trying to police the thought,” he said in an interview on The Defiant’s podcast.

The government order, in his view, set a wider precedent.

It is “a very bad precedent for internet overall, because effectively US government shown they can ban any US-made internet product on the whim,” Polosukhin said. Brukhman made the structural version of the same point: “By default, when AI is being developed by centralized companies, then they’re developed in this … corporate form that is highly susceptible to government pressure.”

The Case for ‘Freedom Technology’

The pitch is that decentralization removes the off switch. Polosukhin wants inference — the step where a trained model answers a query — to run across a permissionless network of machines, encrypted end to end. NEAR uses secure enclaves, hardware he says can verify code ran correctly without exposing the data, at a few percent overhead rather than the heavy cost of replicating work across a blockchain. Run that way, he argued, AI cannot easily be censored or surveilled. “I think of privacy as effectively the freedom technology,” he said.

Brukhman framed decentralized AI as a deliberate counterweight.

“One of the reasons that I am in decentralized AI is to create a counterbalance … so that we can still have access to AI,” he said. He argued the demand is already there, pointing to open-weight models from Chinese labs that sit within a few percentage points of the frontier on public benchmarks. “There is a ton of demand for global permissionless AI, whether the State Department likes that or not,” he said.

The thesis is starting to show revenue at NEAR. NEAR Intents, the protocol’s cross-chain settlement layer, held about $92 million in assets and generated roughly $2.4 million in fees over the prior 30 days, DefiLlama data show. Polosukhin tied NEAR’s run to structural changes — full dilution five years after launch, an inflation cut in an October governance vote, and a fee switch turned on for NEAR Intents in February — rather than to the AI debate itself.

Can It Actually Compete?

The investors who build at the AI-crypto seam are also its sharpest skeptics, and their doubt is not about the principle but the product.

“Most decentralized AI hasn’t really been of the quality of the centralized alternative,” said Jesus Rodriguez, founder of crypto data firm Sentora and author of the AI newsletter The Sequence, who has built and sold AI companies. “It’s not a question of the value proposition conceptually, it’s a question of the product.”

As the leading labs push pre-training, post-training and newer techniques, “the gap with decentralized models has widened and not shortened,” he said, calling decentralized AI an idea that “has been around forever and it has never found product market fit.”

Haseeb Qureshi, managing partner at crypto venture firm Dragonfly, said the economics do not yet support training or running frontier models on distributed networks. Coordinating scattered machines over the public internet carries a real bandwidth cost, he argued, and the labs control vast, expensive datasets that a “decentralized trove of people” cannot match.

The scale gap shows in the numbers: the entire crypto AI sector is worth roughly 2% of Anthropic’s private valuation. Qureshi’s own view is that crypto’s contribution will be narrower — letting users run existing open-weight models privately and cheaply, as Venice does with models such as DeepSeek, rather than training new ones in a decentralized setting.

“The core value proposition of crypto is not decentralization,” he said. “The end is self-sovereignty and censorship resistance.”

He also warned that the freedom crypto is championing cuts both ways. Cheap, ungated frontier AI would put offensive cyber capability in every hand, including hostile states.

April 2026 set a record for the number of crypto hacking incidents, with about 30 exploits, the most of any month, according to DefiLlama; losses topped $600 million before falling to roughly $68 million in May even as incident counts stayed near the high, security firm CertiK found. Analysts have tied much of this year’s stolen funds to North Korea. “This thing is basically a bazooka,” Qureshi said. “I don’t want North Korea to have Mythos.”

What’s Next

Anthropic said it disagrees with the order, believes it is a misunderstanding, and is negotiating with the administration to restore access. Polosukhin said NEAR will keep adding products to its consumer app, including perpetual-futures trading and a relaunched marketplace for AI agents. The decentralized AI camp is betting the next generation of training methods narrows the gap its own skeptics say keeps widening — and that the tokens that ran on the Fable shutdown hold the bid.
U.S. agencies seek stablecoin customer-ID rules akin to banks in new GENIUS Act rule

0

These standards, according to the rule proposal, “must include reasonable procedures for: (1) verifying the identity of any person seeking to open an account to the extent reasonable and practicable; (2) maintaining records of the information used to verify a person’s identity, including name, address, and other identifying information; and (3) determining whether the person appears on any lists of known or suspected terrorists or terrorist organizations provided to the financial institution by any government agency.”

The Fed opened a 60-day public comment period alongside the other agencies in the joint effort, including the Office of the Comptroller of the Currency, Federal Deposit Insurance Corp., National Credit Union Administration and the Treasury Department’s financial-crimes arm.

In September, the regulators had issued a more preliminary document seeking comments to direct their GENIUS implementation in this and other areas, and the Treasury received 450 comments. This new stage is known as a “notice of proposed rulemaking,” which comes with another comment period and review before the agencies can eventually issue final joint rules and begin enforcing the regulations.

The Treasury’s Financial Crimes Enforcement Network (FinCEN) has pursued its own related rule to apply the GENIUS Act anti-money laundering provisions on issuers.

Malta Weighs Legal Framework for DAOs and DeFi Projects

0

Malta’s financial regulator has issued a discussion paper outlining a potential legal framework for decentralized finance (DeFi), including recognition of decentralized autonomous organizations (DAOs), as European policymakers continue to grapple with how to regulate blockchain-based financial services.

On June 12, the Malta Financial Services Authority (MFSA) opened a public consultation on DeFi under the European Union’s Markets in Crypto-Assets (MiCA) regulation. The paper invites industry feedback through July 10 and proposes a new legal category for so-called “software-based organizations,” which would encompass DAOs and other software-governed DeFi entities.

Rather than treating DAOs as a standalone legal concept, the MFSA suggests recognizing them as a type of software-based organization, separating the legal framework governing the organization itself from the rules governing the underlying protocol and software.

The discussion paper builds on Malta’s long-standing role in the digital asset industry, having introduced one of the region’s first comprehensive crypto regulatory frameworks in 2018. While stressing that fully decentralized services generally fall outside MiCA’s scope, the regulator argues that many DeFi projects retain centralized features that complicate claims of decentralization and raise questions about regulatory accountability.

“MiCA excludes fully decentralised models from its regulatory scope, meaning that projects without intermediaries or central control may not need to comply with MiCA,” the paper states.

The MFSA outlines the scope of the DeFi discussion paper. Source: MFSA

Related: DAOs may need to ditch decentralization to court institutions

EU regulators increasingly turn attention to DeFi

Malta’s discussion paper comes amid a broader push across the European Union to clarify how decentralized finance and decentralized autonomous organizations should be treated under MiCA.

In March, a European Central Bank working paper found that governance and control across four major DeFi protocols remained highly concentrated, suggesting many projects may struggle to qualify as “fully decentralized” and therefore fall outside MiCA’s scope.

The debate continued in May, when the European Commission launched a targeted review of MiCA seeking feedback on issues including stablecoin interest payments, the treatment of DeFi and whether gaps in the framework warrant additional regulation.

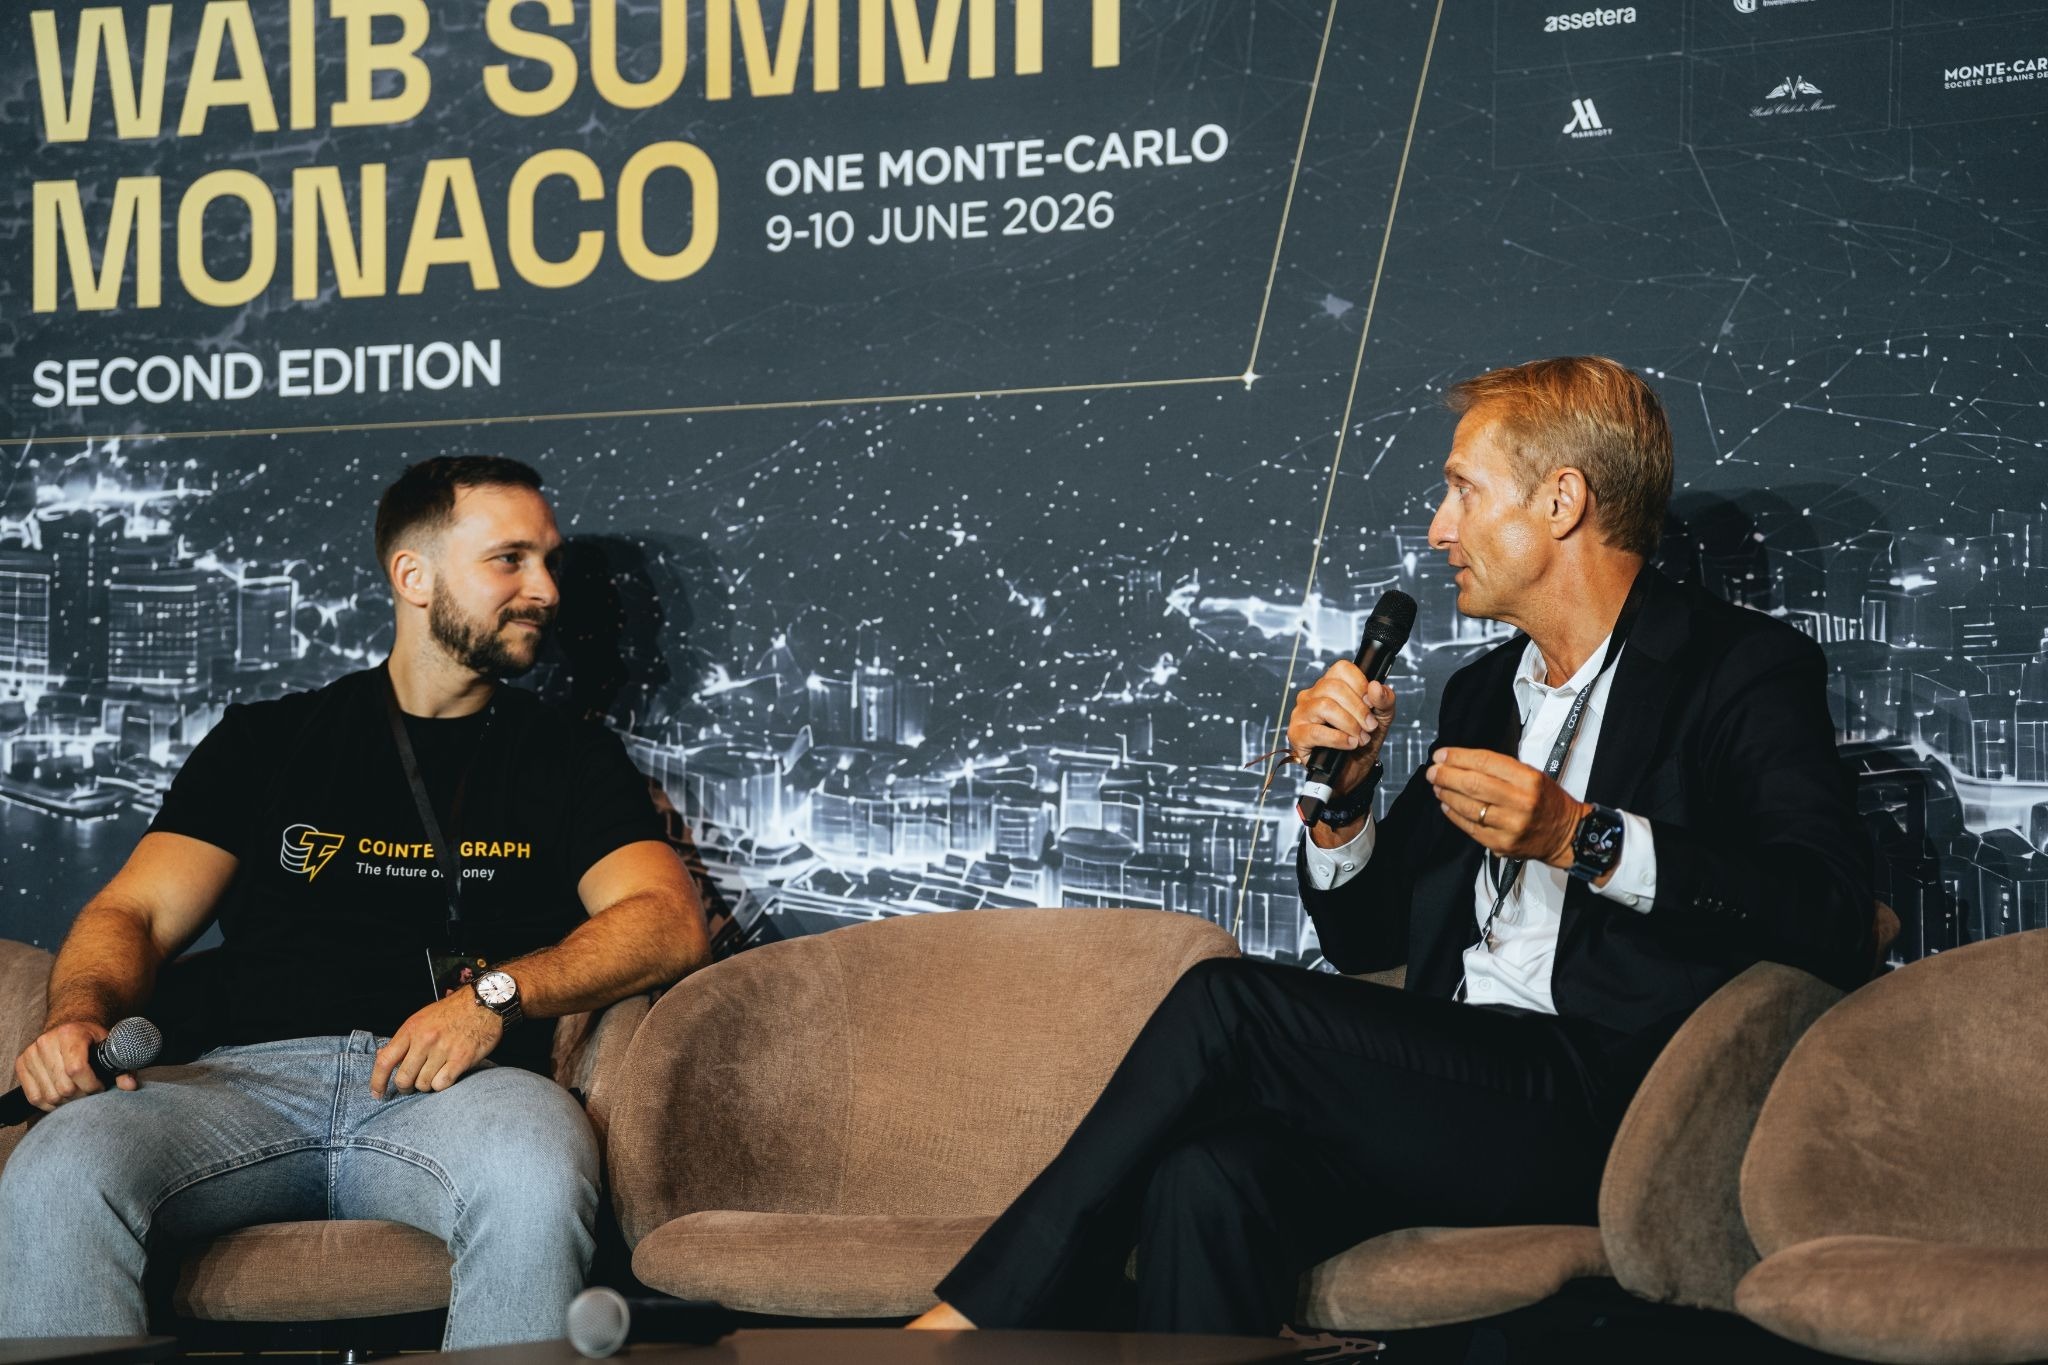
However, not everyone believes a new DeFi rulebook is necessary. Speaking to Cointelegraph at the WAIB Summit Monaco earlier this month, European Commission adviser Peter Kerstens said policymakers should prioritize integrating tokenization into a broader digital asset framework rather than pursuing a second version of MiCA focused on DeFi.

European Commission adviser Peter Kerstens (right) speaks with Cointelegraph’s Zoltan Vardai. Source: WAIB Summit 2026

Related: Crypto firms face July 1 EU cutoff as MiCA grace period ends

Ex-Celsius CEO Mashinsky gets U.S. CFTC ban in final resolution with regulator

0

The punishments of Alexander Mashinsky, the imprisoned former chief of Celsius until its high-profile collapse, continue with a formal banishment from any ability to seek business with the U.S. Commodity Futures Trading Commission or the trading it oversees.

The derivatives regulator didn’t pile any new fines onto Mashinsky, who previously pleaded guilty to accusations he misled the public about the health of his failing crypto firm as it was imploding, but the agency added an expected registration and trading ban, according to a Thursday statement. That’s a minor addition to the 12-year prison sentence imposed in his criminal case, in which he pleaded guilty to fraud, was hit with a $50,000 fine and ordered to return $48 million.

The CFTC’s arrangement, which “permanently restrained, enjoined and prohibited” him from any commodities activity, has been recorded in U.S. District Court for the Southern District of New York, according to the filing, and was approved by a judge on Thursday, the court docket shows.

Ondo Finance Adds 173 Tokenized Stocks and ETFs, Taking Catalog Past 430 Assets Across Three Chains

0

Ondo Finance expanded Ondo Global Markets with 173 new tokenized stocks and ETFs on Tuesday, lifting the platform’s total catalog past 430 assets on Ethereum, Solana, and BNB Chain. The batch brings AI, robotics, quantum, defense tech, critical materials, and data center energy names onchain alongside BlackRock active ETFs and covered call strategies.

Ondo Finance added 173 tokenized stocks and ETFs to Ondo Global Markets on Tuesday, pushing its catalog past 430 assets available across Ethereum, Solana, and BNB Chain.

Ondo Finance’s official X account announced the expansion on June 17. The batch spans some of the most capital-intensive corners of public markets: AI, robotics, quantum computing, defense tech, critical materials, and data center energy. Also included are BlackRock active ETFs and covered call income strategies, products largely inaccessible to crypto-native investors before tokenization. Analytics platform Birdeye added support for all 173 new assets, bringing its tracked Ondo Finance total past 430 as well.

The Platform Behind the Catalog

Ondo Global Markets is a tokenized-securities platform that gives non-US investors onchain access to publicly traded U.S. stocks and ETFs. Each token is backed 1:1 by the underlying security, purchased and held in custody by a U.S.-registered broker-dealer. Tokens track the total return of the underlying position, including dividends, and can be minted or redeemed around the clock on weekdays. The platform crossed $1 billion in total value locked on May 11, the first tokenized-stocks platform to reach that threshold, in under eight months from launch. Cumulative trading volume has surpassed $18 billion.

Ondo Finance holds more than 70% market share among tokenized equity issuers, per RWA.xyz. Its reach extends through integrations with Binance, MetaMask, Blockchain.com, and Ledger hardware wallets. In April, Ondo partnered with Broadridge Financial Solutions to let tokenized-stock holders submit proxy votes on underlying shares, a governance feature rare in the tokenized-asset space. Ondo is also in the process of acquiring Oasis Pro, a U.S. SEC-registered broker-dealer and alternative trading system, to extend its regulated infrastructure toward domestic U.S. access.

Multi-Chain Delivery

The 173 new assets went live across all three supported chains simultaneously. That approach avoids a recurring problem in tokenized-securities rollouts: liquidity concentrating on a single network while users on other chains cannot access the same catalog.

BNB Chain joined Ondo Global Markets in October 2025. Solana launched with over 200 tokenized U.S. equities in early 2026 and has since become the largest network for Ondo-backed assets by count. Ethereum remains the foundation of the platform’s institutional integrations.

The sector spread in this batch reflects where institutional and retail capital has concentrated in public markets. AI infrastructure, defense contractors, robotics, and quantum computing have each drawn sustained inflows over the past year. Critical materials and data center energy extend that theme into the physical infrastructure supporting the technology expansion.

Context in the RWA Arc

Tokenized stocks have emerged as the fastest-growing asset class on Ethereum in 2026, with Ondo and xStocks leading the sector, according to Token Terminal data. The category runs alongside tokenized Treasuries, where Franklin Templeton alone has exceeded $2.5 billion in assets under management.

The expansion follows Ondo’s tokenization of five Franklin Templeton ETFs in March, which brought growth, large-cap, fixed income, equity income, and gold funds onchain. Felix, a protocol built on Hyperliquid, launched access to over 250 Ondo-backed tokenized equities in March, extending the catalog into perpetuals and derivatives infrastructure.

An Ondo executive said in May the company expects the tokenized equity market to reach between $2.5 billion and $3 billion by year-end, per TheStreet. Adding 173 assets in a single batch, across three chains at once, is the most direct expression of that trajectory so far. Ondo has not publicly disclosed how much of the new batch has been minted since the June 17 announcement.

Ethereum Foundation Leses Co-Executive Director Amid Leadership Exodus

0

The Ethereum Foundation has lost another high-ranking contributor, amid increasing scrutiny of the research organization as the network faces ongoing questions about talent retention and governance philosophy.

In a post on X, co-executive director Hsiao-Wei Wang announced that she had stepped down from her role, effective immediately, following a recent sabbatical. Wang wrote that “Ethereum has always been bigger than any role” and indicated that she has not yet decided what she will do next.

Ethereum co-founder Vitalik Buterin commented on Wang’s an X post, acknowledging that she had taken on “the most challenging position in the Ethereum Foundation” alongside Tomasz Stanczak, who also stepped down from his leadership role earlier this year.

Source: Vitalik Buterin

The Ethereum Foundation has logged an estimated 19 layoffs and departures this year, although the loss of senior executives and core contributors has drawn the most attention. The wave of departures comes as the foundation grapples with intensifying competition, ongoing debate over Ethereum’s governance and long-term development strategy, and continued pressure on Ether’s market performance.

Buterin has also pushed back against criticism, particularly claims that the foundation should play a more active role in promoting the network. In May, he said that the foundation “is not the ‘center of Ethereum,’ rather […] ‘one node, with a defined purpose, alongside other nodes.’”

Related: Blockchain researcher defends Ethereum Foundation, says it’s doing ‘exactly’ its job

Decentralization remains Ethereum Foundation’s core mandate

In March, the Ethereum Foundation reaffirmed its role as a steward of the Ethereum ecosystem, unveiling a revised mandate that places even greater emphasis on decentralization.

“Our ultimate goal is for Ethereum to pass the walkaway test: its protocol and core application layers become robust and trustless enough that they would continue to reliably function and evolve even if the Foundation and today’s core developers disappeared tomorrow,” the foundation said.

Source: Ethereum Foundation

That philosophy has also shaped Buterin’s evolving stance on Ethereum layer-2 networks — the independent blockchains built on top of Ethereum to improve scalability and reduce transaction costs. 

Buterin recently stated that the original vision for layer-2s “no longer makes sense,” contending that many have failed to achieve meaningful decentralization and that improvements to the Ethereum mainnet make it a more suitable long-term scaling solution.

Magazine: Ethereum’s roadmap to 10,000 TPS using ZK tech: Dummies’ guide

BlackRock Executive Calls Bitcoin “Too Big To Ignore”, Discusses New Bitcoin Premium Income ETF

0

BlackRock, the world’s largest asset manager with more than $10 trillion under management, has launched a new Bitcoin exchange-traded product designed to generate monthly income for investors — a move the firm’s top ETF executive says is aimed at pulling in a wave of traditional investors who have kept their distance from the asset due to its volatility.

Jay Jacobs, BlackRock’s US Head of Equity ETFs, spoke to CoinTelegraph to discuss the launch of the iShares Bitcoin Premium Income ETF, ticker BITA, which began trading this week. The product represents a departure from conventional Bitcoin exposure by layering a covered-call strategy on top of the firm’s existing iShares Bitcoin Trust, known as IBIT.

“You can think about this as a hybrid strategy for investors,” Jacobs said. “You both have upside opportunity in Bitcoin, as well as the ability to generate income off of Bitcoin.”

BITA holds exposure to Bitcoin through IBIT and sells call options at the money on approximately 25 to 35% of the portfolio. The premium collected from the sale of those options is distributed to holders as income. 

Jacobs said the strategy targets an annual yield of between 15 and 25%, though the actual figure will depend on Bitcoin’s volatility at any given time — a direct application of the Black-Scholes options pricing model, where higher volatility produces higher premiums.

The trade-off is a cap on upside participation. 

If Bitcoin rises 10%in a year and the fund is selling roughly 30%of that upside through options, the fund’s price return would be approximately 7 percent. Add the 15% income component, and total return reaches around 22% — a figure that Jacobs noted would outperform spot Bitcoin in that specific scenario.

In a major Bitcoin rally, the math tilts the other way. If Bitcoin gains 100% in a year, BITA holders would see roughly 70%in price appreciation plus 15% in income, totaling approximately 85%. That underperforms a straight long position, but Jacobs framed that outcome as an accepted trade-off, not a flaw.

Turning bitcoin volatility into a feature

One of the central themes of Jacobs’ conversation was the idea that Bitcoin’s long-criticized volatility is precisely what makes a product like BITA viable. Options prices are a function of volatility, and Bitcoin’s high historical volatility means the premiums available from selling covered calls are substantial.

“You’re monetizing volatility by selling options that are primarily driven by that volatility,” Jacobs said. For investors who have seen Bitcoin’s price swings as a barrier to entry, the product offers a different frame: volatility as a source of income rather than a source of risk.

Jacobs outlined several distinct investor profiles for BITA. Income-oriented investors seeking yield across asset classes represent one group. Long-term Bitcoin holders in a bear or sideways market represent another — people who remain bullish on the asset but want cash flow in the interim. 

A third group, which Jacobs described as more institutional in character, is made up of portfolio managers who have historically required cash-flow-generating assets to justify an allocation.

“Assets that don’t have any cash flows associated with it had always been somewhat difficult, if not impossible, to put in those portfolios — Bitcoin, gold, silver — the cash flow is zero,” Jacobs said. BITA is designed to change that calculus for those investors.

IBIT is the foundation

Jacobs also addressed the broader trajectory of IBIT since its launch roughly two and a half years ago. He said approximately three quarters of IBIT buyers were purchasing an iShares product for the first time, indicating that Bitcoin ETFs have functioned as an on-ramp into the broader ETF ecosystem rather than just a new wrapper for existing investors.

Financial advisors on major bank platforms, who were restricted from accessing digital assets until those platforms opened up access to IBIT, represent a segment Jacobs called out as a source of growing momentum — one that is intersecting with generational wealth transfer as millennials enter higher earning years and accumulate investable assets.

Strategy’s STRC Falls to Record Low, Squeezing a Bitcoin Funding Channel

0

The Stretch preferred fell to about $85 on Thursday, roughly 15% below the $100 it is engineered to hold, extending a record-low close and tightening one of the channels Strategy uses to fund its bitcoin buying.

Strategy’s STRC preferred stock extended its slide to a fresh record low on Thursday, deepening the discount on one of the main channels the largest corporate bitcoin holder uses to fund its purchases.

The Variable Rate Series A Perpetual Stretch Preferred Stock, known as STRC, traded near $85 on Thursday afternoon and touched an intraday low of $84.45, a 52-week low, according to Cboe real-time data around 3:15 p.m. in New York.

The level sits about 15% below the $100 stated amount the stock is designed to hold, and below its $90 IPO price. STRC carries a declared dividend rate of 11.50% a year; at Thursday’s price, that lifts the effective yield to roughly 13.5%. The move extends a record-low close of $89 on Wednesday, a roughly 3% single-day drop on volume of about 5 million shares.

Strategy, the world’s largest corporate holder of bitcoin with about 846,842 BTC, sells STRC near or above its stated amount and routes the proceeds into bitcoin. As the discount grows, that channel raises less cash per share. The record low lands two weeks after Strategy sold bitcoin for the first time since 2022 to fund preferred dividends, and as bitcoin trades around $63,900, below the roughly $75,656 average price Strategy paid for its stack.

How STRC Funds Bitcoin Buys

STRC is a perpetual preferred stock, a class of equity that pays a dividend and ranks ahead of common shares in the payout order. Strategy designed STRC to trade with low volatility near $100 by adjusting its dividend rate each month, marketing it as a higher-yield, lower-volatility way to gain exposure to its bitcoin treasury without holding the common stock.

Strategy raises cash by selling new STRC shares through an at-the-market, or ATM, program. The company launched the program at $4.2 billion in July 2025 alongside what was then its largest-ever IPO, and has since expanded it. In an 8-K covering the week ended June 7, Strategy reported zero STRC ATM sales and about $17.51 billion of remaining STRC issuance capacity. The mechanism depends on the stock holding near or above its stated amount; selling well below $100 raises less cash per share and works against the price-stability design.

STRC has also shrunk as a piece of Strategy’s capital structure as it has fallen. The company told shareholders that as of mid-April STRC carried a $6.4 billion market value with 1.7% 30-day historical volatility; its market value had fallen to about $4.3 billion by Thursday afternoon.

The Dividend Math

The pressure on STRC comes alongside a recurring cash obligation. STRC pays its dividend in cash, and Strategy declared a per-share dividend of about $0.958 for the month ending June 30, reflecting the 11.50% annual rate it held steady effective June 1. The dividend currently pays monthly, but Strategy will move to two scheduled payment dates per month starting June 30, under an amended certificate of designations approved at its June 8 annual meeting.

To meet those obligations, Strategy disclosed on June 1 that it sold 32 bitcoin between May 26 and May 31 at an average price of $77,135, for about $2.5 million, stating the proceeds were expected to fund preferred dividends. The sale was small against a bitcoin position worth more than $50 billion, but it marked the company’s first bitcoin sale since 2022 and the first it disclosed in a standalone filing, a shift for a firm that had framed itself as a net accumulator.

Strategy has also been rebuilding a dedicated cash buffer. The company reported that its USD Reserve, a management-designated pool of liquidity established in December 2025 to support preferred dividends and debt interest, stood at $1.1 billion as of June 14, including unsettled ATM proceeds. That is down from the $2.25 billion Strategy said the reserve held at the start of the year. Over the same week, Strategy bought 1,587 bitcoin for about $100 million using proceeds from common stock sales, separate from the STRC channel.

A Macro Headwind

The decline tracks broad weakness in bitcoin and in Strategy’s other securities. Bitcoin traded around $63,900 on Thursday, down about 1% on the day. The common stock, MSTR, slid about 5% on Wednesday to roughly $116.50, a steeper fall than bitcoin’s, and trades far below its 52-week high near $457.

The selling followed the Federal Reserve’s June 17 decision, the first chaired by Kevin Warsh, to hold its benchmark rate at 3.50% to 3.75% in a unanimous vote. The accompanying projections turned hawkish: nine of 18 officials now see at least one rate increase in 2026, a reversal from March, and the Fed raised its year-end inflation forecast. Higher-for-longer rates weigh on both bitcoin and the income-oriented buyers STRC targets, who can find competing yield in money-market funds and Treasuries.

Saylor Defends the Design

A weaker STRC does not by itself break Strategy’s model, and the company and several analysts have pushed back on the most bearish reading. Bitcoin critic Peter Schiff has revived his “death spiral” argument, contending that the structure forces Strategy to choose between supporting STRC’s price and diluting common shareholders. Analysts at Benchmark and TD Cowen have disputed that framing.

Saylor has defended the design, arguing in recent interviews that Strategy’s bitcoin only needs to appreciate at a low single-digit annual rate for its holdings to cover STRC dividends indefinitely without selling common stock, and saying the company aims to buy far more bitcoin than it sells. He has described Strategy as a shock absorber for bitcoin rather than a systemic risk. The company’s leadership has described the variable-rate mechanism as a tool that has helped keep STRC near its stated amount through earlier stretches of bitcoin weakness.

There is also a counter-signal in a competing product. SATA, the preferred stock Strive created to mirror STRC, traded above $99 this week, suggesting the selloff reflects confidence in Strategy specifically rather than a flaw in the instrument’s design alone. By rank, STRC sits senior to Strategy’s STRK and STRD preferreds and to its common stock, but junior to its STRF preferred and to its debt, giving its dividend a defined claim on the balance sheet.

What’s Next

The semi-monthly dividend switch takes effect June 30, a change Strategy has said is meant to smooth STRC’s trading and reduce volatility around ex-dividend dates. Investors will watch whether the stock stabilizes near $100, whether Strategy resumes STRC issuance once it trades closer to par, and whether further bitcoin sales follow to cover distributions. Strategy is expected to file its next weekly capital-markets update in the coming days.

CME Group Sues CFTC Over Crypto Perpetual Futures

0

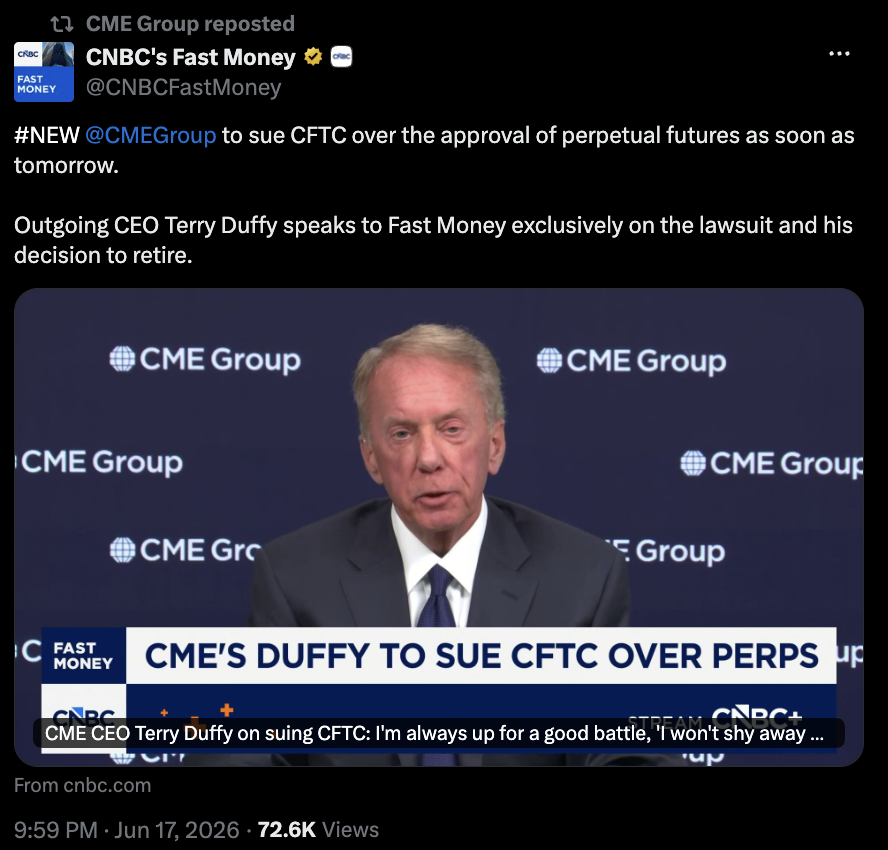
The Chicago Mercantile Exchange (CME) Group said it was taking legal action against the US Commodity Futures Trading Commission (CFTC) over cryptocurrency perpetual futures.

In a Thursday filing in the US District Court for the District of Columbia, CME filed a complaint against the CFTC and its chair Michael Selig over the agency’s regular approvals of perpetual futures tied to crypto. The lawsuit stemmed from a May 29 notice from the CFTC approving perpetual futures contracts tied to the spot price of Bitcoin (BTC) for prediction markets platform Kalshi and issuing a no-action position for similar products on cryptocurrency exchange Coinbase.

According to CME’s filing, the CFTC’s approval of such products went against directives from the US Congress by treating “futures” as “swaps” with expiration dates. The company alleged that the agency was in violation of the Commodity Exchange Act and a court should vacate its actions over perpetual futures, noting that Selig had unilaterally acted without a full panel of five CFTC commissioners.

“With one stroke of his pen, [Selig] overrode Congress’s definition of the term ‘swap’ and circumvented the regulatory regime Congress required for that form of derivative,” said the complaint, adding:

“The CFTC’s failure to evenhandedly, consistently, and correctly apply the CEA risks harming competition and destabilizing derivatives markets.”

Source: PACER

The lawsuit came just one day after CME CEO Terrence Duffy said that the company would be taking legal action against the CFTC. In a Monday CNBC interview, Selig said that perpetual futures contracts “trade very similarly” to others, describing the CFTC’s position as “good for investors” and claiming that the Commodity Exchange Act “does not define the term ‘futures contract.’”

A CFTC spokesperson told Cointelegraph that CME had engaged in “lawfare” against the agency and the administration’s crypto policies, calling the complaint “frivolous.”

Related: ICE, CME press US regulators to ‘rein in’ Hyperliquid energy trading: Report

Kraken also announced the launch of perpetual futures trading for US users through CFTC-regulated platform Bitnomial.

CME CEO Terry Duffy. Source: CNBC Fast Money

Selig acts alone on prediction markets, perpetual futures, CFTC agenda

Confirmed by the US Senate in December 2025, Selig remains the chair and sole commissioner at the CFTC in a leadership panel intended to consist of a bipartisan group of five people. As of Thursday, US President Donald Trump had not announced any nominations to fill the seats, despite urging from many members of Congress to do so.

Magazine: OpenAI files for IPO, SEC scraps 611 rule and Hungary overhauls crypto: Hodlers Digest June 7-13

Cointelegraph is committed to independent, transparent journalism. This news article is produced in accordance with Cointelegraph’s Editorial Policy and aims to provide accurate and timely information. Readers are encouraged to verify information independently.

Ethereum’s Glamsterdam Upgrade Enters Final Devnet Phase With 200M Gas-Limit Target

0

Glamsterdam has reached its final devnet stage, locking in ten EIPs including ePBS and Block-Level Access Lists. The bundle clears the path for a 200 million gas-limit floor and mainnet activation in H2 2026.

Ethereum’s Glamsterdam hard fork reached its final devnet stage Tuesday, locking in the EIP bundle that core developers expect to carry the network through public testnets and on to mainnet activation in the second half of 2026. The release is being framed as the largest protocol change since the Merge.

The upgrade ships ten Ethereum Improvement Proposals tracked under the Glamsterdam Meta EIP-7773, with two headliners doing the structural heavy lifting: EIP-7732, which enshrines Proposer-Builder Separation (ePBS) directly in the protocol, and EIP-7928, which introduces Block-Level Access (BALs) Lists so validators can process unrelated transactions in parallel.

The combination clears the path for a 200 million gas-limit floor, roughly tripling current L1 capacity from the 60 million range and unlocking what proponents say is up to 10,000 TPS-equivalent throughput under realistic workloads.

The Full EIP Bundle

The devnet-0 spec published by the EF’s pandaops team lists the included proposals. Beyond ePBS and BALs, the package contains EIP-7708 (ETH transfers and burns emit a log), EIP-7778 (block gas accounting without refunds), EIP-7843 (a SLOTNUM opcode), EIP-7954 (raising the maximum contract size from roughly 24 KiB to 32 KiB), EIP-7975 (eth/70 partial block receipt lists), EIP-8024 (backward-compatible SWAPN, DUPN and EXCHANGE opcodes), EIP-8037 (state-creation gas-cost increase), and EIP-8159 (eth/71 Block Access List Exchange).

The bundle resolves a debate that ran through several All Core Devs calls this spring over whether ePBS and BALs were too ambitious to ship together. The May 2026 finalization of EIP-8037, which sets a fixed cost per state byte and dedicates a separate gas reservoir for state growth, was the final piece that gave client teams a sustainability ceiling under which a 200M gas limit could be raised without bloating the database past 120 GiB per year.

The Two Headliners

ePBS pulls block-building duties into the consensus layer, separating the validator that proposes a block from the builder that constructs the execution payload. The handoff is currently mediated by off-protocol relays like MEV-Boost, which the ethereum.org documentation notes will become optional rather than required once the protocol natively settles builder payments. The change also widens the data-propagation window from two seconds to roughly nine, which is what unlocks the higher gas limit without forcing validators to rush block validation.

Block-Level Access Lists give every block an upfront map of which accounts and storage slots its transactions will touch, plus the post-execution state values. That lets nodes prefetch data in parallel and process non-overlapping transactions concurrently, rather than replaying them serially. BALs also enable executionless sync, where new nodes can update their state from the access-list digest without replaying the full transaction history. The projected throughput gains were laid out in earlier coverage of the framework when the design first crystallized.

Changes for Users

For end users, the most visible change is EIP-2780, which cuts the intrinsic transaction-gas floor and is projected to make standard ETH transfers between existing accounts up to 71% cheaper. EIP-7708 also makes ETH transfers emit a log, which exchanges and wallets have wanted for years because it removes the need for custom transaction tracing.

For validators, ePBS rewrites the builder-selection process and adds a Payload Timeliness Committee that attests separately to consensus blocks and execution-payload timeliness. Staking pools will need architectural updates to monitor the new flow trustlessly, but the user-facing exit process improves through EIP-8080, which lets standard exits borrow unused capacity in the consolidation queue at a three-for-two rate.

For Layer 2s, the wider propagation window means Ethereum can carry more blobs per block, expanding the data-availability budget that rollups draw from. That continues the Fusaka direction of decoupling rollup data costs from L1 execution congestion, alongside parallel research tracks like the post-quantum key registry laid out earlier this month.

No Mainnet Date

A mainnet target slot is not on the table yet. Client teams use the public testnet phase, which follows successful devnet rotation, to set the activation date. Holesky and Hoodi will fork before mainnet, and only after multi-client stability holds for several epochs across those networks.

Past forks have run two to four months of public-testnet seasoning; on that cadence, mainnet would land between September and December 2026.

The 200 million gas limit is the design target for what Glamsterdam unblocks, not a value the fork itself enforces. Validators set the limit via standard gas-vote signaling, which they currently coordinate around the 60 million range, and would step the limit up only as nodes prove they can handle the larger blocks without degraded propagation.