Home Blog Page 148

Strategy STRC June 30 ex-dividend date and dividend rate reset explained

0

Strategy’s (MSTR) perpetual preferred stock, STRC, is down 3% during Friday’s pre-market and is trading below $73 around 27% below its $100 par value, as investors focus on June 30, a date that brings two important events.

First, June 30 is the ex-dividend date. Investors who own shares before the ex-dividend date will receive the next payment, while buyers on or after June 30 will not. The date also serves as the record date, when Strategy shareholders qualify for the distribution. Eligible investors will receive STRC’s first semi-monthly dividend of $0.48 per share on July 15.

Normally, a stock declines by roughly the amount of its dividend when it begins trading ex-dividend. For STRC, a $0.48 adjustment on a $73 stock represents less than 0.7%, during a time when STRC is falling as much as 2-3% a day. So the ex-dividend date in theory should not be a huge catalyst for further downside in the STRC price.

The bigger catalyst is Strategy’s monthly dividend rate reset. STRC is a perpetual preferred stock, meaning it has no maturity date and pays a dividend that can be reset periodically.

Aave Advances Automated AAVE Buyback Overhaul With Aavenomics 3.0

0

Aave founder Stani Kulechov previewed Aavenomics 3.0 on X Thursday, an automated on-chain buyback mechanism that would route all protocol and GHO revenue to AAVE holders by default, replacing the existing discretionary committee-directed program.

Aave founder Stani Kulechov previewed Aavenomics 3.0 on X Thursday, a tokenomics overhaul that would replace the protocol’s existing discretionary buyback program with an automated, non-discretionary on-chain mechanism funded by all protocol and GHO revenue.

The announcement came as Kulechov responded to a CoinDesk report that Kraken parent Payward was in talks to acquire a 15% equity stake in Aave Group at a $385 million valuation. Kulechov disputed the “70% discount” framing in the report while using the moment to lay out Aave’s existing and planned revenue structure for token holders. Aavenomics 3.0 is the consequential part: an automated buyback system that executes at the protocol level, running continuously unless governance votes to halt it.

Current Buyback Program

Aave’s governance approved the Aavenomics Part One ARFC in early 2025, which gave the Aave Finance Committee a mandate to execute AAVE buybacks from secondary markets at $1 million per week during the initial six-month period. That works out to roughly $50 million annually in discretionary repurchases, coordinated through the Aave Finance Committee and funded from protocol excess revenue.

The mechanism is committee-directed: governance can redirect, pause, or resize the program without a protocol-level change. Aavenomics 3.0, as described by Kulechov, would harden the buyback into the protocol’s economic architecture. Details on the implementation mechanics and governance timeline are expected at Aave’s next quarterly call, per Kulechov’s post.

Revenue Flowing to the Token

The broader context for the buyback upgrade is the Aave Will Win (AWW) framework, which passed governance in April 2026. Under AWW, 100% of revenue from Aave Protocol, from GHO, and from Aave-branded products including Aave App, Aave Pro, and Swaps flows entirely to the Aave DAO treasury. Aave Labs operates solely as a DAO service provider and retains no product revenue.

GHO, Aave’s native stablecoin, has grown to approximately $599 million in circulating supply, per DefiLlama, generating incremental protocol fee income alongside lending revenues. Aave’s all-time protocol fees exceed $2.2 billion, with annualized fees running at roughly $400 million based on the trailing seven-day window.

Aavenomics 3.0 would route that revenue stream through an automated mechanism. Under the design Kulechov described, buybacks would execute without requiring committee approval on each cycle, making repurchases a standing feature of how the protocol distributes economic output to token holders.

The Kraken Equity Context

The CoinDesk report described a deal in which Payward would receive 250,000 AAVE tokens and a 15% common equity stake in Aave Group, with Payward also seeking to syndicate the deal. The $385 million valuation sits below AAVE’s fully diluted token valuation of roughly $1.52 billion at current prices.

Kulechov’s pushback, reported by Unchained, drew a structural distinction between Aave Group as a corporate entity and the AAVE token as the economic vehicle. The equity in Aave Group represents a claim on the corporate service provider, which under AWW receives DAO-funded development budget but retains no protocol or product revenue. The AAVE token captures all of that economic output. Aave Labs holds its own AAVE token allocation, and Kulechov said multiple market participants have discussed purchasing it through long-term partnerships.

Payward’s interest follows its integration of Aave technology through Kraken’s Layer 2 network Tydro. The Defiant reported Thursday on Kulechov’s initial dispute of the deal framing. Kraken has made no public statement on the status of the talks.

AAVE Price

AAVE was trading around $95 Friday morning, up roughly 13.5% over the prior 24 hours and up about 27% on the week, per CoinGecko. The token’s market cap stood at approximately $1.44 billion, against total value locked on Aave of $12.46 billion, per DefiLlama.

Aavenomics 3.0 governance details have not yet been published on the forum; the quarterly call is where Kulechov indicated the full specification would be released.

Ripple CEO stays bullish on bitcoin but says Saylor’s strategy has hurt crypto

0

Ripple CEO Brad Garlinghouse said he remains bullish on bitcoin but that Michael Saylor’s approach to funding bitcoin purchases has damaged the broader crypto market, in a CNBC interview on Friday, as the preferred stock at the center of Strategy’s model fell to a record low.

“Financial engineering does not drive long-term value,” Garlinghouse said, arguing that the lasting value of any digital asset comes from its usefulness. “Team Michael Saylor wasn’t focused on the right stuff and that has hurt the overall market.”

He separated that from his view on the asset itself, saying he is still bullish on bitcoin.

Garlinghouse’s target was the machine Strategy has used to accumulate bitcoin. For about a year, the company has issued preferred shares, a class of stock that pays a fixed dividend, to raise cash for more bitcoin.

Its STRC share carries an 11.5% annual dividend and is engineered to trade near $100. Garlinghouse pointed to STRC trading about 25% below that level as a “damning indictment” of the strategy.

Chainlink Launches Project Pangea With 50+ Banks Across 16 Countries for T+0 FX Settlement

0

Chainlink and a multinational consortium of more than 50 banks across 16 countries launched Project Pangea at Point Zero Forum in Zurich, targeting real-time atomic settlement for the $9.6 trillion-a-day global foreign exchange market via Chainlink rails, Swift messaging, and regulated EUR and KRW stablecoins.

Chainlink and a multinational banking consortium of more than 50 institutions across 16 countries launched Project Pangea at Point Zero Forum in Zurich on Tuesday, targeting T+0 atomic settlement for the $9.6 trillion-a-day global FX market.

The initiative pairs Chainlink’s oracle and interoperability stack with Swift’s ISO 20022 messaging and FairSquareLab’s settlement technology to enable direct Payment-versus-Payment (PvP) swaps of regulated EUR and KRW stablecoins. The formal announcement names three core consortium partners: Qivalis, a euro stablecoin consortium backed by 37 European banks; UniKA (Unified Korea Alliance), the Korean coalition behind Project Pangea, which comprises a steering committee of five entities — Shinhan Bank, JB Bank, Kbank, FairSquareLab, and OBDIA — alongside 10+ participating Korean commercial banks; and FairSquareLab, a Korean onchain FX infrastructure firm.

Three-Layer Stack

Project Pangea’s architecture runs on three layers: a banking layer built on Swift and ISO 20022 messaging; a connectivity layer using Chainlink CCIP and Data Streams for high-speed FX market data; and a settlement layer of AMM smart contracts deployed on Ethereum, Polygon, and a dedicated Pangea L1 blockchain operated by FairSquareLab.

The Pangea L1 functions as neutral territory independent of any single country or participating bank. At the protocol level, oracle price updates execute ahead of every other transaction in each block, ensuring FX swaps settle at current market rates rather than stale quotes.

Through Existing Rails

Banks interact with the system through their existing Swift payment infrastructure. Instructions route through Chainlink’s Runtime Environment (CRE), which translates ISO 20022 messages into onchain settlement actions without requiring institutions to rebuild internal systems. The DTCC chose the same CRE layer for its 24/7 tokenized collateral platform earlier this year, with production targeted for Q4 2026.

Cross-border FX currently requires institutions to convert capital through intermediary currencies before reaching a target denomination, creating settlement delays and intraday liquidity drag. Project Pangea replaces that step with a direct atomic swap at oracle-verified prices.

“Project Pangea upgrades the fragmented foreign exchange model of today with direct, atomic currency swaps using stablecoins,” Fernando Vazquez, President of Capital Markets at Chainlink Labs, said in the announcement. “This is a clear signal that global finance is increasingly moving onchain.”

Project Pangea is Chainlink’s third major institutional announcement in the past two weeks: Chainlink CCIP drew over $1.1 billion in token value in a single week in early June, and the company launched APAC Equities Streams on Monday, putting live pricing for Samsung, Toyota, and Sony on-chain.

SOL Bounced To $72 As Tokenized Stock Trading Surges But Will It Hold?

0

Key takeaways:

  • SOL’s rebound to $72 shows bullish futures and airdrop hopes, but falling TVL and low DEX volumes point to fragile onchain demand.
  • Tokenized stocks spark hype on Solana, yet Pump.fun dependence and Hyperliquid competition threaten sustained SOL momentum.

Solana native token SOL jumped to $72 on Friday, distancing itself from the $64 lows the prior day. Part of traders’ optimism stemmed from the stellar growth of tokenized stock trading, fueled by the AI sector. However, increasing competition in decentralized application networks could limit SOL’s short-term upside.

Solana tokenized stocks 24-hour volumes, USD. Source: Jupiter Aggregator

Tokenized stocks on Solana traded over $113 million in 24 hours, according to Jupiter Aggregator data. However, the relatively thin liquidity in the automated market-making pools raised concerns, especially as multiple issuers compete for similar products. Still, some of those tokens launched only recently, which might explain the low number of holders in most cases.

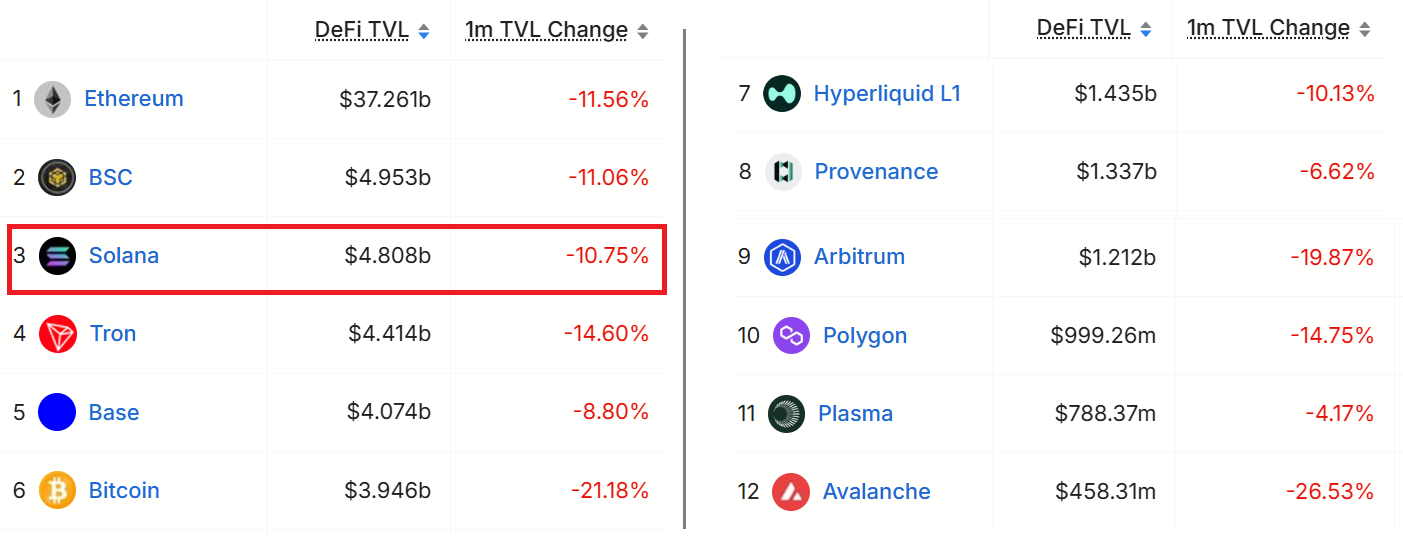
Blockchains ranked by DeFi Total Value Locked (TVL), USD. Source: DefiLlama

The Total Value Locked (TVL) on the Solana network dropped 11% over the past month, while the Ethereum layer-2 Base reduced the gap. Negative highlights on Solana TVL include a 19% decline in Kamino, a 20% trim by Binance Staked SOL, and a 17% decline in Raydium. The tokenization platform xStocks, on the other hand, posted 31% growth in TVL.

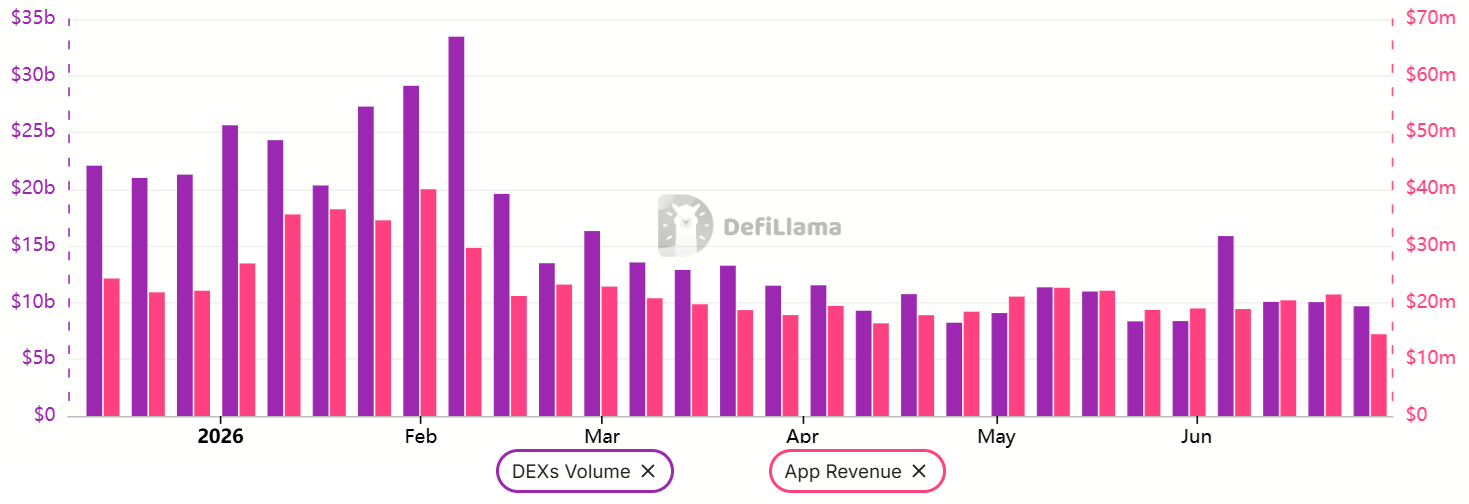
Solana weekly DEX volumes & DApps revenue, USD. Source: DefiLlama

Decentralized exchange (DEX) volumes on Solana fell to $10 billion per week from $30 billion in early February, coinciding with a downtrend in decentralized application (DApp) revenues. Thus, regardless of the successful launch of tokenized tech stocks and equity indexes, demand for SOL on blockchain processing remains subdued.

Solana’s dependence on Pump.fun and increased competition in tokenized launches

More concerningly, 30% of DApp revenue on Solana came from the token launch platform Pump.fun, which depends heavily on memecoin activity. A CoinGecko report revealed that 80% of the 18.7 million tokens launched in less than 48 hours, while 55% of the addresses involved lost up to $1,000 according to Dune data.

SOL perpetual futures annualized funding rate. Source: Laevitas

Demand for bullish leverage on SOL futures increased on Friday, pushing the funding rate to its highest level in June. The current 10% level is far from displaying excessive confidence, as the 6% to 12% range is typically deemed neutral. Still, the 14% gains since the $64 low on Thursday managed to reverse the bearishness marked by negative funding rates.

Related: Solana grabs 95% of tokenized equity as traders debate if SOL bottom is in

Part of SOL investors’ optimism stems from anticipation of airdrops on the network, although the timing of those tokens’ launch remains uncertain. Highlights include OnRe reinsurance with $200 million in TVL, Bulk perpetual DEX with an aggregate open interest of $325 million, and Loopscale lending platform at $79 million in TVL.

It might be premature to claim that SOL is bound to reclaim the $80 mark, last seen on June 1, given increased competition in tokenized stock trading from Hyperliquid and centralized exchanges on competing blockchains. OKX, for instance, formed a strategic partnership with the NYSE parent company using Ethereum-based systems.

EU Lawmakers Back Review of DeFi, Staking and NFT Regulation

0

The European Parliament’s economic affairs committee has urged the European Commission to assess whether crypto lending and borrowing, staking, non-fungible tokens (NFTs) and decentralized finance (DeFi) should be regulated.

The recommendations were part of a report tabled Friday for plenary vote. It also called for promoting tokenization across financial services, encouraging euro-denominated stablecoins and assessing whether additional crypto activities should be regulated under the European Union’s Markets in Crypto-Assets Regulation (MiCA).

Drafted by Belgian Member of the European Parliament Johan Van Overtveldt, the report is an own-initiative resolution by the Committee on Economic and Monetary Affairs (ECON) that outlines recommendations for the Commission on digital asset regulation. 

It will next go before the European Parliament for a vote, expected July 7. If adopted, the resolution would become Parliament’s official position on digital assets policy but would not amend MiCA or create new legal obligations.

The legislative timeline shows the committee’s approval of the report and its referral for a plenary vote. Source: European Parliament

Related: European Parliament throws support behind digital euro

EU warms up to regulated stablecoins

The recommendations also reflect an evolving view of stablecoins among policymakers. Days after former Bank for International Settlements general manager and longtime crypto critic Agustín Carstens softened his stance on stablecoins, the report welcomed euro-denominated stablecoins under MiCA and encouraged their development to support the bloc’s payment sector.

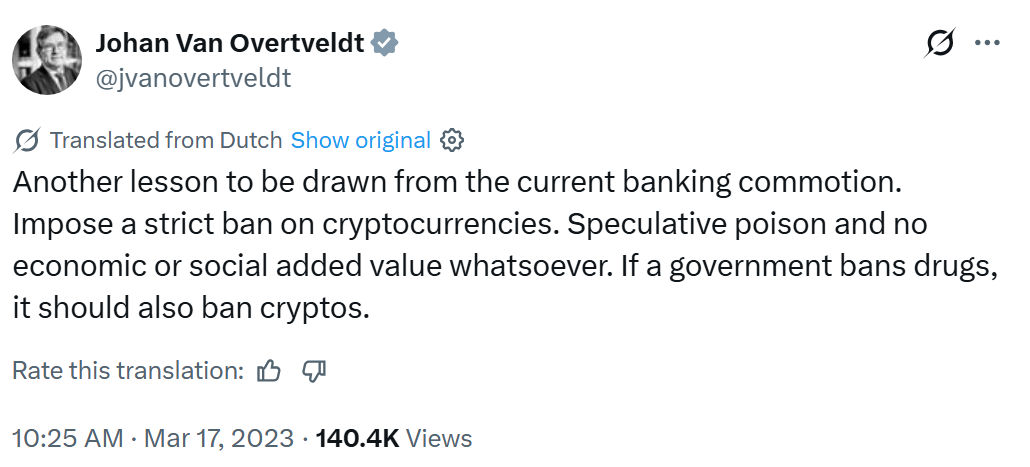
In 2023, Van Overtveldt called for tighter restrictions on cryptocurrencies following the banking turmoil surrounding Silicon Valley Bank, Signature Bank and Silvergate Bank. The crisis was also closely tied to stablecoins, as USDC issuer Circle held roughly $3.3 billion of its reserves at Silicon Valley Bank when it collapsed, briefly causing USDC to lose its dollar peg.

Van Overtveldt likened cryptocurrencies to drugs during the 2023 banking crisis. Source:Johan Van Overtveldt

The report argued that euro-denominated stablecoins could complement tokenized commercial bank deposits and wholesale central bank digital currencies while enabling faster and cheaper cross-border payments. It also said broader adoption could strengthen the competitiveness of EU financial markets and the international role of the euro.

The stance also aligns with ECON’s broader vision for Europe’s digital money ecosystem. On Tuesday, the committee backed legislation for a digital euro, with lawmakers arguing that public and private forms of digital money should coexist rather than compete.

Related: Poland president vetoes MiCA bill again as crypto companies look to license abroad

Lawmakers look beyond MiCA’s current scope 

Van Overtveldt first presented a draft of the report in February before months of negotiations and amendments by ECON members. The earlier version largely focused on MiCA’s existing framework, including stablecoin classifications and legal certainty for multi-issued stablecoins.

The committee-approved report urged consistent application of MiCA across the EU to preserve a level playing field for crypto firms. It also warned member states against introducing national requirements beyond MiCA that could fragment the bloc’s digital asset industry.

The Commission is already reviewing MiCA. In May, the Commission launched a public consultation seeking feedback on whether the framework should be expanded to cover areas including DeFi, staking, lending, NFTs and tokenized financial assets, while also reopening debate over the regulation’s ban on interest-bearing stablecoins.

Meanwhile, MiCA’s transitional period ends July 1, after which crypto asset service providers generally must hold authorization under the regulation to continue operating across the EU.

Magazine: AI is banking the unbanked in Africa… faster than crypto

Majors fall 9% over week as AI stocks lure buyers

0

Dogecoin and Hyperliquid’s HYPE led the week’s losses across crypto, falling near 10%, as money kept flowing toward stocks tied to the artificial-intelligence boom and away from major tokens.

Dogecoin slid 9.6% over seven days to about $0.076 and HYPE lost 9.9%, the steepest falls among the majors. Ether dropped 8.4% to about $1,581 and XRP fell 7.8% to $1.06, while solana and tron held up better, roughly flat on the week at $72 and $0.32.

Bitcoin was the steadier major, down 5.3% to around $60,345 on Saturday after dipping to about $58,800 on Friday and recovering, per CoinDesk data.

“Bitcoin approached $58K at its lows late Thursday and early Friday, but in both cases, aggressive buying quickly pushed it back into the $60K range,” Alex Kuptsikevich, FxPro chief market analyst, told CoinDesk. “This pattern resembles margin position liquidations during downtrend spikes, followed by strong buying on pending orders during the recovery.”

“Given deteriorating sentiment among institutional investors and their ability to quickly divest from cryptocurrencies to stabilise their balance sheets, it is worth preparing for continued pressure and periodic sell-off spikes by leveraged traders,” he added.

ASIC Extends No-Action Relief for Digital Asset Firms

0

The Australian Securities and Investments Commission (ASIC) has given digital asset businesses another three months to apply for licenses required under its updated regulatory guidance.

Australia’s financial regulator said that the temporary protection from enforcement would remain in place until Sept. 30, pushed from the previous June 30 deadline.

The extension applies to businesses seeking an Australian Financial Services (AFS) license, as well as companies that may require market or clearing and settlement authorizations.

ASIC also expanded the no-action relief to cover digital asset businesses operating through authorized representatives or intermediary arrangements with licensed firms, widening the pool of companies eligible for the transition period.

The regulator said it has received about 30 license applications since updating its digital asset guidance in October 2025.

Source: ASIC

Australia’s crypto licensing transition takes shape

ASIC previously introduced the no-action position after updating its Information Sheet 225 (INFO 225) guidance to clarify how existing financial services laws apply to digital assets. The guidance states that many digital asset products are financial products under existing law, meaning many providers require an AFS licence.

That approach rests on ASIC’s view that Australia’s definitions of financial products are broad and technology-neutral. The regulator said its interpretation was recently reinforced by the High Court’s Block Earner ruling, which found that the company’s former crypto yield product was a financial product under the Corporations Act.

Related: Coinbase plans expansion to stock trading in Australia after securing license

The temporary relief is separate from Australia’s Digital Asset Framework, which passed Parliament in April and is scheduled to commence on April 9, 2027.

The law will bring digital asset platforms and tokenized custody platforms under Australia’s financial services licensing regime. ASIC has warned that some firms licensed under the current guidance may need additional authorizations once the new framework takes effect. 

“Many digital asset firms that apply for a licence based on INFO 225 will also need to add DAP and TCP authorisations to their licence once that regime commences,” ASIC said in a May announcement. 

Magazine: AI is banking the unbanked in Africa… faster than crypto

Cointelegraph is committed to independent, transparent journalism. This news article is produced in accordance with Cointelegraph’s Editorial Policy and aims to provide accurate and timely information. Readers are encouraged to verify information independently.

Kraken’s xStocks Opens Bending Spoons IPO Registration to EEA Retail

0

Kraken’s xStocks platform is opening non-binding interest registration for the Bending Spoons IPO to eligible customers in the EEA and select global markets, the tokenized equities infrastructure’s second pre-IPO offering after a troubled SpaceX debut.

Kraken’s xStocks platform is letting eligible customers in the European Economic Area and select global markets submit non-binding interest in the Bending Spoons IPO, the platform’s second pre-IPO tokenized equity offering and its first for a non-US tech company filing for Nasdaq.

Bending Spoons, the Italian software conglomerate behind WeTransfer, Evernote, Vimeo, AOL, and Eventbrite, filed to go public on Nasdaq under the ticker BSP. The company’s portfolio spans more than 50 products reaching around 500 million monthly users, and it reported Q1 2026 revenue of $601 million. Customers who receive an allocation will get BSPx, a 1:1 backed tokenized representation of Bending Spoons equity, delivered to their Kraken portfolio on listing day and tradeable from day one.

Registration Terms

Submitting interest reserves funds without charging them. Allocation outcomes vary: full, partial, or zero, depending on availability and demand. Distribution is pro-rata rather than first-come, first-served, and any funds not allocated are returned automatically. The offering is open to EEA customers and select global markets; US, UK, Canadian, and Australian residents are excluded.

After the IPO

Customers who receive an allocation get BSPx on Bending Spoons’ listing day. The token then trades 24/5 on Kraken and on participating xStocks Alliance platforms and compatible DeFi venues. xStocks, the tokenized equities framework built by Kraken parent Payward, holds assets worth over $100 million on Ethereum and $30 million on BNB Chain across its portfolio. Each BSPx token is backed 1:1 by the underlying share, held in custody by a regulated entity, and portable across participating platforms and DeFi protocols.

The Bending Spoons offering follows xStocks’ SpaceX tokenized equity debut earlier this year. That rollout drew criticism after Bybit, Binance, and Bitget Wallet canceled SpaceX allocations when xStocks failed to deliver shares for a portion of registered users. Kraken’s blog post makes no reference to the SpaceX delivery issues in the context of the Bending Spoons launch.

Interest registration is available in the Kraken mobile app. Bending Spoons has set no public date for when its shares will begin trading on Nasdaq.

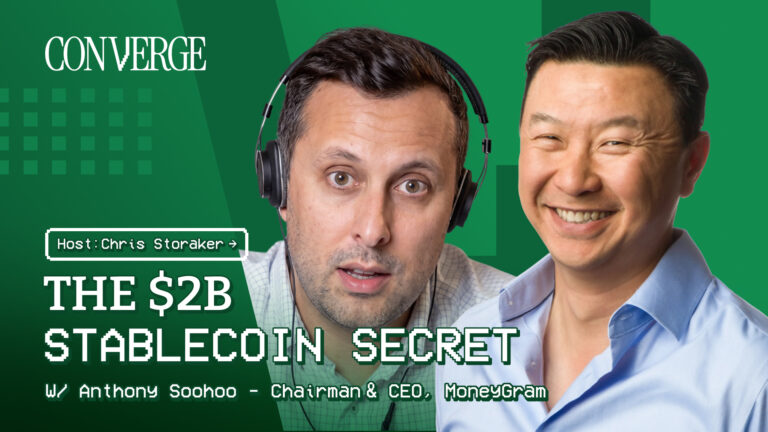
MoneyGram CEO on rolling out MGUSD to its 60 million users, globally

0

MoneyGram has been quietly building on blockchain for over five years. Now, with its own stablecoin (MGUSD), a Kraken partnership, a validator seat on the Tempo network, and $2B+ in stablecoin settlements already running — the pace is accelerating.

🎧 Listen to Interview

💻 Watch Video

MoneyGram does not need an introduction. The company moves money across roughly 200 countries and territories, some 20,000 corridors, and about 500,000 retail locations, and it has done so for more than 80 years. What has changed is where the plumbing runs. Speaking on The Defiant’s Converge podcast, Chairman and CEO Anthony Soohoo described a company “going through a massive refounding,” one being rebuilt from the backend up on stablecoins and blockchain rails.

“We want our employees and our teams to think like founders,” Soohoo said, casting the first 18 months of his tenure as a deliberate rebuild of core infrastructure rather than a front-end facelift. That sequencing, he argued, is why the product cadence is now accelerating. In recent months MoneyGram has integrated with Kraken to give crypto users a cash off-ramp, taken a validator seat on the payments blockchain Tempo, and launched MGUSD, a proprietary US dollar stablecoin announced about two weeks before the interview.

Five Quiet Years

MoneyGram was among the first remittance companies to let people convert digital assets into physical cash, work that began around 2022 with self-custody wallets on Stellar. The Kraken partnership extends that idea: a Kraken user can request a cash pickup in roughly 100 countries and collect local currency at a MoneyGram location.

The throughline, Soohoo said, is treating crypto rails as a base layer rather than a product line. “We see it as a foundation to be able to unlock and build future services and products for our customers,” he said. The company has been working with stablecoins for more than five years.

The Settlement Case

Asked what stablecoins actually fix, Soohoo pointed to three benefits. The first is timing. Stablecoins “settle twenty four seven, including weekends,” he said, which traditional banking rails often cannot.

The second is inventory. MoneyGram holds, in Soohoo’s words, “billions of dollars that are floating around the world” through its network at any moment, and he frames that cash as working inventory. Real-time settlement lets the company turn that inventory faster and provision liquidity closer to demand, rather than pre-funding corridors against a forecast. “You just do it when you see demand,” he said, comparing it to just-in-time supply chains.

The third is cost, which he expects to fall as the rails mature alongside greater liquidity and full traceability. MoneyGram is already trading on a run rate of close to $2 billion, having started earlier this year, and wants to bring on more trading partners to move more of its back office onto stablecoins.

Where Cost Hides

The familiar crypto pitch is that remittances are expensive and stablecoins make them cheap. Soohoo complicated that. Moving value inside MoneyGram’s own network is “just a change on a digital ledger,” he said, and carries little cost. The expense sits at the edges, in conversion: paying a bank to put money in, or paying to handle cash on the way out.

Cash, he stressed, is the most expensive payout method of all. Armored transport, counting, and manual handling make it costly in a way that consumers and even many in the industry overlook. Yet for much of the world, cash remains what recipients want, which is why MoneyGram’s strategy keeps a foot in both worlds: cheap digital movement, with the customer choosing how and when to convert to local currency.

Why Build MGUSD

With dozens of stablecoins already on the market, the obvious question is why issue another. Soohoo reached for an Apple analogy. Just as Apple designs its own processors to tune them tightly to the iPhone, MoneyGram wanted a coin tuned to its own use cases. “We see MGUSD as our foundational, maybe we call it our own microprocessor, our own ASIC chip specifically for our use case,” he said.

Owning the coin gives the company more control, more of the underlying economics, and the ability to pass savings to customers, he said. MGUSD is a native US dollar stablecoin that lives strictly inside the MoneyGram network. It is “not built for traders or institutions,” Soohoo said, but for the company’s customers, who still pass standard KYC checks, as a base for future services spanning send, receive, stored value, rewards, and spending.

Under the hood, MoneyGram assembled a stack of specialists rather than building everything itself. Bridge serves as the regulated issuer, M0 provides the smart-contract infrastructure that manages flows, the coin is built on Stellar, and Fireblocks handles treasury and custody. Soohoo described running a build, buy, or partner analysis for each layer, keeping governance and design in-house while orchestrating outside partners for issuance and settlement.

A Seat on the Rails

MoneyGram’s validator role on Tempo, a blockchain purpose-built for payments with features such as memo fields, batched transactions, and native privacy, fits the same backend logic. Tempo was incubated with close involvement from Stripe, already a significant MoneyGram partner.

Becoming a validator lets MoneyGram learn from the infrastructure and contribute back to the network, Soohoo said, and reflects a broader conviction: “You can’t be a great global payments company if you don’t understand and are not part of the infrastructure.”

Products and the Unbanked

If MGUSD effectively hands a dollar-denominated account to millions of customers with cash-in and cash-out at hundreds of thousands of points, the natural next step is spending. Soohoo declined to confirm a card or any unannounced product, saying only that the goal is to “democratize” financial services for the billions of people with limited access. These are existing customers, he noted, and the aim is to deepen those relationships over time.

The Regulatory Patchwork

Yield and rewards on stablecoins are, in Soohoo’s words, “a hot topic.” MoneyGram’s approach is to follow the law and work closely with regulators, which is why it launched in the United States first, where the GENIUS Act and the pending Clarity Act provide clearer guardrails that let the company move faster. He expects different “flavors” of what is permitted by jurisdiction, with rewards a major selling point in some markets and off the table in others.

The global picture is uneven. Brazil recently moved to restrict stablecoin settlement for foreign-exchange businesses, a reminder that some destination regulators worry about capital controls and dollarization. Soohoo declined to comment on specific jurisdictions but argued the technology is early, likening the moment to how people discussed generative AI before ChatGPT arrived. MoneyGram, he said, will operate within whatever frameworks governments set, and sees local-currency stablecoins as a natural extension of the currency-pair trading it already does. “We’ve been doing it forever,” he said.

The Convergence Bet

Soohoo closed on why he thinks the timing is unusual. “I don’t think in the history of my career in tech have I ever seen a new platform shift happening at the same time,” he said, citing blockchain, AI, and agentic commerce converging at once, where prior eras turned on a single platform like the PC, the internet, or mobile.

The hardest problem in any platform shift, he added, is distribution, and that is where MoneyGram believes it holds an edge. “We already have distribution across the world,” he said, alongside decades of customer relationships. “Our MoneyGram brand stands for trust.” As for what comes next, he offered a two-word answer: “Stay tuned.”