Speaking on Cointelegraph’s Chain Reaction, Christian Trummer said MiCA has increased trust in regulated platforms and called for stricter enforcement against noncompliant firms.
Speaking on Cointelegraph’s Chain Reaction, Christian Trummer said MiCA has increased trust in regulated platforms and called for stricter enforcement against noncompliant firms.
Stablecoin issuer Circle urged the European Commission to revise reserve requirements in its response to a consultation on reviewing the Markets in Crypto-Assets Regulation (MiCA).
In Thursday’s summary of its response, the USDC and EURC issuer said mandatory bank-deposit requirements expose stablecoin issuers to banking-sector credit and counterparty risks.
Circle faced those risks firsthand in March 2023, when USDC temporarily lost its dollar peg after the company disclosed that $3.3 billion of its reserves were held at Silicon Valley Bank. The funds were subsequently made available after US authorities protected the bank’s depositors.
The consultation, which closed Wednesday, sought feedback on how MiCA is working and whether it remains fit for purpose as crypto markets develop. Responses will inform the Commission’s assessment of the regulation and activities beyond its current scope.
Related: MiCA focus shifts from rulemaking to supervision, ESMA chair says
MiCA currently requires e-money token issuers to hold at least 30% of reserves in commercial bank deposits, with a higher minimum of 60% for significant issuers, according to Circle.
Circle backed reconsidering the mandatory deposit minimums and replacing them with a more flexible minimum asset liquidity requirement, agreeing with the European Central Bank.
The company also called for removing two reserve concentration limits that impose a 35% cap on exposure to a single sovereign and a ceiling on deposits with each counterparty equivalent to 1.5% of that bank’s total assets.
The stablecoin issuer also urged the Commission to preserve “multi-issuance,” through which a European Union-authorized entity and a foreign-regulated counterpart co-issue a stablecoin. Restricting that structure would push users toward offshore providers outside MiCA’s protections, Circle argued.
Related: 50,000 Europeans call on EU to ease stablecoin rewards restrictions in MiCA review
The Hyperliquid Policy Center also responded to the consultation, urging the Commission to treat crypto perpetual futures under the EU’s existing securities and derivatives framework, the second Markets in Financial Instruments Directive, or MiFID II.
The group called for requirements tailored to perpetual futures’ market structure and recognition of public blockchain records as a way to meet transparency and recordkeeping obligations.
The Global Blockchain Business Council recommended clearer token classification, proportionate stablecoin safeguards and less duplication between MiCA and payment-services rules.
On cross-border stablecoin issuance, GBBC called for clear redemption responsibilities, enforceable reserve rebalancing and an accountable EU supervisory framework.
Magazine: Stablecoins can drain from banks and nations at lightning speed
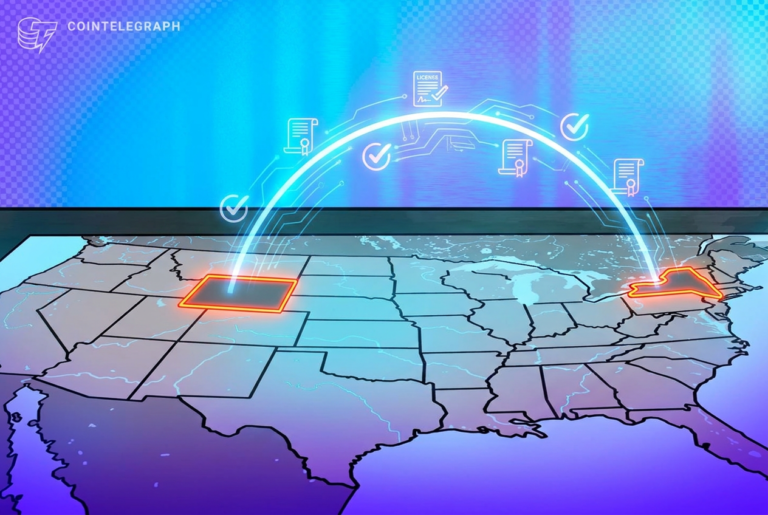
New York and Wyoming financial regulators have signed an agreement to coordinate oversight of crypto companies operating across both states, including licensing, examinations and potential enforcement actions.
The Memorandum of Understanding (MOU), announced Thursday by the New York State Department of Financial Services (NYDFS) and the Wyoming Division of Banking, applies to firms already regulated in either state and those seeking approval in both jurisdictions.
Under the agreement, the regulators will share analysis and historical examination data to streamline applications, coordinate examination schedules and work toward joint examinations of companies operating in both states.
The agreement also provides an expedited pathway for certain firms already regulated in one state that seek approval in the other. Companies operating under an existing license or charter for at least three years and not subject to enforcement action could receive an expedited review, with the second regulator aiming to reach a decision within six months.
The MOU establishes protocols for sharing supervisory reports, market trend data and notifications about potential enforcement actions. The regulators will periodically share investigative information and may undertake enforcement actions jointly, in coordination or separately.
The agreement links two states that have historically taken different approaches to crypto regulation. New York has maintained its BitLicense regime since 2015, subjecting crypto firms to what NYDFS calls “rigorous licensing standards,” while Wyoming has sought to accommodate digital asset businesses through crypto-focused laws, regulations and specialized banking charters.
Magazine: Stablecoins can drain from banks and nations at lightning speed
Crypto advocacy organizations behind a lawsuit opposing Illinois’ Digital Asset Tax reported that state officials agreed to delay implementation by six months.
In a Thursday filing in the circuit court of Sangamon County, Illinois, the crypto and blockchain advocacy group Digital Chamber said that Illinois would postpone a 0.2% tax on digital assets from Jan. 1 to July 1, 2027. The organization sued Illinois Attorney General Kwame Raoul and the Department of Revenue official David Harris in July, claiming the tax had been “slipped into the state’s budget” without debate or public feedback.
“The Parties stipulate that continuing the Tax’s effective date from January 1, 2027 until July 1, 2027 will permit orderly briefing and adjudication of the underlying legal questions without prejudicing any Party’s rights, claims, or defenses on the merits,” the filing said.
Source: Digital Chamber
The digital asset tax was included in a senate bill as part of the Illinois state budget for the fiscal year 2027, signed into law by Governor JB Pritzker in June. Under the legislation, crypto brokers would have been required to impose a 0.2% tax or face potential prison time and fines starting on Jan. 1.
Related: Illinois draft crypto tax rules detail DeFi, stablecoin treatment
Digital Chamber CEO Cody Carbone called the delay a “major win” for the crypto industry but said that the organization would continue to attempt to overturn the tax in court.
“[A] delay is not a repeal,” said Carbone. “The job isn’t done, and we won’t stop until this tax is struck down for good.”
The Digital Chamber’s lawsuit was separate from legal actions taken by the Crypto Council for Innovation (CCI) and Blockchain Association (BA) in August. The two trade associations argued against the crypto tax on constitutional grounds, later seeking to block its Jan. 1 implementation with a preliminary injunction.
As of Thursday, the status of the CCI and BA lawsuit was unclear given the agreement for a six-month delay. Cointelegraph contacted the organizations for comment but did not receive an immediate response.
Magazine: Exchanges reporting crypto gains to IRS becomes tax nightmare
Cointelegraph is committed to providing independent, high-quality journalism across the crypto, blockchain, AI, and fintech industries.
All news, reviews, and analyses are produced with full journalistic independence and integrity. For more details on our standards and processes, please read our Editorial Policy.
The US securities regulator has proposed easing rules governing how investment advisers and funds hold crypto, potentially clearing a regulatory hurdle that has held some businesses back from offering clients digital asset investments.
The proposal, published on Thursday, would let investment advisers hold clients’ crypto assets themselves when no eligible crypto custodian is available, with conditions. It would also allow state trust companies to serve as crypto custodians.
“The crypto asset market has grown from a niche curiosity into a multi-trillion-dollar asset class to which investors actively seek exposure. Unfortunately, our rules and regulations have not kept pace,” US Securities and Exchange Commission Chair Paul Atkins said in a statement.
The proposal targets a practical barrier to crypto investment: investment advisers can struggle to find a qualified custodian for a particular token, limiting the investments they can offer clients.
The Digital Chamber has previously raised concerns about the lack of qualified crypto custodians. In a May 2025 submission to the SEC, the Digital Chamber said some advisers had declined token allocations or asked portfolio companies to retain them until custody became available.
In a statement on Thursday, SEC Commissioner Hester Peirce likened the uncertainty to a regulatory “roller coaster,” saying advisers have been “gritting their teeth and holding on for dear life” while awaiting workable custody rules.
Under the SEC proposal, advisers seeking to hold clients’ crypto themselves would have to establish that no permitted custodian is available for each asset and reassess that determination quarterly. If a custodian becomes available, the assets would need to be transferred as soon as reasonably practicable.
Self-custody would also require safeguards around private keys, cybersecurity and separation of each client’s holdings. At least two authorized individuals would have to approve any transfer of a self-custodied crypto asset.
Related: US SEC follows CFTC in staff guidance for crypto
SEC Commissioner Mark Uyeda said the proposal recognized that adviser custody creates “an inherent conflict of interest,” and that advisers’ fiduciary duties would continue to apply when they hold clients’ crypto.
The proposal would also allow regulated funds to maintain crypto assets in self-custody with their investment adviser, provided the adviser meets self-custody requirements and the fund’s board oversees the arrangement.
Using a state trust company — a financial firm authorized by a US state to look after assets on other people’s behalf — would carry separate conditions.
These include making sure the state trust company is authorized by the relevant state authority to provide crypto custody, has reasonable procedures to safeguard crypto assets from loss, theft or misappropriation and has audited financial statements and internal control reports and ensuring client holdings are segregated from the company’s own assets.
The package also proposes changes to audit, recordkeeping and disclosure requirements. The SEC will accept public comments for 60 days after the proposal is published in the Federal Register.
The latest proposal adds to a push by the SEC and Commodity Futures Trading Commission to set clearer rules for crypto under their existing powers after the CLARITY Act failed to advance in the Senate last month. The CFTC has submitted a crypto-market proposal for White House review, while the SEC has opened a path for trading tokenized stocks.
Magazine: China warns foreign spies about crypto, Singapore dominates Asia: Asia Express
The group behind US President Donald Trump’s memecoin announced that he will appear at a third event for his top tokenholders weeks after a report that investors in his crypto ventures had lost a combined $4.7 billion.
On Wednesday, the GetTrumpMemes website behind the promotion of the president’s memecoin, Official Trump (TRUMP), announced a Nov. 22 dinner for the “top 185” holders. The event will mark the third time Trump has gathered his memecoin fans for similar events, including a May 2025 dinner for 220 TRUMP holders at the Trump National Golf Club in Washington, DC, and an April 2026 luncheon for 297 guests at the president’s Mar-a-Lago property in Florida.
According to the GetTrumpMemes website, Trump will appear at his DC golf club on Nov. 22 alongside three unnamed guests. Attendance will be based on the top 185 memecoin holders, scored between Sept. 30 and Nov. 12.
In August, the nonprofit consumer advocacy organization Public Citizen estimated that investors in the Trump family’s crypto ventures were “$4.7 billion underwater” since 2022, with $3.2 billion in losses attributed to the memecoin. Market data showed that TRUMP’s price surged about 9% to $2.23 from $2.05 immediately after the dinner announcement on Wednesday.
Trump launched the memecoin shortly before his January 2025 inauguration, and the price surged sharply to $70 before dropping below $20 within days. At the time of publication, the token was trading at $2.06.
Related: Hunter Biden’s laptop controversy gets a memecoin afterlife
Many critics of the first memecoin event accused Trump of selling access to the presidency through “pay-to-play” schemes. Justin Sun, the founder of the Tron network and the top holder at the time of Trump’s May 2025 dinner, held about $19 million worth of the token. The US Securities and Exchange Commission (SEC), whose chair was picked by Trump, later settled a lawsuit against Sun for $10 million.
According to Trump’s 2025 disclosures, the president reported $1.4 billion in crypto-related earnings, including his TRUMP memecoin. A White House spokesperson referred Cointelegraph to the event organizers for comment.
“In the best case, the dinner is unethical and unconscionable profiteering off the presidency,“ Public Citizen co-president Robert Weissman told Cointelegraph. “People are buying the memecoin and eager to attend a dinner only because Trump is president. In the worst case, this is pay-to-play access to the president: spend enough on Trump’s memecoin and you may get a chance to whisper to the President of the United States about a preferred policy, enforcement action or requested favor.“
In a Thursday Bluesky post, Senator Chris Coons called the memecoin event “corruption.”
The announcement of the Trump memecoin dinner came just a few weeks after lawmakers in the US Senate failed to advance the Digital Asset Market Clarity (CLARITY) Act, a bill expected to establish clear guidelines for financial agencies on the oversight and enforcement of cryptocurrencies.
All Democrats present voted nay on the legislation, with some saying the bill’s ethics provision is not sufficient to address Trump profiting from the crypto industry.
“President Trump, his children, and his Cabinet are making billions of dollars in the crypto space, in part from bilking everyday Americans out of their hard-earned money,” said Senator Ellissa Slotkin after her vote against CLARITY on Sept. 15. “I cannot in good conscience vote for any legislation that codifies that behavior from public officials.”
The Senate has a limited window to address CLARITY before the next session of Congress in 2027. Many polls showed Democrats favored to take majority control of the House of Representatives and Senate, leaving the Republican-led bill’s future uncertain.
Magazine: Is there any chance left to save the CLARITY Act?
More than 50,000 Europeans have urged the European Commission to loosen restrictions on stablecoin rewards as part of its review of the bloc’s Markets in Crypto-Assets (MiCA) framework, according to crypto advocacy group Stand With Crypto EU.
The campaign came as the Commission closed its MiCA review consultation on Wednesday, with Stand With Crypto EU pushing for regulated stablecoin providers to be allowed to offer incentives including cashback, loyalty benefits and fee reductions.
The group said more than 50,000 supporters wrote to the Commission during the consultation, while more than 126,000 people have separately signed its petition calling for a more permissive EU approach to stablecoins.
Stand With Crypto EU campaign vehicle outside the European Parliament in Brussels, Belgium. Source: Stand With Crypto EU
MiCA prohibits issuers and crypto service providers from paying interest on stablecoins, a restriction Stand With Crypto argues puts the products at a disadvantage to bank deposits and other e-money products that can offer benefits to customers.
Stand With Crypto said the campaign generated more than six times the 8,221 responses submitted to the European Central Bank’s (ECB) digital euro consultation and far exceeded the 198 responses received during the Commission’s 2020 consultation on crypto rules.
“We are calling on the Commission to use the MiCA review to allow regulated stablecoins to offer rewards to holders,” Stand With Crypto EU general manager Harry Pearce Gould told Cointelegraph.
Asked whether Europe should look to regulatory models outside the EU, Pearce Gould pointed to the US:
The US has made a clear choice to back stablecoins as the settlement layer for tokenisation. Europe doesn’t need to copy that, but it does need to compete with it.
He added that allowing rewards could help euro-denominated stablecoins gain adoption and compete with dollar stablecoins.
“Strong euro stablecoins matter for the euro’s global standing and the EU’s payment sovereignty,” he said.
Related: Binance’s EU services face scrutiny over licensing exemption: Report
The campaign comes as European central banks are pushing for broader changes to MiCA’s treatment of stablecoins.
In a Sept. 22 response to the European Commission’s MiCA review, the European System of Central Banks (ESCB) called for the existing prohibition on stablecoin interest to extend to lending, borrowing and staking arrangements that generate yield.
The ESCB also proposed replacing MiCA requirements that stablecoin issuers hold a minimum share of their reserves in bank deposits with liquidity thresholds. The central banks argued that the existing rules could strain lenders if a stablecoin run forced an issuer to rapidly withdraw deposits.
The ECB has separately highlighted a potential liquidity mismatch, noting in June that stablecoins settle around the clock while their reserve assets may still operate on traditional settlement timelines.
Source: European Central Bank
The proposals come amid broader concerns from the ECB over stablecoins’ potential impact on financial stability.
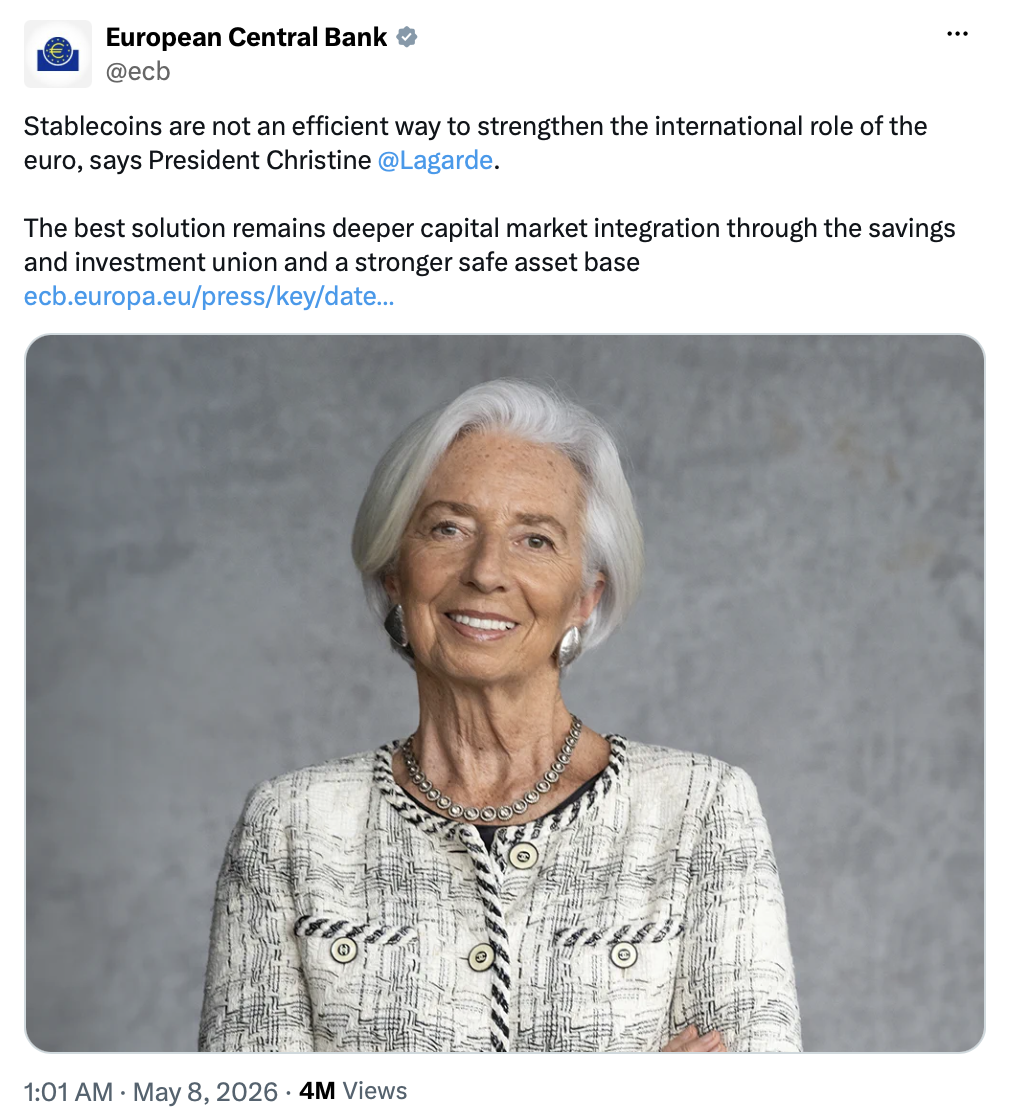
In May, ECB President Christine Lagarde warned that a shift of deposits from banks into stablecoins could weaken bank lending and monetary policy transmission, while arguing that Europe should instead prioritize tokenized financial infrastructure anchored by central bank money.
Magazine: Peter Brandt says Bitcoin may hit $600K by 2029, calls XRP a ‘fool coin’
Anyone who’s ever sent a bank transfer overseas is familiar with the painful process of waiting for things like working hours, correspondent banks and settlement times.
In many cases, it would be faster, cheaper and just more efficient to strap the physical cash to a homing pigeon, or slap it in an envelope and send it via DHL.
Stablecoins can move money across borders around the clock, without waiting for the legacy system to fire up its steam engines.
They can settle transactions 24/7, cut out layers of intermediaries and give people access to digital dollars without even needing a traditional bank account.
So do we even need banks any more? And what are the ramifications of stablecoins offering a faster, cheaper and easier way to move money?
Anthony Vassallo, director of crypto at Silicon Valley Bank, which failed in March 2023 and now operates as a division of First Citizens Bank, tells Magazine competition from stablecoins will show up across two time frames:
“Two clocks matter. One is slow: currency substitution, deposit erosion, and weakening policy transmission building over months or years. One is fast: a depeg, issuer shock, or banking event that can move capital at software speed within hours.”
The European Central Bank raised concerns about the impacts, arguing that large amounts of stablecoin reserves held in bank deposits could trigger cascading withdrawals if there were a surge in redemptions.
The bank points to a “liquidity mismatch” between digital money and the banking system that supports it, with reserve assets subject to traditional settlement timelines, while stablecoins settle around the clock.
Related: MiCA cracks down on USDT in Europe… but no one else cares
We already saw that dynamic in action in March 2023 when USD Coin lost its dollar peg after Circle’s disclosure that $3.3 billion of its reserves were held at the failed Silicon Valley Bank. The incident turned a banking failure into a stablecoin crisis almost overnight, with authorities having to step in to guarantee deposits.
Large stablecoin reserves could trigger a bank run. Source: ECB
Bank runs are pretty extreme cases; the slower clock Vassallo describes has more of a drip-drip effect. It can happen without a crisis, and may be harder to see as it unfolds.
In July 2026, the Bank for International Settlements looked at stablecoin flows and conventional foreign currency deposits across 130 economies.
It found that both tend to grow at times of currency pressure and during banking or sovereign crises, with stablecoin flows appearing less affected by capital controls.
So, when people are trying to move out of a deteriorating local currency, stablecoins can provide a dollar-based alternative that’s harder for local governments to contain.
A September report from Sphere Labs and SVB describes Argentina, Nigeria and Turkey as markets where stablecoin demand has been closely connected to demand for dollar exposure.
In Argentina, for example, it says 94% of crypto bought with pesos was in stablecoins, while in Turkey, around $38 billion worth of lira was swapped for stablecoins over a year.
Arnold Lee, chief executive of Sphere Labs, says stablecoin adoption is fundamentally a dollar story driven by demand for dollars from people who face barriers to accessing the traditional banking system. He tells Magazine:
“Most of these economies are going to keep moving toward dollars […] What I spend my time on is the manner of it, because a country that manages the shift and one that gets overtaken by it end up in very different places.”
A separate BIS study published in March found that a rise in demand for dollar stablecoins can spill into traditional currency markets.
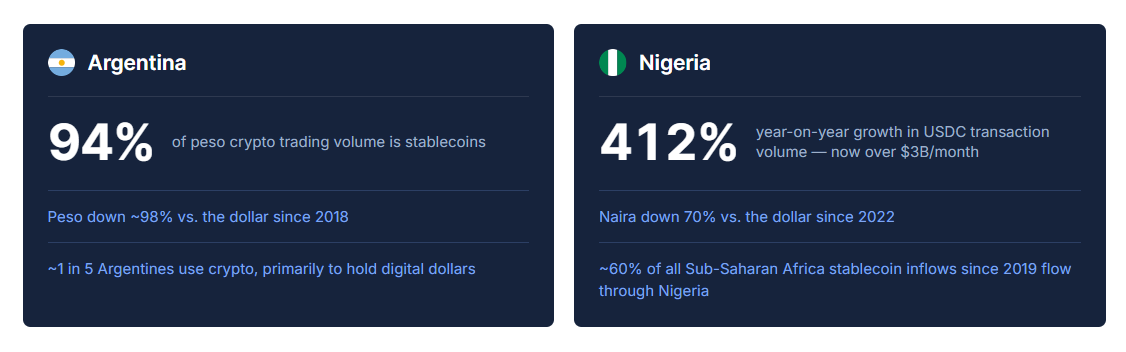
Markets where stablecoin demand is connected to demand for dollar exposure. Source: Sphere/SVB
The study looked at four major USD-pegged stablecoins across 27 fiat currencies between 2021 and 2025, and found that increased stablecoin demand could put downward pressure on local currencies and make dollars more expensive to obtain through FX swaps, with the effect stronger when financial intermediaries were already under strain.
Lee says, “When citizens in high-inflation economies move from local currency into digital dollars, monetary transmission weakens, deposit bases erode, and pressure builds faster than central banks can respond.”
Related: Stablecoins not credible for payments at scale, BIS chief says
The Sphere report describes how, during a January 2025 dispute between the US and Colombia, Colombians plowed funds into digital dollars. Banks and currency exchanges were closed for the weekend, but the casa de blockchain is always open.
That’s where the ECB’s warning shot reverberates the loudest.
Under current Markets in Crypto Assets (MiCA) rules, stablecoin issuers must hold at least 30% of reserves in bank deposits, and up to 60% for significant asset-referenced tokens (ARTs).
Lessons for the rise of stablecoins. Source: BIS
The European System of Central Banks proposed moving away from those fixed percentages earlier this month, toward requirements based on how quickly reserve assets can be made available.
That would avoid a doomsday scenario where heavy redemptions bleed commercial lenders dry overnight; something Tether chief executive Paolo Ardoino warned about in 2024, when he called MiCA “very dangerous when it comes to stablecoins.”
So the same system can create pressure in both directions: money can leave a bank and move into stablecoins when users want digital dollars, then flow back through banks when those stablecoins are redeemed.
The technology doesn’t determine which direction the flow takes, but it can determine how quickly it can happen.
However, stablecoins are not taking over the world just yet. Often they are simply an intermediate currency that moves faster, but still ends up as dollars in the bank.
Pankaj Bengani, former executive at Block and co-founder of stablecoin payments company MELD, tells Cointelegraph that close to half of the company’s B2B stablecoin offramp volume is in North America.
He says the businesses using it include importers, exporters, technology firms, e-commerce marketplaces, payment companies and fintechs.
“The vast majority of corporates in our data convert back to fiat immediately after the transaction settles. They are not taking a crypto position. They are using MELD as a settlement rail instead of SWIFT,” Bengani says.
He says the biggest flows are cross-border commercial payments, particularly where businesses earn or hold dollars but suppliers and employees need local currency.
Supplier payments make up close to a third of business use, while invoice settlement accounts for roughly a quarter.
That paints a different picture from people turning to digital dollars to protect their savings from inflation or yanking lump sums out of the fiat system in times of stress.
And it raises another interesting question: if the money isn’t staying in crypto, what part of the traditional system is actually being displaced? Bengani says:
“Stablecoins won’t replace SWIFT overnight. The realistic change is a thinner correspondent layer, with a common settlement rail replacing intermediary steps that exist only because banks historically needed each other to cross borders.”
In a world where money moves at the speed of thought, that doesn’t mean banks disappear.
Bengani says reserves still sit in bank deposits and Treasuries, businesses still need fiat currencies, and banks remain important for “custody, compliance, liquidity, and local settlement.”
But what changes is the plumbing in between — stablecoins may not be removing banks from the financial system as much as changing where the friction sits.
Magazine: Exchanges reporting crypto gains to IRS becomes tax nightmare
Cointelegraph publishes long-form journalism, analysis and narrative reporting produced by Cointelegraph’s in-house editorial team with subject-matter expertise. All articles are edited and reviewed by Cointelegraph editors in line with our editorial standards. Some articles contain affiliate links, from which Cointelegraph may earn a commission. These relationships do not influence which products we review or our editorial conclusions. Content published in here does not constitute financial, legal or investment advice. Readers should conduct their own research and consult qualified professionals where appropriate. Cointelegraph maintains full editorial independence.
European regulators are reportedly scrutinizing Binance’s use of a legal exemption to continue serving customers in the European Union without authorization under the bloc’s crypto rules.
The European Securities and Markets Authority (ESMA) and regulators in France, Germany and Greece are examining Binance’s use of reverse solicitation under the Markets in Crypto-Assets Regulation (MiCA), the Financial Times reported on Thursday.
Binance withdrew its Greek MiCA application in June and said it would seek authorization in another EU member state.
Binance told Cointelegraph on Sept. 18 that it continues pursuing MiCA authorization and remains committed to operating in Europe on a long-term compliant basis.
Binance is relying on reverse solicitation to continue serving some EU customers, the report said, citing a person familiar with the matter.
The exemption allows non-EU crypto asset service providers (CASPs) to serve customers who approach them entirely on their own initiative, but ESMA’s guidelines stress that companies cannot use it to circumvent MiCA requirements.
Related: Binance disappears from Google Play in certain EU countries
Ahead of the end of MiCA’s transitional period on July 1, Binance told Cointelegraph that EU access would depend partly on a user’s jurisdiction, account status and “servicing entity.” Some EU traders are now being served through Binance’s Abu Dhabi-regulated entity, according to the FT.
Binance did not confirm whether it was in talks with EU regulators, telling Cointelegraph that it “complies with applicable regulatory requirements.”
ESMA on Wednesday called for stronger powers over non-EU companies that solicit European investors without MiCA authorization in its response to the European Commission’s consultation on reviewing the regulation.
ESMA said its proposals would support faster, more consistent supervisory action across the EU and reduce opportunities for companies to exploit regulatory differences.
Related: EU banking watchdog calls for crypto lending rules under MiCA
The push follows ESMA Chair Verena Ross saying Monday that the regulator’s MiCA focus had shifted “from rulemaking towards supervision and convergence.”
ESMA’s register of non-compliant crypto providers grew from 164 entries on July 16 to 173 in its Sept. 30 update.
Binance does not appear on the latest register, which MiCA describes as “non-exhaustive” and which ESMA updates based on information from national authorities and other sources.
ESMA told Cointelegraph it does not comment on specific cases, adding that supervision, investigation and enforcement of crypto asset service providers under MiCA are handled by national authorities. It also said the information in its MiCA register is provided by national competent authorities, with entries reflecting information received from the relevant authorizing or notified regulator.
Germany’s Federal Financial Supervisory Authority (BaFin) declined to provide further information, citing legal confidentiality obligations. The French and Greek watchdogs had not responded by publication.
Magazine: MiCA is coming for DeFi vaults, but regulation will be difficult