Home Blog Page 1274

After A Snake-Like 2025, Is The Bitcoin Price Ready To Break Out In 2026?

0

We had high hopes for the bitcoin price in 2025. It was supposed to be the crescendo of the four-year cycle, the most bullish setup in recent memory. It was the year after the halving, the ETFs had just been approved, a new president was elected, with the promise of the money printer roaring back to life. Everything looked primed for a Q4 blow-off top, and instead of a new life in Monaco, all you got was this lousy article.

What follows is my interpretation of the events of 2025 and my outlook for 2026. I’m not a trader, not an analyst, and like you, I’ve been outperforming professional funds for years, by simply stacking Sats, of course. I’m more of a “fix the money, fix the world” kinda guy, but like everyone else, it’s hard to ignore Bitcoin’s price movements, which I think of as the game of “Snakes and Ladders”.

The bitcoin price as a game of Snakes and Ladders.

In the game of Snakes and Ladders, momentum drives us forward, but it can also provide a false sense of confidence. You can be one roll away from victory, only to land on a snake that sends you sliding back ten places. As much as hopium dictates that we pray for the price to go ‘up and to the right’, markets rarely oblige. Switching from the board to the chart, price action is played on a board of global liquidity and market sentiment. When sentiment is low or liquidity dries up, no amount of good news can sustain momentum. We simply crab sideways or find a snake that slides us down into further despair.

On the other hand, when liquidity floods the system, we often find the ladders that shoot us through resistance levels. For most of 2025, we were stuck playing the former, while dreaming of the “ladder”. So let’s take this time to review 2025 from the perspective of hindsight, as foresight proved to be of little benefit.

What Happened To Our 2025 Bull Run?

If there is a phrase that defines the Bitcoin market of 2025, it is exactly that: a Year of Snakes and precious few ladders. Interestingly, and unbeknownst to me, 2025 was indeed the year of the snake according to the 12-year Chinese zodiac cycle, starting January 29, 2025, and ending February 16, 2026.

The bitcoin price in 2025, overlayed with the Chinese Year of the Snake.

We began the year with the kind of euphoria that usually marks a cycle top. The halving was behind us, and the political stars had aligned perfectly. Google trends showed search queries were soaring. In fact, the year kicked off with a quiet but massive victory before the political fireworks even started: FASB fair value accounting rules took effect on January 1st, finally allowing companies to report bitcoin profits rather than just losses.

Then came the main event. We witnessed the inauguration of a “Bitcoin President.” Gary Gensler departed, leaving behind a legacy that, in hindsight, was perhaps less villainous than we assumed, and Ross Ulbricht walked free within 48 hours. With the new administration came a few allies: Paul Atkins took over the SEC and Mike Selig the CFTC, securing a pro-crypto cabinet.

The financial plumbing was finally completed. The ETFs were fully operational, options trading on IBIT were unleashed, and it quickly became clear that Michael Saylor was not about to let Larry Fink steal his thunder. MicroStrategy went on a $25 billion buying spree, 100x what they bought in 2020, and the corporate treasury list exploded from 60 companies to nearly 200.

By October, the engines were well and truly revving. We hit the All-Time High on October 6th, ready to punch the accelerator for the glorious Q4 end-of-cycle run. Instead, we shifted the gear into reverse and slid all the way down to $80,000.

First, we got our knickers in a twist over the “Knots vs. Core” drama. Then came the Binance incident, where the snake manifested itself as a “technical issue” at precisely the wrong time, and right as Gold broke out. We essentially got rug-pulled by a glitch. The issue of October 10th likely created added sell pressure through forced liquidations, whilst also triggering the 4-year cycle sellers who have been trained to sell Q4 of the 4th year. Few understood the gravity of it at the time, though I tip my hat to Jesse Olson for calling it early.

Then the FUD machine was turned on. First, it targeted MicroStrategy with threats of MSCI exclusion; it didn’t help sentiment that its mNAV has been dropping all year. Then it pivoted back to Bitcoin with the return of the “quantum attack” narrative.

While the headlines swirled, the bitcoin price became stuck in purgatory, range-bound between $84,000 and $95,000 and trapped by options traders, even though the handcuffs had theoretically been taken off IBIT options earlier in the year. Bitcoin was having an Austin Powers moment, while Peter Schiff enjoyed his first day out in the sun since high school. Bless him.

Is The Tide About to Turn?

While some fear 2026 will bring the hangover of a post-cycle bear market, I, like countless other optimists believe otherwise. If 2025 was the year of snakes, 2026 is the year we finally climb a few ladders.

The setup is favourable. We have a Bitcoin-ish president, who’s hungry to fire up the printing press, we’ve a developing multipolar world, where the process of game theory should be heating up, there’s a $7 trillion debt wall to be paid, the old guard are positioned, the regulation stranglehold has been loosened, the cowboys (FTX, Terra-Luna, etc.) are gone, gold and silver have both had their runs, and Bitcoin’s supposed to follow next, or so we hope. 

Source: Sminston With

Not to mention, the tax year is done, and new budgets have been allocated to fund managers and businesses alike. FASB fair value accounting is now live, smoothing the runway for corporate balance sheets. Michael Saylor is still buying with the relentless intensity of a man who understands math better than Archimedes. Even the “MSCI FUD” was defeated early, so credit to George and the Bitcoin for Corporations team for that victory.

At the point in time as the price is beginning to climb higher, the bears are finally showing signs of exhaustion, that’s according to James Check and countless others. By far the most significant headwind Bitcoin faced in 2025 was the relentless onslaught of coins sold by long-term holders. That pressure looks to finally be ending. On November 1st, approximately 67% of the Realised Cap was invested above $95k. The last two months have seen a massive supply redistribution occur, with that metric declining to 47%.

Over the last 30 days, around 80% of the coins which have transacted came from higher prices. This is the definition of capitulation. The weak hands who bought the top have flushed out, and new buyers have stepped in with a lower and stronger cost basis.

Incidentally, the Year of the Snake officially ends on February 16, 2026, to be followed by a horse, which as we all know has the ability to outrun any bull. This coincides almost perfectly with the monthly CME Futures expiry on February 27th. The shedding of a snake’s skin happens right before the growth returns. 

Is the 4-Year Cycle Dead?

Really, who can truly say they know? What we do know is that the four-year cycle is no longer connected to the halvings or the presidential cycles in the way we once thought, and the halvings are less likely to have an effect going forward, as the new coins distributed are a lower percentage of supply, and the miners are supported by huge funds which can help them weather any potential death spiral.

We have not seen a Pi Cycle top signal, the 200 week moving average has not crossed the prior cycle top, the MVRV score is just 1.3, the Puell multiple is just .99, we’ve not had a considerable drawdown, and we’re still at the bottom of the range of almost every metric imaginable. For those of you who are old enough to remember the KitKat ad from the 90’s, “the 4 year cycle is not dead, it was just takin’ a break.”

As the 4-year cycle is a purely Liquidity Based Cycle, it can be measured by proxy using the ISM Manufacturing PMI, a qualitative index sourced from purchasing managers in the manufacturing industry. I give credit to Raoul Pal for highlighting this metric; he was the first I observed to point out that bitcoin is a “Liquidity” asset rather than a “Halving” asset. Bitcoin, as the highest-beta risk asset in existence, responds to shifts in global risk appetite with greater force and speed than any other asset class. The PMI tracks the business cycle, and it has been in contraction for nearly two years. The current PMI at 47.9 signals ongoing contraction, but ISM projections indicate a 4.4% revenue growth for manufacturing in 2026, crossing 50 in Q2 as Trump’s policies kick in. The bitcoin price should follow. When the ISM PMI is below 50, we’re generally in a bear market, and we’ve been that way for over two years now. The bull markets have historically topped out between 55 and 65. The question remains, when is the business cycle going to see an upturn? TechDev is of the view that it’s happening very soon, as the bullish divergence reversal momentum is decidedly building.

Source: Sminston With

The $9 Trillion Debt Question

The US government has to address the $9 trillion debt wall that’s due to mature this year. But the nuance is in how they do it. President Trump has made it clear he intends to build a “Dream Military” for 2027 and is pushing for a budget increase to $1.5 trillion. When you combine that with the $4.1 trillion of debt maturing in 2026 and the standard annual deficit, the US Treasury faces a $9 trillion liquidity gap, and a further $7.4 trillion before 2028. 

Does the US have to print all $9 trillion? No. And through this lens, the recent geopolitical moves make sense. Trump didn’t only capture Maduro for a photo-op; he has likely taken control over 303B barrels of reserves and is enforcing USD oil sales, creating artificial dollar demand and easing the liquidity gap by $2-3T annually. 

Can he cover the gap via a mix of tariffs (that Americans actually pay for!), Petro-Dollar demand, and the inevitable monetization of the rest by the Federal Reserve? I guess he’ll have to. With Jerome Powell expected to leave his chair in May, the path will be cleared to give the printer engines a whir. 

There’s another $5 – $10 tr due globally in 2026, and the same again in 2027. So the fed chair won’t be without company. 

My View: 2026–2027

The four-year cycle OGs may be stepping aside, but the Liquidity Cycle is just gearing up, and Bitcoin, as Raoul Pal has long argued, remains the ultimate liquidity barometer.

Samuel Benner’s famous 19th-century forecasting chart (first published in 1875), maps long-term cycles of panics (“A” years), booms/high prices (“B” years), and depressions/low prices (“C” years). Interestingly, 2026 falls squarely in one of Benner’s “B” years, which is a period of “Good Times, High Prices and the time to sell Stocks and values of all kinds.” The chart places 2026 right alongside previous boom years like 2016, 2007, 1999, and 1989, suggesting we are entering a structurally favorable window for risk assets.

How Long Will The Next Money Printing Last?

Prediction: 18–24 months

Why: History shows that once the dam gates open, it takes roughly two years to stabilize and reflate. If the official aggressive printing phase begins in late 2025 (as the liquidity uptick and Benner timeline imply, and as M2 shows), it will likely run strong through mid-2027.

How Much LIquidity Will Be Added?

Prediction: ~$9–$10 trillion in the U.S. Treasury debt is maturing in 2026 alone (about one-third of outstanding marketable debt) and a further $5 – $10 tr globally.

Why: As discussed above, the maturity walls for 2026 are nearly double what we faced during the COVID crisis. Yellen extended the pain by leaning on short-term issuance back then, but come hell or high water, that debt has to be paid or refinanced—the money will arrive from somewhere. Because of this, we can expect a new wave of inflation, the 70’s and 80’s have a story to tell about that!

How High Will The Bitcoin Price Go?

Prediction: $250,000

Why: During that $5 trillion COVID expansion, BTC rallied roughly 20x from the $3k–$4k lows to $69k. With the potential for double that liquidity entering the system this cycle, the upside is significant even if diminishing returns apply. From our $16k effective low, a conservative 10x to 12x multiple lands us in the $160k to $200k range as a base case. However, models suggest we could push higher. PlanC’s quantile model points toward $300k+ by the end of 2026, and Giovanni Santostasi’s Power Law projects a peak potentially around $210k early on, with room to stretch as high as $600k in outlier scenarios. But hey, I was expecting +$200k last cycle too.

Oh, if the Strategic Bitcoin Reserve Act moves out of the committee, and if the U.S. Treasury officially starts side-stacking alongside MicroStrategy, all bets are off the table.

When Will The Price Top Out?

Prediction: Late 2026 to mid-2027

The Logic: Bitcoin historically tops out 12–18 months after the liquidity expansion enters its “mania” phase. If the ISM Manufacturing PMI crosses back above 50 in early 2026, the perfect storm should unfold throughout 2026, setting up a blow-off top, potentially in the first half of 2027.

Bitcoin is unlikely to go straight up, nothing ever does. We’ll almost certainly encounter a few snakes along the way: sharp corrections, regulatory noise, profit-taking, or some form of shenanigans. But the ladders are built, ready and waiting. The Year of the Snake is coming to an end, just ahead of the February 27 CME futures expiry, our potential ignition point, right before the anticipated PMI uptick in Q2.

2025 was a year of snakes and sideways pain, with long-term holders finally capitulated and weak hands flushed out. Now, with a wall of liquidity heading our way, 2026 looks like the ladder we’ve been waiting for. The horse year is coming, so stack and secure accordingly.

Good luck. 
Starknet Partners with NEAR to Bring STRK to Solana

0

Ethereum L2 Starknet’s native token is now available across the Solana ecosystem, a day after Solana’s official X account mocked the L2 for low usage.

Ethereum Layer 2 Starknet’s token STRK is now natively accessible on Solana, with cross-chain interoperability provided by NEAR Intents, according to an announcement on Jan. 15.

The integration allows users to receive STRK directly in a Solana wallet from “a wide range of supported tokens and chains.”

The move brings STRK into Solana’s ecosystem — which has a TVL of nearly $11 billion — without requiring users to go through a standard bridging process. Instead, NEAR Intents uses a “solver-based execution model” where users specify an outcome and execution is handled behind the scenes, according to a press release viewed by The Defiant. The release emphasized the integration is meant to make the token easily accessible in Solana DeFi.

“The result is a practical cross-ecosystem workflow that prioritizes speed, usability, and real DeFi participation over novelty,” the release reads.

STRK will be available for spot trading on Solana-based decentralized exchange Jupiter, while fellow Solana DEX Meteora will act as the primary liquidity venue for STRK on the chain.

The launch comes a day after Solana’s official X account posted a jab at Starknet, criticizing the network’s reported daily activity and valuation. The post claimed Starknet had “8 daily active users” and “10 daily transactions,” while referencing its market cap and fully diluted valuation (FDV) and concluding, “Send it straight to 0.”

It also comes as Starknet has added more than $100 million in TVL since December, reaching over $313 million by press time, though it is still slightly below its March 2024 peak of nearly $331 million.

Starknet TVL 2023-present. Source: DefiLlama

STRK is currently trading at $0.086 at press time, down about 6% over the past 24 hours, according to CoinGecko. The token has a market cap of roughly $435 million. Solana’s native token, SOL, is currently changing hands at $143, down 3% on the day.

PlusAI Launches Southern Europe’s First Autonomous Trucking Program with IVECO

0

SANTA CLARA, Calif. & TURIN, Italy–(BUSINESS WIRE)–PlusAI, a leader in AI software for autonomous trucks, announced an expansion of its long-standing partnership with IVECO, the commercial vehicle brand of Iveco Group N.V. (EXM: IVG). Together, the companies will launch the first deployment of heavy-duty trucks equipped with Level 4 Autonomous Driving Systems (ADS) in Southern Europe, in collaboration with Spanish logistics operator Sesé and the Government of Aragon. This announcement comes on the heels of PlusAI’s planned public listing via a business combination with Churchill Capital Corp IX (Nasdaq: CCIX).

PlusAI and IVECO will launch the first deployment of heavy-duty trucks equipped with Level 4 Autonomous Driving Systems (ADS) in Southern Europe, in collaboration with Spanish logistics operator Sesé and the Government of Aragon.Share

Under this program, PlusAI and IVECO will develop two IVECO S-Way heavy-duty trucks integrated with PlusAI’s SuperDrive™ virtual driver, enabling Level 4 autonomous capabilities. The autonomous trucks will undergo multi-year testing starting in 2026. For the entire trial period, these trucks will operate with a safety operator on board on freight routes between Madrid and Zaragoza, a corridor spanning approximately 300 km (184 miles).

“Autonomous trucks are a transformative technology that could dramatically improve road safety and reshape commercial freight transportation worldwide,” said Shawn Kerrigan, COO and Co-Founder of PlusAI. “We are proud to deepen our partnership with IVECO and demonstrate how autonomous driving technology can enhance safety, efficiency, and sustainability while strengthening Europe’s supply chains.”

Marco Liccardo, Chief Technology & Digital Officer at Iveco Group, added: “Vehicle automation is a key pillar of Iveco Group’s technology strategy. We are thrilled to reinforce our strong partnership with PlusAI to further innovate our ADAS and ADS technologies on board IVECO trucks. This project will take us forward on our journey to offer customers the highest quality technology for increasingly sustainable transport.”

This initiative builds on years of joint research and testing between PlusAI and Iveco Group, including advanced Level 2+ and Level 4 programs. It also marks a significant milestone as PlusAI moves into its next phase of growth as a publicly traded company through its previously announced business combination with Churchill Capital Corp IX (Nasdaq: CCIX).

Upon closing, the combined company will operate as “PlusAI” and is expected to be listed on Nasdaq under the ticker symbol “PLS.” The business combination remains subject to approval by Churchill IX shareholders, the Registration Statement being declared effective by the SEC, and other customary closing conditions. The business combination is expected to close in Q1 of 2026.

About PlusAI

PlusAI is an artificial intelligence company pioneering AI-based virtual driver software for factory-built autonomous trucks. Headquartered in Silicon Valley with operations in the United States and Europe, PlusAI was named by Fast Company as one of the World’s Most Innovative Companies. Partners including TRATON GROUP’s Scania, MAN, and International brands, Hyundai Motor Company, Iveco Group, Bosch, and DSV are working with PlusAI to accelerate the deployment of next-generation autonomous trucks. PlusAI announced in June 2025 that it plans to go public via a merger with Churchill Capital Corp IX (Nasdaq: CCIX). For more information, visit www.plus.ai or follow PlusAI on LinkedIn and YouTube.

About Churchill Capital Corp IX

Churchill IX is a blank check company formed for the purpose of effecting a merger, amalgamation, share exchange, asset acquisition, share purchase, reorganization or similar business combination with one or more businesses. It may pursue an initial business combination target in any business or industry.

Additional Information About the Proposed Transaction and Where to Find It

The proposed transaction will be submitted to shareholders of Churchill IX for their consideration. Churchill IX has filed a registration statement on Form S-4 with the SEC, which includes and will include a preliminary proxy statement/prospectus and definitive proxy statement/prospectus, respectively, to be distributed to Churchill IX’s shareholders in connection with Churchill IX’s solicitation of proxies for the vote by Churchill IX’s shareholders in connection with the proposed transaction and other matters described in the Registration Statement, as well as the prospectus relating to the offer of the securities to be issued to PlusAI stockholders in connection with the completion of the proposed transaction. After the Registration Statement has been filed and declared effective, a definitive proxy statement/prospectus and other relevant documents will be mailed to PlusAI stockholders and Churchill IX shareholders as of the record date established for voting on the proposed transaction. Before making any voting or investment decision, Churchill IX shareholders, PlusAI stockholders and other interested persons are advised to read the preliminary proxy statement/prospectus and any amendments thereto and, once available, the definitive proxy statement/prospectus, as well as other documents filed with the SEC by Churchill IX in connection with the proposed transaction, as these documents will contain important information about Churchill IX, PlusAI and the proposed transaction. Shareholders may obtain a copy of the preliminary proxy statement/prospectus, and the definitive proxy statement statement/prospectus once available, as well as other documents filed by Churchill IX with the SEC, without charge, at the SEC’s website located at www.sec.gov or by directing a written request to Churchill Capital Corp IX, 640 Fifth Avenue, 12th Floor, New York, NY 10019.

Forward-Looking Statements

This press release includes “forward-looking statements” within the meaning of the federal securities laws. Forward-looking statements may be identified by the use of words such as “plan,” “project,” “will,” “estimate,” “intend,” “expect,” “believe,” “target,” “continue,” “could,” “may,” “might,” “possible,” “potential,” “predict” or similar expressions that predict or indicate future events or trends or that are not statements of historical matters. We have based these forward-looking statements on current expectations and projections about future events. These statements include: expectations regarding the completion of the business combination between PlusAI and Churchill IX; estimates of customer adoption rates and usage patterns; projections regarding the value and capabilities of autonomous driving solutions; projections of development and commercialization timelines; expectations regarding PlusAI’s ability to execute its business model; expectations regarding safety and system maturity of SuperDrive; PlusAI’s deployment of virtual driver software; PlusAI’s expectations concerning relationships with strategic partners, suppliers, governments, regulatory bodies and other third parties; future ventures or investments in companies, products, services, or technologies; the potential benefits of the proposed transaction and expectations related to its terms and timing; and the potential for PlusAI to increase in value.

These forward-looking statements are provided for illustrative purposes only and are not intended to serve as, and must not be relied on as, a guarantee, an assurance, a prediction or a definitive statement of fact or probability. Actual events and circumstances are difficult or impossible to predict and will differ from assumptions, many of which are beyond the control of PlusAI and Churchill IX.

These forward-looking statements are subject to known and unknown risks, uncertainties and assumptions that may cause our actual results, levels of activity, performance or achievements to be materially different from any future results, levels of activity, performance or achievements expressed or implied by such statements. Such risks and uncertainties include: that PlusAI is pursuing an emerging technology, faces significant technical challenges and may not achieve commercialization or market acceptance; PlusAI’s historical net losses and limited operating history; PlusAI’s expectations regarding future financial performance, capital requirements and unit economics; PlusAI’s use and reporting of business and operational metrics; PlusAI’s competitive landscape; PlusAI’s dependence on members of its senior management and its ability to attract and retain qualified personnel; the capital requirements of PlusAI’s business plans and the potential need for additional future financing; PlusAI’s ability to manage growth and expand its operations; potential future acquisitions or investments in companies, products, services or technologies; PlusAI’s reliance on strategic partners and other third parties; PlusAI’s ability to maintain, protect and defend its intellectual property rights; risks associated with privacy, data protection or cybersecurity incidents and related regulations; the use and regulation of artificial intelligence and machine learning; uncertainty or changes with respect to laws and regulations; uncertainty or changes with respect to taxes, trade conditions and the macroeconomic environment; the combined company’s ability to maintain internal control over financial reporting and operate a public company; the possibility that required regulatory approvals for the proposed transaction are delayed or are not obtained, which could adversely affect the combined company or the expected benefits of the proposed transaction; the risk that shareholders of Churchill IX could elect to have their shares redeemed, leaving the combined company with insufficient cash to execute its business plans; the occurrence of any event, change, or other circumstance that could give rise to the termination of the business combination agreement; the outcome of any legal proceedings or government investigations that may be commenced against PlusAI or Churchill IX; failure to realize the anticipated benefits of the proposed transaction; the ability of Churchill IX or the combined company to issue equity or equity-linked securities in connection with the proposed transaction or in the future; and other factors described in Churchill IX’s filings with the SEC. Additional information concerning these and other factors that may impact such forward-looking statements can be found in filings and potential filings by PlusAI, Churchill IX or the combined company resulting from the proposed transaction with the SEC, including under the heading “Risk Factors.” If any of these risks materialize or assumptions prove incorrect, actual results could differ materially from the results implied by these forward-looking statements. In addition, these statements reflect the expectations, plans and forecasts of PlusAI’s and Churchill IX’s management as of the date of this communication; subsequent events and developments may cause their assessments to change. While PlusAI and Churchill IX may elect to update these forward-looking statements at some point in the future, they specifically disclaim any obligation to do so. Accordingly, undue reliance should not be placed upon these statements.

In addition, statements that “we believe” and similar statements reflect our beliefs and opinions on the relevant subject. These statements are based upon information available to us as of the date of this communication, and while we believe such information forms a reasonable basis for such statements, such information may be limited or incomplete, and our statements should not be read to indicate that we have conducted an exhaustive inquiry into, or review of, all potentially available relevant information. These statements are inherently uncertain and investors are cautioned not to unduly rely upon these statements.

An investment in Churchill IX is not an investment in any of our founders’ or sponsors’ past investments, companies or affiliated funds. The historical results of those investments are not indicative of future performance of Churchill IX, which may differ materially from the performance of our founders’ or sponsors’ past investments.

Participants in the Solicitation

Churchill IX, PlusAI and certain of their respective directors, executive officers and other members of management and employees may, under SEC rules, be deemed to be participants in the solicitation of proxies from Churchill IX’s shareholders in connection with the proposed transaction. Information regarding the persons who may, under SEC rules, be deemed participants in the solicitation of Churchill IX’s shareholders in connection with the proposed transaction will be set forth in proxy statement/prospectus/consent solicitation statement when it is filed by Churchill IX with the SEC. You can find more information about Churchill IX’s directors and executive officers in Churchill IX’s final prospectus related to its initial public offering filed with the SEC on May 1, 2024 and in the Annual Reports on Form 10-K filed by Churchill IX with the SEC. Additional information regarding the participants in the proxy solicitation and a description of their direct and indirect interests will be included in the proxy statement/prospectus/consent solicitation statement when it becomes available. Shareholders, potential investors and other interested persons should read the proxy statement/prospectus/consent solicitation statement carefully when it becomes available before making any voting or investment decisions. You may obtain free copies of these documents from the sources described above.

No Offer or Solicitation

This communication does not constitute an offer to sell or the solicitation of an offer to buy any securities, or a solicitation of any vote or approval, nor shall there be any sale of securities in any jurisdiction in which such offer, solicitation or sale would be unlawful prior to registration or qualification under the securities laws of any such jurisdiction. This communication is not, and under no circumstances is to be construed as, a prospectus, an advertisement or a public offering of the securities described herein in the United States or any other jurisdiction. No offer of securities shall be made except by means of a prospectus meeting the requirements of Section 10 of the Securities Act of 1933, as amended, or exemptions therefrom. INVESTMENT IN ANY SECURITIES DESCRIBED HEREIN HAS NOT BEEN APPROVED BY THE SEC OR ANY OTHER REGULATORY AUTHORITY NOR HAS ANY AUTHORITY PASSED UPON OR ENDORSED THE MERITS OF THE OFFERING OR THE ACCURACY OR ADEQUACY OF THE INFORMATION CONTAINED HEREIN. ANY REPRESENTATION TO THE CONTRARY IS A CRIMINAL OFFENSE.

Mass Protests Fuel Iran’s Crypto Boom, Shattering $7.8B Mark

0

Trusted Editorial content, reviewed by leading industry experts and seasoned editors. Ad Disclosure

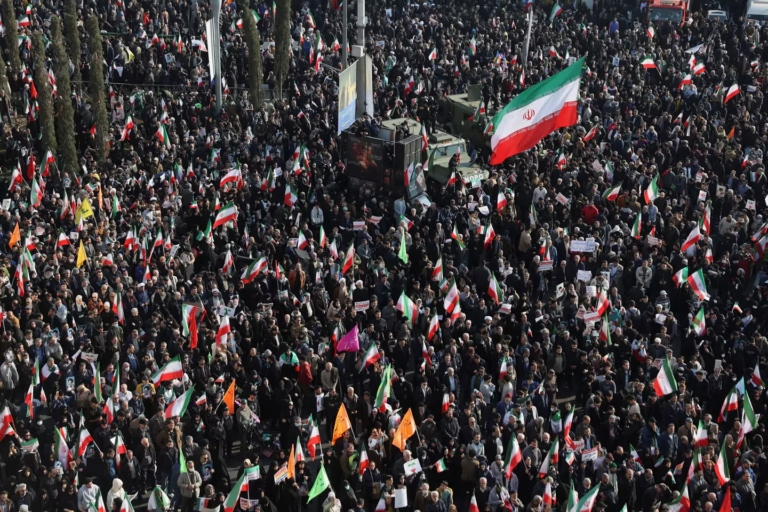
Iran’s on-chain crypto activity surged to about $7.80 billion in 2025, driven in large part by mass protests that began in late December 2025.

According to Chainalysis, the rise reflects both ordinary people moving assets out of banks and state-linked actors shifting funds on blockchain networks.

The shift was sharp and sudden; many withdrawals moved from local exchanges into personal wallets as people looked for ways to safeguard savings.

Iran Protests Push People Toward Bitcoin

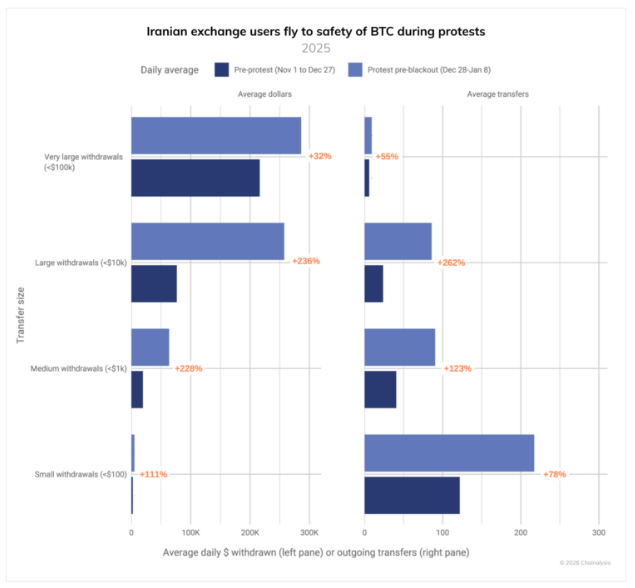
Based on reports, Bitcoin withdrawals from Iranian exchanges rose noticeably during the unrest. Some transfers happened in short, intense bursts when internet access was still available.

Many Iranians chose self custody — sending crypto to private wallets rather than keeping it on exchanges — as the rial lost value and access to traditional finance tightened.

Inflation in the country was reported at about 40–50% in recent months, which helped push more households to seek alternatives for storing value.

Source: Chainalysis

State Actors And Civilian Use Diverge

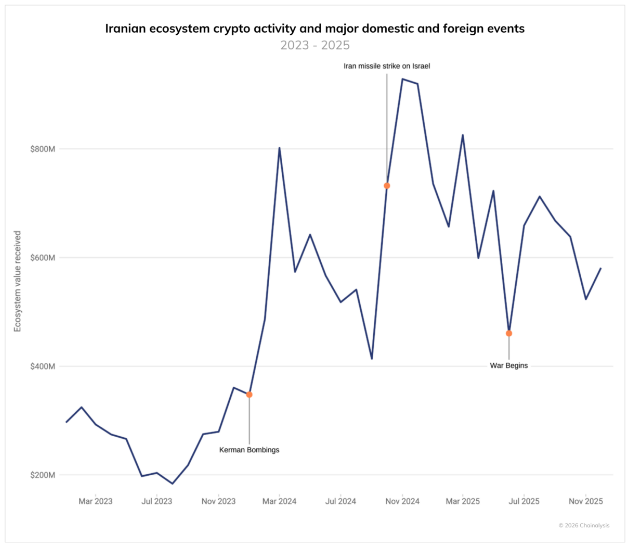
Chainalysis data shows complexity in the flows. Addresses linked to the Islamic Revolutionary Guard Corps were tied to roughly half of the total crypto volume received in Iran during Q4 2025.

That does not mean ordinary use did not rise — it did. But the numbers point to crypto serving different roles at once: it can be a shelter for households when local currency collapses, and it can be a channel for state-linked actors to move funds. Analysts warn that these two uses can mask one another in on-chain tallies.

Daily crypto transfers and total transaction volumes have jumped sharply during periods of unrest in Iran.
Source: Chainalysis

Economic Fear Meets Practical Steps

People acted quickly. When banks and payment systems were uncertain or blocked, crypto offered a way to move value across borders without the usual banking rails.

Some transfers were small. Others were larger, tied to families or businesses trying to protect capital. According to the sources, these spikes in activity coincided with other significant occurrences involving geopolitical crises and specific cyber attacks that contributed to the erosion of faith in the local infrastructure.

BTCUSD trading at $95,642 on the 24-hour chart: TradingView

Internet Blackouts Drive Self Custody

The Iranian government has imposed internet blackouts in response to the escalating protests. By controlling the online access, Iranians resorted to the windows of opportunity to transfer money. The transfer of money to private accounts became a common practice during the online windows.

That pattern — brief but intense bursts of withdrawals — shows how people adapt quickly to changing conditions. It also explains why on-chain volume readings jumped so high in 2025.

What The Numbers Suggest

The $7.78 billion number measures on-chain crypto volume tied to Iranian activity over the year, not the market value of holdings inside the country. Based on reports, that figure captures a mix of ordinary transfers, commercial activity, and movements linked to sanctioned entities.

Featured image from Stringer/Via Reuters, chart from TradingView

Editorial Process for bitcoinist is centered on delivering thoroughly researched, accurate, and unbiased content. We uphold strict sourcing standards, and each page undergoes diligent review by our team of top technology experts and seasoned editors. This process ensures the integrity, relevance, and value of our content for our readers.

Here’s Why Bitcoin is a Better Scarce Asset Than Gold: Ark Invest’s Cathie Wood

0

In brief

  • Ark Invest has published its 2026 Outlook report, in which CEO Cathie Wood flags Bitcoin as a better asset for portfolio diversification as she sounds the alarm on gold’s rally.
  • Wood’s preference for Bitcoin is driven by its algorithmically fixed supply, unlike gold, whose miners can increase production in response to high prices.
  • Bitcoin maintains an extremely low correlation with other major assets, making it a powerful diversification tool, especially in a currency-revaluation environment, Wood said.

Bitcoin’s mathematically capped supply makes it a superior scarce asset to gold in an era of rising institutional demand, according to Ark Invest founder and CEO Cathie Wood.

In her “2026 Outlook” report, Wood analyzes the recent divergence between the two assets.

Gold vs. Bitcoin 

While gold surged 65% in 2025, Bitcoin declined 6%. Wood attributes gold’s 166% rally since October 2022 not to inflation fears, but to “global wealth creation” outpacing the metal’s modest ~1.8% annual supply growth.

“The incremental demand for gold could be outstripping its supply growth,” she wrote. Bitcoin, however, presents a fundamentally different supply dynamic.

“Gold miners, by boosting production of gold, can do something not possible with Bitcoin,” Wood notes. “Bitcoin is mathematically metered to increase ~0.82% per year for the next two years, at which point its growth will decelerate to ~0.41% per year.”

This inelastic supply schedule means that any surge in demand—such as continued inflows into spot ETFs—would have a more potent effect on Bitcoin’s price. “If Bitcoin demand continues to increase, the bellwether crypto could benefit more than gold due to its mathematical nature,” the report suggests.

Bitwise CIO Matthew Hougan recently echoed this scarcity thesis, suggesting sustained institutional demand that outpaces supply could ignite a “parabolic blowoff” for Bitcoin.

“Bitcoin’s performance in 2025 looks weak in isolation, but context matters,” Georgii Verbitskii, Founder of TYMIO, told Decrypt. “In 2024, Bitcoin rose sharply… a period of consolidation the following year is not only normal but justified.”

Verbitskii agreed with Wood’s core structural argument, noting that “when capital rotates into hard assets during a global currency revaluation, Bitcoin belongs in that same category as gold.”

However, he highlighted a critical divergence, that gold miners can increase production when prices rise, but Bitcoin’s supply is fixed. “That asymmetry means that when demand returns, Bitcoin’s price reaction is structurally more explosive,” Verbitskii said.

Looking ahead

Wood’s analysis also places gold’s current rally in a sobering historical context.

The ratio of gold’s market capitalization to the M2 money supply has reached a level last seen in the early 1930s and 1980s—periods she describes as “extreme.” Historically, sustained declines from such peaks have coincided with strong equity market returns.

For allocators, Wood highlights a final, critical advantage: diversification.

The correlation between Bitcoin and gold is lower than that between the S&P 500 and bonds, she noted, concluding that Bitcoin “should be a good source of diversification for asset allocators looking for higher returns per unit of risk during the years ahead.”

“Looking into 2026, I don’t see this as a buy-or-sell question, but rather a hold question,” Verbitskii said. “Gold offers stability, Bitcoin offers asymmetric upside. Historically, Bitcoin has grown faster than gold, and I expect that pattern to continue.”

Daily Debrief Newsletter

Start every day with the top news stories right now, plus original features, a podcast, videos and more.

Inside Stripe’s Crypto Strategy with Privy CEO: Wallets as Global Financial Accounts and the End of Decentralization Dogmas

0

Stern says Privy underpins Stripe’s stablecoin stack — and argues crypto needs better trade-offs, not absolutism.

As payment giant Stripe continues to move deeper into crypto, Privy CEO and co-founder Henri Stern says the biggest barrier to adoption isn’t regulation or scaling, but the lack of compelling products. Embedded wallets, he argues, can bridge that gap by making digital assets usable inside everyday applications.

In an exclusive interview with The Defiant founder Camila Russo, Stern explained how Privy fits into Stripe’s broader crypto plans, which now include stablecoins, wallet tools, and its own blockchain efforts. Privy is a developer-focused embedded wallet platform, which Stripe acquired back in June.

Privy’s CEO also pushed back on what he sees as crypto’s habit of framing concepts like decentralization, trustlessness, and custody as binary outcomes rather than design trade-offs — an approach he says has often come at the expense of real security and user adoption.

Stripe Integrates Crypto Rails

Stripe processed $1.4 trillion in payments volume in 2024 and has pushed further into crypto in 2025. The company launched Stablecoin Financial Accounts in May, which let users in more than 100 countries send, receive, and hold stablecoins.

In June, Stripe made another strategic move into crypto infrastructure by acquiring Privy. The deal marked Stripe’s commitment to bridging traditional fintech and on-chain rails by bringing self-custodial crypto-native infrastructure into its product suite.

Stripe acquired Privy following the fintech giant’s $1.1 billion acquisition of stablecoin platform Bridge in February 2025, marking the company’s largest purchase to date and a major step in its push into crypto and stablecoin infrastructure.

In September, Stripe and crypto venture firm Paradigm unveiled Tempo, an EVM-compatible Layer 1 blockchain built for high-volume payments. Tempo has not launched on mainnet yet, but it is expected to include a built-in stablecoin trading system.

Stern said these efforts reflect a broader shift inside Stripe, where crypto is no longer confined to a single team but increasingly embedded across product, legal, and engineering groups evaluating how on-chain rails could serve global users.

Privy’s Role in Stripe

Inside Stripe, Privy has taken on a dual role, powering core wallet infrastructure and serving as an internal expertise hub on digital assets, helping coordinate crypto efforts across legal, engineering, and product teams.

Stern said Privy is “the backbone of that stablecoin stack,” helping Stripe power new crypto features for its users. Privy also supports Stripe’s broader work with crypto companies, including access to decentralized finance (DeFi) and building what he described as the “core control plane for digital assets.”

That positioning reflects Privy’s origin as developer infrastructure rather than a consumer wallet, a distinction Stern says is critical to making crypto usable at scale without forcing users to manage private keys, browser extensions, or recovery phrases on day one.

Stern on Tempo

Stern framed Tempo as an example of why specialization matters as crypto infrastructure matures. Rather than viewing new blockchains as unnecessary fragmentation, he argued that payments-focused chains can succeed by optimizing for a specific set of constraints, like high throughput, predictable fees, and developer-friendly abstractions, in the case of Tempo.

Stern argued that while similar functionality could theoretically be built elsewhere, the real question for developers is whether they want to assemble and maintain that stack or rely on purpose-built rails that “just work” for payments at scale. In that sense, Tempo reflects a broader shift toward infrastructure designed around concrete use cases.

Users, Not Ideology

Privy is built to make crypto feel less complicated for users, with Stern describing the company as an “embedded wallet software solution” that lets developers “spin up and host self-hosted wallets as part of their applications.”

This comes as most users still have to download a separate wallet app or browser extension, save a recovery phrase, and buy tokens to pay for gas before they can use many blockchain products.

Stern said this friction has held back otherwise promising crypto products, arguing that many teams have prioritized architectural purity over meeting users where they are.

Privy, he explained, starts with security, then balances usability with user control. “We’re trying to set a floor for security,” Stern told The Defiant. “And then from there we’re optimizing for UX and self custody.”

Rather than treating custody or decentralization as absolutes, Stern described them as design choices that exist along a spectrum, one that developers must navigate based on their users’ needs, threat models, and regulatory constraints.

He added that Privy wallets can support different use cases, including user wallets, developer-controlled wallets, and treasury use cases for companies. The goal is to keep giving developers more flexibility while keeping assets “under the user’s control with the user’s consent,” Stern said.

Looking ahead, Stern said he expects wallets to increasingly function as global financial accounts — interoperating with both traditional banking systems and on-chain applications — as more fintechs experiment with stablecoins, programmable money, and crypto-native settlement layers.

Bitcoin’s renewed push to $100K sparked by fresh institutional demand

0

Sustained US Bitcoin ETF inflows are supporting prices near $97,000, raising questions about whether institutional demand is reshaping Bitcoin’s market cycle.

11 EH/s: Bitmain Eyes a New Bitcoin Mining Proxy? – Miner Weekly

0

While most attention in recent months has focused on publicly traded miners racing to add hashrate or pivot toward AI, one of the fastest-growing bitcoin mining operations has expanded largely outside the spotlight. This article first appeared in Miner Weekly, Blocksbridge Consulting’s weekly newsletter curating the latest news in bitcoin mining and data analysis from […]

Korea University Blockchain Institute Partners With Injective as Validator in Global Ecosystem

0

Korea University’s Blockchain Research Institute has partnered with Injective, joining its global ecosystem as a validator to strengthen ties between academia and the blockchain industry. Validator Participation and Network Security Korea University’s Blockchain Research Institute has partnered with layer 1 blockchain, Injective, formally joining the global Injective ecosystem in a move that strengthens ties between […]