Executives at Coinbase used a recent company ‘AMA’ call to address growing scrutiny around Bitcoin exchange-traded funds, defending the firm’s dominant role as a custodian and pushing back against claims that spot Bitcoin ETFs are backed by “paper Bitcoin” rather than real assets.
Responding to a question from Bloomberg’s James Seyffart, Coinbase CEO Brian Armstrong said the company holds a commanding share of the U.S.-listed Bitcoin ETF custody market, estimating Coinbase’s share at more than 80%. He framed that concentration as a competitive advantage rather than a risk.
“We do have pretty dominant market share in terms of custody for the ETFs. I see that as a strength. We’re the trusted counterparty on the institutional side. I think we’re far ahead there, and it’s a great business for us,” Armstrong said on the call.
He acknowledged concerns about concentration risk but noted that large ETFs often diversify custodians as assets scale, which has allowed competitors to gain limited market share over time.
Armstrong said Coinbase remains the dominant custodian for U.S. bitcoin ETFs, with roughly “80% plus market share,” while noting that larger funds often diversify custodians as they scale, a shift he called “healthy and good.”
Armstrong touched on the security of Coinbase’s custody infrastructure, pointing to cold storage systems that are regularly penetration tested and audited.
He said Coinbase has secured patents related to its custody technology and employs cryptographers to harden defenses against attacks. Large financial institutions and government clients also conduct their own audits, he added.
When Seyffart asked about sentiment circulating on social media that Bitcoin ETFs are not fully backed by real Bitcoin. Armstrong said he does not understand where those concerns originate, reiterating that spot Bitcoin ETFs are required to be fully backed by the underlying asset.
Coinbase CFO Alesia Haas offered more detail, explaining that critics are often calling for public “proof of reserves,” such as disclosure of on-chain wallet addresses tied to ETF holdings. Haas said Coinbase does not disclose client wallet addresses for security and confidentiality reasons, but stressed that ETF issuers and custody clients can independently verify their assets on-chain.
Haas said the custody business is ‘separately audited,’ noting that Coinbase produces SOC 1 and SOC 2 reports that demonstrate controls are in place and operating effectively.
Those audits reconcile holdings back to the blockchain and confirm that assets are segregated by clients, including ETF issuers.
Haas said every custody client can see its assets on-chain and knows the addresses associated with its holdings. “We would never disclose addresses that we hold on behalf of clients,” she said, adding that Coinbase could explore tools that allow clients to disclose proof of reserves themselves if they choose.
Coinbase executives touch on the Clarity Act
Later on in the call, Armstrong and Haas addressed regulatory developments around Coinbase’s stance on proposed U.S. crypto market structure legislation often referred to as the CLARITY Act.
Armstrong pushed back on claims that Coinbase withdrew support for the bill, saying the company objected to the specific draft that it viewed as unworkable.
Coinbase has spent more than $100 million over several years advocating for regulatory clarity, Armstrong said, arguing that earlier drafts made concessions to traditional financial trade groups that could stifle crypto innovation.
He said negotiations are ongoing and that lawmakers, regulators, and industry participants remain engaged.
Armstrong said the company expects a market structure bill to pass and argued that statutory clarity would provide long-term certainty beyond shifting leadership at agencies like the SEC. If legislation stalls, he said Coinbase would continue operating under existing rules while seeking clarity through regulators or the courts.
“I think the bill will get done,” Armstrong said. “It’s in everyone’s interest at this point.”
Bitcoin (BTC) analysts mapped out the key BTC price levels to watch as the market’s focus shifted to the $58,000 to $65,000 zone as the last line of defense.
Bitcoin price is wedged between two key levels
Bitcoin is currently wedged between the 200-week simple moving average (SMA) at $68,300 and the 200-week exponential moving average (EMA) at $58,400.
Generally, in Bitcoin’s trading history, major BTC bottoms have formed between the 200-week SMA and EMA, according to analyst Jelle. This suggests that Bitcoin is possibly forming a bottom between these trendlines.
Related: Bitcoin accumulation wave puts $80K back in play: Analyst
While Bitcoin has produced a weekly close above the 200-week EMA for the second week in a row, “this doesn’t mean it is now in the clear,” trader and analyst Rekt Capital said in a Monday X post, adding:
“The absence of any meaningful upside from here going forward, there is a risk that BTC loses the 200-week EMA in time, triggering additional downside.”
BTC/USD weekly chart. Source: Rekt Capital
Crypto investor and entrepreneur Ted Pillows had an expanded view, focusing on $71,000 for a bullish breakout.
In a Tuesday post on X, Ted Pillows said that Bitcoin needs a daily close above the $71,000 level to increase the chances of an upside rally, adding:
“And if a breakdown happens below $66,000, BTC might revisit $60,000.”
BTC/USD two-day chart. Source: Ted Pillows
Cointelegraph reported that the CME gap between $80,000 and $84,000 could act as a magnet, representing the upper price target for Bitcoin. With nine out of 10 CME gaps filled since August 2025, the $80,000–$84,000 range stands out as the key level to watch on the upside.
Bitcoin bulls must hold the price above $65,000
After turning away from $72,000 last week, Bitcoin found support at $65,000. Glassnode’s cost basis distribution heatmap reveals a significant support area recently established from $63,000 to $65,000, where long-term holders recently acquired approximately 372,240 BTC.
A decisive break below this level “would likely open the path toward the realized Price” around $55,000, Glassnode said in a Monday post on X.
Bitcoin cost basis distribution heatmap. Source: Glassnode
Current analysis suggests that the bears may aim to hold BTC price below $65,000 to remain in control. If they succeed, the BTC/USDT pair may then retest the critical $60,000 level. If the $60,000 support cracks, the next stop is likely to be $52,500.
This article does not contain investment advice or recommendations. Every investment and trading move involves risk, and readers should conduct their own research when making a decision. While we strive to provide accurate and timely information, Cointelegraph does not guarantee the accuracy, completeness, or reliability of any information in this article. This article may contain forward-looking statements that are subject to risks and uncertainties. Cointelegraph will not be liable for any loss or damage arising from your reliance on this information.
The Federal Reserve is seen as a last stronghold against political pressure on interest rates. Shrinking the Fed’s balance sheet may impact risk markets. Kevin Warsh’s past monetary policy judgments are viewed critically.
Key takeaways
The Federal Reserve is seen as a last stronghold against political pressure on interest rates.
Shrinking the Fed’s balance sheet may impact risk markets.
Kevin Warsh’s past monetary policy judgments are viewed critically.
Warsh’s monetarist views lead him to fear inflation from Fed balance sheet expansions.
Current labor market conditions and productivity gains are leading to expectations of rate cuts.
Quantitative easing does not guarantee inflation due to varying money velocity.
The Fed stopped targeting money supply because it was ineffective.
QE affects financial asset prices more than the private sector’s purchasing power.
There’s a distinction between financial inflation and main street inflation, driven by QE.
The central bank and commercial banks can create credit, impacting liquidity in non-banking sectors.
Political dynamics influence the Federal Reserve’s independence.
Monetary policy changes can have significant market stability consequences.
Warsh’s potential impact on future monetary policy is under scrutiny.
Guest intro
Joseph Wang is the CIO at Monetary Macro and principal of FedGuy.com. He previously served as a senior trader on the Federal Reserve Bank of New York’s Open Markets Desk, where he implemented monetary policy. He is the author of the bestselling book Central Banking 101.
The Federal Reserve’s role against political pressure
The Federal Reserve is becoming the last stronghold against political pressure regarding interest rates.
— Joseph Wang
The president has joked about suing the Fed if rates aren’t cut, highlighting political tensions.
Understanding the Fed’s independence is crucial for grasping current monetary policy debates.
Political influence challenges the Fed’s ability to maintain independent monetary policy.
The Fed’s resistance is seen as vital for maintaining economic stability.
I kind of get the sense that the federal reserve is kind of the last bastion of the resistance.
— Joseph Wang
The Fed’s role is critical in balancing political and economic pressures.
Central bank independence is a cornerstone of effective monetary policy.
Impact of shrinking the Fed’s balance sheet
Shrinking the Federal Reserve’s balance sheet will likely impact risk markets.
— Joseph Wang
Reducing the balance sheet could lead to increased market volatility.
Investors need to be aware of potential changes in market dynamics.
The balance sheet reduction is a key focus for future monetary policy.
My base case is it’s not easy to shrink this without having an impact on risk markets.
— Joseph Wang
Understanding balance sheet policies is crucial for financial market participants.
The Fed’s actions may have unintended consequences on market stability.
Market participants should prepare for potential disruptions from policy changes.
Kevin Warsh’s monetary policy views
Kevin Warsh has consistently exhibited poor judgment on monetary policy.
— Joseph Wang
Warsh’s hawkish stance is a key aspect of his economic perspective.
His past roles provide insight into his potential future policy decisions.
Warsh’s monetarist view leads him to fear inflation from Fed balance sheet expansions.
He’s someone who has consistently exhibited not very good judgment on monetary policy.
— Joseph Wang
Understanding Warsh’s views is important for assessing his impact on the Fed.
His nomination could shift the Fed’s policy direction.
Warsh’s approach may influence future monetary policy debates.
Labor market and productivity’s influence on rate cuts
The current labor market conditions and productivity boom are leading to expectations of rate cuts.
— Joseph Wang
A weak labor market and productivity gains are seen as disinflationary.
Rate cuts are expected to support economic growth amid these conditions.
Understanding labor market dynamics is crucial for predicting monetary policy.
The labor market you know not doing that great and also we have this huge productivity boom.
— Joseph Wang
Productivity improvements may allow for more accommodative monetary policy.
Economic indicators are key to understanding rate cut expectations.
The Fed’s policy decisions are influenced by labor and productivity data.
The complexities of quantitative easing
Quantitative easing does not guarantee inflation due to the time-varying nature of money velocity.
— Joseph Wang
QE’s effectiveness depends on the velocity of money, not just money supply.
The Fed’s balance sheet expansion doesn’t directly lead to inflation.
Understanding QE’s mechanics is crucial for grasping its economic impact.
The velocity of money was something that was time varying.
— Joseph Wang
QE’s effects on inflation are more complex than commonly assumed.
The relationship between money supply and inflation is not straightforward.
QE’s role in monetary policy requires careful analysis.
The Fed’s shift away from money supply targeting
The Federal Reserve discontinued targeting the money supply because it was ineffective.
— Joseph Wang
The shift reflects a change in the Fed’s approach to monetary policy.
Historical policy changes impact current economic understanding.
The fed also discontinued targeting the money supply because they realized that it doesn’t work.
— Joseph Wang
The Fed’s strategies have evolved over time to address economic challenges.
Understanding past policy shifts is important for current monetary policy analysis.
The Fed’s focus has shifted to other economic indicators.
QE’s impact on financial asset prices
Quantitative easing (QE) primarily affects financial asset prices rather than increasing the purchasing power of the private sector.
— Joseph Wang
QE changes asset composition, not private sector purchasing power.
The policy’s impact is more pronounced in financial markets.
Fed prints a lot of money but you know you don’t really it doesn’t increase the purchasing power of the private sector.
— Joseph Wang
Understanding QE’s effects on asset prices is crucial for investors.
The policy’s role in financial markets is a key focus for the Fed.
QE’s impact on the real economy is limited compared to financial markets.
The Fed’s actions influence asset prices more than consumer spending.
Distinction between financial and main street inflation
There is a distinction between financial inflation and main street inflation, with QE effectively driving financial asset inflation without corresponding main street inflation.
— Joseph Wang
QE’s effects are more pronounced in financial markets than in the broader economy.
Understanding inflation types is crucial for policy discussions.
There’s this important distinction between… financial inflation and main street inflation.
— Joseph Wang
The Fed’s policies have different impacts on various sectors of the economy.
QE’s role in financial asset inflation is a key consideration for policymakers.
The distinction influences public understanding of inflation.
Policy discussions must address the different types of inflation.
Credit creation and liquidity impacts
The central bank and commercial banking system can create credit out of thin air, impacting liquidity in non-banking sectors.
— Joseph Wang
Credit creation by banks influences economic liquidity.
The mechanism is crucial for understanding monetary policy effects.
The central bank and the commercial banking system have elastic balance sheets.
— Joseph Wang
Banks’ ability to create credit affects liquidity in the economy.
Understanding credit creation is important for analyzing economic conditions.
The interaction between banks and the economy is a key focus for the Fed.
Credit creation’s impact on liquidity is a fundamental economic concept.
Decentralized lending protocol ZeroLend says it is shutting down completely after the blockchains it operates on have suffered from low user numbers and liquidity.
“After three years of building and operating the protocol, we have made the difficult decision to wind down operations,” ZeroLend’s founder, known only as “Ryker,” said in a post the protocol shared to X on Monday.
“Despite the team’s continued efforts, it has become clear that the protocol is no longer sustainable in its current form,” he added.
ZeroLend focused its services on Ethereum layer-2 blockchains, once touted by Ethereum co-founder Vitalik Buterin as a central part of the network’s plan to scale and remain competitive.
However, Buterin said earlier this month that his vision for scaling with layer 2s “no longer makes sense,” that many have failed to properly adopt Ethereum’s security, and that scaling should increasingly come from the mainnet and native rollups.
ZeroLend operated at loss due to illiquid chains, says Ryker
ZeroLend’s Ryker said the reason for the shutdown is that several blockchains the protocol supported “have become inactive or significantly less liquid.”
He added that in some cases, oracle providers — services that fetch data and are often crucial to running protocols — have stopped support on some networks, making it “increasingly difficult to operate markets reliably or generate sustainable revenue.”
Source: ZeroLend
“At the same time, as the protocol grew, it attracted greater attention from malicious actors, including hackers and scammers,” Ryker said. “Combined with the inherently thin margins and high risk profile of lending protocols, this resulted in prolonged periods where the protocol operated at a loss.”
He added that the protocol will ensure users can withdraw their assets, adding, “We strongly encourage all users to withdraw any remaining funds from the platform.”
Ryker said some user funds may be locked on blockchains that have seen “significantly deteriorated” liquidity, and ZeroLend will upgrade the protocol’s smart contracts with the aim of redistributing stuck assets.
Related: TradFi giant Apollo enters crypto lending arena via Morpho deal
He added that ZeroLend has also been working to trace and recover funds tied to an exploit in February last year, where protocol users of a Bitcoin (BTC) product on the Base blockchain were exploited after an attacker drained lending pools.
Ryker said that suppliers of the product affected by the incident will receive a partial refund funded by an airdrop allocation received by the ZeroLend team.
At its height in November 2024, ZeroLend commanded a total value locked of nearly $359 million, but that has since sunk to $6.6 million, according to DefiLlama.
The ZeroLend (ZERO) token has fallen by 34% in the last 24 hours in reaction to the protocol’s shutdown and has also lost nearly all its value since hitting a peak of one-tenth of a cent in May 2024, according to CoinGecko.
Magazine: Ethereum’s Fusaka fork explained for dummies — What the hell is PeerDAS?
Cointelegraph is committed to independent, transparent journalism. This news article is produced in accordance with Cointelegraph’s Editorial Policy and aims to provide accurate and timely information. Readers are encouraged to verify information independently. Read our Editorial Policy https://cointelegraph.com/editorial-policy
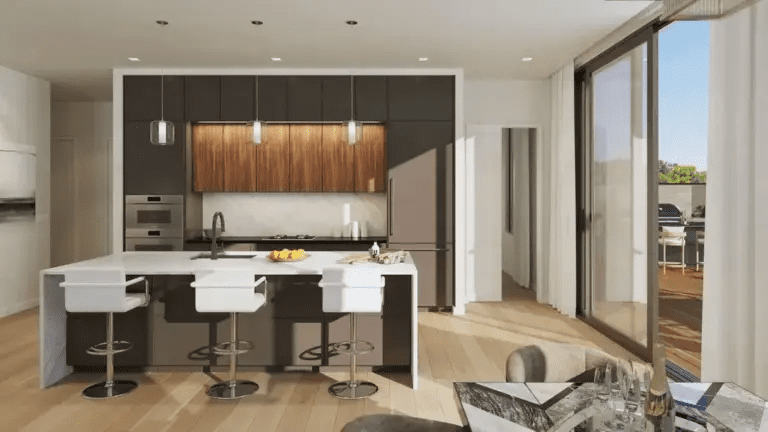
As part of the full interior package, German Kitchen Center is supplying all kitchens, bathroom vanities, and laundry rooms across the building. Unlike traditional condo developments that often avoid customization due to logistical complexity, Avraham’s model leverages GKC’s specialized systems to manage upgrades without disrupting construction timelines.
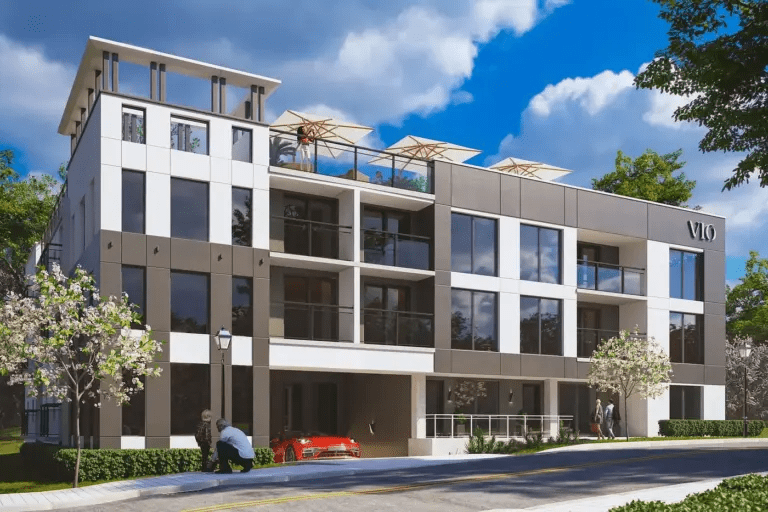
VIO
“My non-negotiable is that the product has to feel intentional… an experience that makes buyers feel like they’re stepping into a real home,” said Roni Avraham. “GKC brought systems, structure, and a buyer-facing experience that reduced risk for the development and improved the purchase experience.”
German Kitchen Center
The project, known as VIO, has seen a significant market response to this flexibility. The majority of buyers have opted to upgrade their selections, helping the project stand out in the luxury market and move units faster than standard “one-size-fits-all” developments. By working directly with the GKC design team, buyers receive a professional, tailored experience that elevates the perceived value of the entire building.
This successful model demonstrates that structured customization through a trusted partner serves as a competitive advantage for developers while delivering a superior final product for homeowners.
Roni Avraham
About Roni Avraham:
Roni Avraham is a real estate developer specializing in boutique luxury residential projects in Georgia and Florida. His focus is on creating curated, high-quality environments characterized by intentional design and premium materials. For more information, visit Roni Avraham’s Website or follow him on LinkedIn.
About German Kitchen Center:
German Kitchen Center is a leading provider of comprehensive kitchen and interior systems. GKC offers a complete system, including design, planning, and coordination for residential condominium projects, specializing in high-end European cabinetry and structured upgrade pathways for developers.
You can also visit my Medium post: https://marcoderhy.medium.com/roni-avrahams-boutique-condo-success-with-german-kitchen-center-cf2a1bdbce64?postPublishedType=initial
Bitcoin’s (BTC) price continued to consolidate near $68,000 on Tuesday, but sustained weakness below this level may generate additional sell pressure from the newest cohort of large holders.
While the long-term whales remain in profit, short-term whales are sitting on sizeable unrealized losses. One analyst highlighted how this pressure may impact BTC’s price, as other indicators point to a continued downtrend.
Key takeaways:
The short-term Bitcoin whales are sitting on net unrealized losses of 22% at current prices.
The Binance whale inflow ratio climbed to 0.62 from 0.4 in two weeks, signaling a rise in the large-holder deposits.
Long-term whales control 71% of the large-wallet supply and remain in profit above their realised price of $41,626.
New BTC whales face mounting unrealized losses
Market analyst Carmelo Alemán noted that the wallets holding 1,000–10,000 BTC control 4.483 million BTC at the moment. 1.287 million BTC (28.7%) belongs to the short-term holder (STH) whales, while 3.196 million BTC (71.3%) sits with the long-term holder (LTH) whales.
The cost basis gap is significant. STH whales have a realized price of $88,494, carrying an unrealized loss of 22%. LTH whales hold a realized price of $41,626, maintaining a 65% in profit.
Bitcoin realized price of new and old whales. Source: CryptoQuant
Alemán explained that this asymmetry shows the recent whale holders are under pressure while older capital retains a large cushion.
However, realized losses among STH whales have remained limited since Bitcoin’s all-time high of $126,000 in October 2025, reflecting resilience from the holders.
The key structural level remains near $41,626, which is the LTH realized price. As long as BTC holds above it, the data reflects redistribution rather than structural capitulation, the analyst said.
Related: Ray Dalio’s world order warning revives case for Bitcoin as neutral money
BTC whale deposits increase as pressure on long-term holders builds
The Binance whale inflow ratio, measuring the share of the 10 largest BTC deposits relative to total inflows, rose to 0.62 from 0.4 between Feb. 2 and 15. A higher ratio suggests a growing whale-driven sell-side activity.
Whale inflow ratio on Binance. Source: CryptoQuant
Crypto analyst Darkfost said that a part of the flow is linked to the “Hyperunit whale,” believed to be Garrett Jin, who moved close to 10,000 BTC onto Binance.
LTH’s spent output profit ratio (SOPR) also dropped to 0.88. SOPR measures whether the coins are being sold at a profit or loss, with a reading below 1 meaning losses are being realized. The monthly average SOPR remains at 1.09, and the annual average stands at 1.87, indicating that long-term profitability is still intact.
Additionally, Alphractal founder Joao Wedson said that the long-term holder net-unrealized profit/loss (NUPL) stands at 0.36, meaning unrealized profits remain positive.
The analyst said that the past cycle bottoms formed only after the metric turned negative, implying Bitcoin may still need another dip to confirm capitulation among the LTH cohorts.
Related: Bitcoin weekly RSI echoes mid-2022 bear market as BTC plays liquidity games
This article does not contain investment advice or recommendations. Every investment and trading move involves risk, and readers should conduct their own research when making a decision. While we strive to provide accurate and timely information, Cointelegraph does not guarantee the accuracy, completeness, or reliability of any information in this article. This article may contain forward-looking statements that are subject to risks and uncertainties. Cointelegraph will not be liable for any loss or damage arising from your reliance on this information.
Bitcoin navigated an uneasy range between $67,000 and $69,000 as extreme market fear weighed on sentiment. Despite briefly reclaiming the $69,000 level, the price retreated to a session low of $66,557. Even Strategy’s $168 million acquisition of 2,486 bitcoins, which grew its total holdings to 717,131 coins, failed to ignite any meaningful bullish momentum. Strategy […]
Mass texting has long been a powerful communication tool for businesses, nonprofits, and organizations looking to reach large audiences quickly. But in the age of artificial intelligence, these platforms are undergoing a remarkable transformation. AI is reshaping how messages are created, delivered, and optimized, making mass texting more personalized, efficient, and strategic than ever before. As organizations look for ways to stay competitive and connect meaningfully with their audiences, understanding how AI is influencing mass texting platforms can help them make smarter communication decisions.
Smarter Personalization Through AI-Driven Insights
One of the most significant advancements in mass texting platforms is the ability to personalize messages at scale. AI analyzes user behavior, preferences, and past interactions to help organizations craft messages that feel more relevant and timely. Instead of sending the same generic text to thousands of people, businesses can now tailor content based on demographics, engagement patterns, or purchase history. This level of personalization increases the likelihood that recipients will read and respond to messages, strengthening customer relationships and improving overall communication effectiveness.
Deliverability is a critical factor in mass texting success, and AI is playing a major role in improving it. AI-powered systems can analyze delivery rates, carrier responses, and user engagement to determine the best times to send messages and the most effective formats to use. These insights help organizations avoid common pitfalls such as message throttling or carrier filtering. Additionally, AI can identify patterns that indicate when recipients are most likely to engage, allowing businesses to optimize their messaging schedules for maximum impact. This data-driven approach ensures that messages reach their intended audience quickly and reliably.
Advanced Compliance and Security Features
As regulations around digital communication continue to evolve, compliance has become a top priority for organizations using mass texting platforms. AI is helping to simplify this process by automatically monitoring message content, opt-in status, and consent records. These systems can flag potential compliance issues before messages are sent, reducing the risk of violations. AI also enhances security by detecting unusual activity, preventing unauthorized access, and safeguarding sensitive data. With these advanced protections in place, organizations can communicate confidently while maintaining trust with their audiences.
More Meaningful Engagement Through Conversational AI
Another major evolution in mass texting platforms is the rise of conversational AI. Instead of relying solely on one-way messages, organizations can now engage in dynamic, two-way conversations with their audiences. AI-powered chat tools can answer questions, provide support, and guide users through processes such as scheduling or purchasing. This conversational approach makes mass texting more interactive and user-friendly, helping organizations build stronger connections and deliver better customer experiences. As conversational AI becomes more sophisticated, these interactions will feel increasingly natural and intuitive.
Conclusion
AI is reshaping the landscape of mass texting, making platforms smarter, more efficient, and more responsive to user needs. From advanced personalization and automation to improved deliverability, compliance, and conversational capabilities, AI-driven innovations are helping organizations communicate more effectively than ever before. As these technologies continue to evolve, mass texting will remain a vital tool for reaching audiences quickly and meaningfully in an increasingly digital world.
Markets head into this week navigating a familiar cross-current: geopolitics setting the floor for energy, while U.S. inflation and growth data determine how much room the Federal Reserve has to turn dovish.
The immediate catalyst is a second round of indirect U.S.–Iran nuclear talks in Geneva on Tuesday, as tensions around the Strait of Hormuz keep traders alert to headline risk. Iran staged drills near the key shipping lane as negotiations began, showing why crude has stayed sensitive to diplomatic signals even as broader demand and supply fundamentals remain mixed.
Oil: diplomacy as the marginal driver
Oil markets are treating the Geneva discussions as the week’s highest-beta event. Brent traded around the high-$60s a barrel in early Tuesday dealing, with WTI near the low-$60s, reflecting a risk premium that tends to rise quickly when Middle East shipping routes are in focus.
The price action can be seed as less about near-term balances and more about the probability distribution around sanctions enforcement, potential supply disruptions, and—at the optimistic end—de-escalation that could relax constraints. Citi has argued geopolitics is likely to support crude in the near term, but sees scope for prices to drift lower later in 2026 if conflict risks cool and additional supply comes through.
That setup matters beyond energy: oil is the most direct channel through which geopolitics can leak into inflation expectations—especially at a moment when the market is trying to price the Fed’s next move with more confidence.
The U.S. macro “data dump”: minutes, PCE, and delayed GDP
On the macro side, the central issue is whether incoming U.S. data validate the market’s easing bias or force a re-pricing of the first cut.
The Fed will publish minutes from the Jan. 27–28 meeting on Wednesday, Feb. 18, a release that often clarifies how broadly the committee shares concerns about growth versus inflation persistence.
Then Friday, Feb. 20 brings an unusually consequential pairing: the advance estimate of fourth-quarter 2025 GDP and the Personal Income and Outlays report that contains the Fed’s preferred inflation gauge, the PCE price index. The Bureau of Economic Analysis rescheduled both releases to Feb. 20 after they were originally slated for late January, turning Friday into a focal point for rates and FX markets.
In practice, traders will treat the trio—minutes, GDP, PCE—as a single narrative test: does disinflation remain intact without a sharp growth downshift, or is the economy still running hot enough to keep policy restrictive longer?
Rates, FX and equities: why positioning feels fragile
Thin liquidity in parts of Asia due to Lunar New Year closures has already left cross-asset markets more headline-sensitive, with investors cautious ahead of both the Geneva talks and U.S. releases.
In that environment, the dollar and front-end rates can overshoot on surprises. A softer-than-expected PCE print, or minutes that emphasize downside risks, would typically reinforce rate-cut pricing—pressuring the dollar and easing financial conditions. Conversely, stronger inflation or more hawkish minutes can re-steepen the “higher for longer” tail risk, tightening conditions quickly.
That sensitivity is showing up most clearly in gold—an asset that trades as a real-rate proxy as much as a geopolitical hedge.
Gold: above $5,000 as a battleground, but not a straight line
Gold has been consolidating around the $5,000/oz region after a powerful run, with Tuesday’s trade highlighting how quickly the metal can slip when the dollar firms and haven demand pauses. Spot gold fell to the high-$4,900s on Feb. 17, driven by both a stronger dollar and reduced participation from major Asian markets during the holiday period.
The chart logic around the big round number has become part of the narrative. A sustained move above $5,100 is increasingly viewed as a trigger for trend-following inflows, while breaks below $5,000 raise the probability of a deeper retracement into the high-$4,800s—levels. And, this can be the next meaningful support zone in a post-rally normalization.
Lukman Otunuga, senior market analyst at FXTM, argued the interaction between U.S. data and geopolitics could set the tone across assets, saying: “This week’s US data and US-Iran talks could be decisive for markets. A solid PCE print and GDP could reinforce dovish rate-cut bets, pressuring the dollar while supporting gold and US equities.” He added that “Gold remains well-supported above $5,000, but volatility may persist given thin liquidity in China and geopolitical uncertainty. Traders should expect swings across FX, equities, and crypto.”
The key nuance: gold’s reaction function is not purely “risk-off.” If oil headlines push inflation expectations higher, that can lift nominal yields and complicate gold’s path even as geopolitical demand improves. Conversely, if diplomacy calms oil and PCE cools, gold can rally on easing real yields even with less overt haven demand. That’s why this week’s mix—Geneva plus PCE—has outsize influence.
Bitcoin: macro-sensitive, but trading its own levels
Bitcoin has been hovering around $68,000, with traders mapping $60,000 as a consequential liquidation and positioning level after the market’s sharp pullback from late-2025 highs.
Bitcoin is down 1.22% to $67,870 in 24h, closely tracking a 0.94% drop in the total crypto market cap, according to CoinMarketCap Bitcoin data.
The near-term dynamic resembles a macro “risk barometer”: easier financial conditions and a softer dollar tend to help crypto, while firmer yields and a resurgent dollar raise the hurdle for sustained upside. At the same time, crypto microstructure can dominate over short windows—particularly if leveraged positioning clusters around round-number supports.
That makes Friday’s U.S. releases and Wednesday’s Fed minutes relevant not because they “predict” bitcoin, but because they can shift the broader liquidity regime that crypto often amplifies. A dovish interpretation of the data can ease the pressure on high-beta assets; a hawkish surprise can revive the reflexive de-risking that pushes traders to defend well-watched downside levels.
The week’s takeaway
For investors, the most important point is sequencing. Tuesday’s Geneva headlines can move oil immediately, but the durability of those moves will depend on whether Friday’s PCE and GDP prints nudge the Fed narrative toward earlier cuts—or reinforce patience.
In other words, geopolitics may set the range, but U.S. macro is still the anchor for rates—and by extension the dollar, gold’s real-rate impulse, and the temperature of risk appetite that bleeds into equities and crypto.
The article “Will US-Iran Talks and US PCE Set the Tone for Oil, Gold and Bitcoin?” was first published on AlexaBlockchain. Read the complete article here: https://alexablockchain.com/Will-US-Iran-Talks-and-US-PCE-Set-the-Tone-for-Oil-Gold-Bitcoin/
Read Also: Is X’s InfoFi crackdown a necessary fix for spam—or a reminder that crypto attention markets still run on centralized gatekeepers?
Disclaimer: The information provided on AlexaBlockchain is for informational purposes only and does not constitute financial advice. Read complete disclaimer here.
The Bitcoin whitepaper is clear about Bitcoin’s core feature: it is permissionless. Anyone in the world can pay anyone by joining the peer-to-peer network and broadcasting a transaction. Proof of Work consensus even empowers anybody to become a block producer, and means that the only way to reverse a payment is to overpower everyone else through hashpower.
But Proof of Work only defines how to choose a winner amongst competing chains; it does not help a node discover it. A 51% attack – or a 100% attack – is much easier if an attacker can prevent nodes from hearing about competing chains. The job of discovery belongs to the peer-to-peer module, which juggles many contradictory tasks: Find honest peers in a network where nodes constantly join and leave, but without authentication or reputation. Always be on the lookout for blocks and transactions, but don’t be surprised if most data is garbage. Be robust enough to survive extreme adversarial conditions, but lightweight enough to run on a Raspberry Pi.
The implementation details for a permissionless peer-to-peer network were left out of the whitepaper, but constitute the bulk of the complexity in Bitcoin node software today.
Filters are for Spam
The whitepaper acknowledges public transaction relay as the cornerstone of Bitcoin’s censorship resistance, but only says a few words about how it should operate: “New transactions are broadcast to all nodes. Each node collects new transactions into a block. Each node works on finding a difficult proof-of-work for its block.”1
Many find it amusing that Satoshi suggested every node would mine. Due to the centralizing pressure of mining variability, the vast majority of nodes on today’s network do not work on finding a proof-of-work. Perhaps that is an acceptable or even successful result of economic incentives; we traded a portion of decentralization for increased hashpower and thus security. However, Bitcoin’s censorship resistance will collapse if we also give up decentralized transaction relay.
Our desire for a wide pool of transaction relaying nodes must contend with the practicality of everyday computers exposing themselves to a permissionless network and processing data from anonymous peers. This threat model is unique and requires highly defensive programming.
In block download, a block’s proof-of-work elegantly serves as both Denial of Service (DoS) prevention and an unambiguous way to assess the utility of data. In contrast, unconfirmed transaction data is virtually free to create and might just be spam. For example, we cannot know whether the transaction meets its spending conditions until we have loaded the UTXO, which may require fetching from disk. It costs attackers absolutely nothing to trigger this relatively high latency activity: they can craft large transactions using inputs that do not belong to them or do not exist at all.
Validation steps such as signature verification and mempool dependency management can be computationally expensive. Famously, transactions with a large number of legacy (pre-segwit) signatures can take minutes to validate on some hardware2, so most nodes filter out large transactions. Resource usage is not only local to the node either: accepted transactions are typically gossiped to other peers, using bandwidth proportional to the number of nodes on the network.
Nodes protect themselves by limiting the memory used for unconfirmed transactions and validation queues, throttling transaction processing per peer, and enforcing policy rules in addition to consensus. Yet these limits can also create censorship vectors when not designed carefully. The simple logic of not downloading a transaction that has already been rejected before, limiting the size of the transaction queue for a single peer, or dropping requests after failed download attempts can lead to nodes blinding themselves to a transaction. These bugs become accidental censorship vectors when exploited by the right attacker.
In this vein, while it is entirely logical to not keep unconfirmed transactions that are double-spends of each other (only one version can be valid), rejection of a double-spend means that an earlier broadcast precludes a later one from being mined. A double-spend could be an intentional attempt to fake a payment or, when a UTXO is owned by multiple parties, a pinning attack that exploits mempool policy to delay or prevent second layer settlement transactions from being mined. How should nodes choose?
This question brings us to the second element of transaction relay: incentive compatibility3. While fees are not relevant to consensus beyond limiting what a miner can claim as a block reward, they play a huge role in node policy as a utility metric. Assuming miners are driven by economic incentives, nodes can approximate which transactions are most attractive to mine and discard the least attractive ones. When transactions spend the same UTXO, the node can keep the more profitable one. While nodes do not collect fees, they can consider zero fee transactions as spam: they are likely to use up network resources but never be mined, yet cost virtually nothing to create.
These two design goals — DoS resistance and incentive compatibility — are in constant tension. While it is attractive to replace a transaction with a higher feerate-version, allowing repeated replacements with tiny fee bumps could waste the network’s bandwidth. Accounting for dependencies between unconfirmed transactions can create more profitable blocks (and enable CPFP), but can be expensive for complex topologies.
Historically, nodes relied on heuristics and dependency limits, which caused user friction and opened new pinning vectors. Mempools that track clusters can assess incentive compatibility more accurately but still must limit mempool dependencies. These types of restrictions create pinning vectors for transactions involving multiple parties that don’t trust each other: an attacker can prevent their co-transactor from employing CPFP by monopolizing the limit.
It is easy to trivialize these issues: pinning attacks are a niche type of censorship that only apply to shared transactions and typically only result in temporary transaction delays. Is it worth the effort to help non-mining nodes squeeze a few extra satoshis of fees?
A Deal with the Mevil
Shared transactions are the backbone of UTXO-mixing privacy solutions and second layer protocols. Much of Bitcoin development is focused on creating scalable, private, feature-rich applications in a second layer that falls back to settling on-chain. A common pattern is to temporarily delay withdrawals or settlement, allowing parties to respond to misbehavior within a time window. But many designs – including ones that are used to motivate consensus changes – gloss over fee-bumping in these scenarios.
A time window to prevent misbehavior is also a window of opportunity for attackers. These two conditions – shared transactions and confirmation deadlines to prevent misbehavior – create the perfect storm that upgrades the severity of pinning attacks from temporary transaction delays (meh) to potential theft (oh no!).
Pinning has been the subject of years of research and development effort resulting in the Topologically Restricted Until Confirmation (TRUC) transaction format4, Pay to Anchor (P2A) output type5, Ephemeral Dust policy6, Cluster Mempool7, limited relay of packages8, and various improvements to transaction relay reliability. These features are designed to provide stronger guarantees for propagating higher fee replacements of shared transactions.
Still, proper fee management involves overhead in the form of larger transactions, more complex wallet logic, and handling unlikely edge cases. An easy shortcut is to strike a deal with a miner: in exchange for a fee, the miner guarantees that their transactions will be mined promptly. This solution may prove more reliable than using the peer-to-peer network, which can have high latency and poor propagation due to heterogenous mempool policies.
Adoption of direct-to-miner submission can grow quickly when there is commercial interest. Exchanges represent a large proportion of transaction volume and probably prefer predictable timing over optimizing fees. Popular applications may be plagued with pinning attacks or want to use nonstandard transactions that common node policies prohibit. Companies and custodians concerned about quantum short-range attacks may create a private channel with a miner.
As private Miner Extractable Value (MEVil)9 becomes necessary to stay competitive, the network can snowball toward a model of centralized blockspace brokers. These services can become chokepoints for attackers and government mandates and undermine the premise that becoming a miner is permissionless.
If the transaction relay network becomes irrelevant for node operation, then participating in it may also feel unnecessary. In this hypothetical future, will we chuckle at the idea of every node on the network relaying unconfirmed transactions, the way we think it’s funny that Satoshi envisioned every node to be a miner?
The irony is that mining centralization does not begin with overt collusion or regulatory capture. It begins with a few rational shortcuts: more efficient agreements, custom relay paths, or performance optimizations that are beneficial to their participants. Nobody can stop these agreements from taking place. But we can try to reduce the competitive edge that private services have over the public network: iron out mempool pinning vectors before considering proposals for consensus changes that increase the potential for Mevil; make the public transaction relay network an efficient marketplace to bid (and update bids) for block space.
The peer-to-peer network is where many of Bitcoin’s core ideologies come to life. It is also an engineering challenge with painful tradeoffs between efficient node operation, censorship resistance, incentive alignment, and protocol complexity. It will only get harder as Bitcoin grows. How it should choose to reconcile these competing design goals is left as an exercise to the reader.
Get your copy of The Core Issue today!
Don’t miss your chance to own The Core Issue — featuring articles written by many Core Developers explaining the projects they work on themselves!
This piece is the Letter from the Editor featured in the latest Print edition of Bitcoin Magazine, The Core Issue. We’re sharing it here as an early look at the ideas explored throughout the full issue.