Sweden’s Riksbank has recommended that lawmakers prepare for a possible digital krona, citing concerns over foreign-currency stablecoins and the future of domestic payments.
Sweden’s Riksbank has recommended that lawmakers prepare for a possible digital krona, citing concerns over foreign-currency stablecoins and the future of domestic payments.
Cointelegraph is committed to providing independent, high-quality journalism across the crypto, blockchain, AI, and fintech industries.
All news, reviews, and analyses are produced with full journalistic independence and integrity. For more details on our standards and processes, please read our Editorial Policy.
Bo Hines, previously a crypto adviser to US President Donald Trump who later joined stablecoin issuer Tether, reportedly kept a stake in a company that profited from the passage of a stablecoin bill when he was still at the White House.
According to a Wednesday report from The Wall Street Journal, Hines had a one-third stake in the investment company he co-founded, Nxum, while pushing US lawmakers to pass the Guiding and Establishing National Innovation for US Stablecoins, or GENIUS, Act. The legislation reportedly came amid Nxum receiving $6.3 million as part of a deal with stablecoin issuer Tether, behind the USDt (USDT) token, with the first payment going through while Hines was still serving in government.
The Wall Street Journal reported that Hines kept in contact with his partners at Nxum, updating them on progress with the GENIUS Act through the Signal app while serving as Trump’s crypto adviser.
He also reportedly pressed the Nxum partners to label any Republican lawmakers opposing the stablecoin bill as “undermining the president” and “bought and paid for by democratic shills like Coinbase and a16z.” Hines joined Tether as a “strategic adviser” in August 2025, becoming CEO of its US arm the following month.
The reported deal between a former White House official and a crypto company continues to shine a spotlight on accusations that Trump and his family and staff are personally benefitting from laws they help to draft and pass. The president disclosed earning $1.4 billion from investments tied to digital assets in 2025, which included millions of dollars from his family’s crypto company World Liberty Financial, behind the issuance of the USD1 stablecoin.
Related: EU lawmakers push crypto onto anti-corruption agenda
The GENIUS Act passed Congress and was signed into law in July 2025 in a ceremony attended by many cryptocurrency executives, including those behind stablecoins like Tether and Circle. Hines was in attendance and personally recognized by Trump at the event.
Though it was signed into law in 2025, the GENIUS stablecoin bill requires rules from government agencies overseeing the tokens, including the Office of the Comptroller of the Currency, Federal Deposit Insurance Corporation, Federal Reserve Board and Treasury Department. The law is scheduled to go into effect in January 2027.
Cointelegraph reached out to Tether for comment on the accusations in the report but did not receive an immediate response.
Several figures previously in government have left to become executives or advisers to digital asset companies. In addition to Hines joining Tether, Summer Mersinger, a former commissioner with the US Commodity Futures Trading Commission (CFTC), resigned her position three years before her term was scheduled to end for a position as CEO of the crypto advocacy group Blockchain Association.
On Wednesday, Solidus Labs announced that Kevin Webb, a former CFTC senior counsel and adviser to former Commissioner Brian Quintenz, would join the fintech company as its vice president of policy. Webb isn’t the first former commissioner at the company, as the CFTC’s Dawn Stump left the agency in 2022 to join Solidus as a “strategic adviser.”
Magazine: Can the SEC and CFTC’s pro-crypto rules be overturned? Legal opinion
Cointelegraph is committed to providing independent, high-quality journalism across the crypto, blockchain, AI, and fintech industries.
All news, reviews, and analyses are produced with full journalistic independence and integrity. For more details on our standards and processes, please read our Editorial Policy.
In the wake of the failed CLARITY cloture vote in the Senate, the SEC and CFTC immediately moved to issue their own rules for crypto markets.
Two days after the vote, the SEC unveiled a five-year exemption that permits the issuing and trading of stock tokens. OXK has since teamed up with ICE to launch trading in 63 NYSE-listed stocks and Securitize launched 12 Securitize Stocks, including Apple, Nvidia and Microsoft.
The SEC has also issued guidance clarifying that a crypto token doesn’t become a security just because a project is buying back its own tokens, and stated that liquid staking tokens are not securities. It has also proposed new rules for the custody of crypto assets.
The CFTC, meanwhile, moved to exempt some crypto software providers from registration requirements. It has proposed a new “crypto asset market” registration category and intends to allow registered exchanges to offer leveraged trading.
But the concern among some in the industry is that these rules could be built on shifting sands. TD Cowen has cautioned that agency rules “are the easiest to rescind” — which was demonstrated when Trump-appointed commissioners wiped away all traces of the Gary Gensler era.
A 2024 Supreme Court decision also means agency rules can more easily be overturned by the courts.
The durability of regulator rulemaking is currently being tested in court, with a community bank group suing the Office of the Comptroller of the Currency for exceeding its authority by allowing crypto firms to obtain national trust bank charters.
To discuss the legal issues involved, Magazine spoke with Yuriy Brisov from D&A Partners. This is an edited version of the conversation.
Magazine: SEC Chair Paul Atkins said after the CLARITY vote failed that the agency was releasing rules because Congress didn’t. Are agencies like the SEC supposed to create rules, or are they just supposed to interpret rules that already exist?
Brisov: They are supposed to create rules. They have this power under the Exchange Act of 1934. The SEC was created as a result of the major meltdown in the US markets in the end of the 1920s. From the moment of creation, the SEC had the power to create rules and regulations on how the laws should apply. American legislation works by creating general rules, like a frame, and then it has a watchdog watching over these regulations.
There was a reason why it was created like this — so that when, say, blockchain tokens came along, the US legislation would be ready to accommodate new technology. That’s what the Commission has been doing for ages now, and it’s obviously within their powers.
Magazine: Can they interpret the rules in the opposite way to an SEC appointed by a previous administration?
Brisov: There should be a reason for that. They can, in theory, do that, but it should be all within the formation of the body of law. Under Gary Gensler, the Commission tried to apply these rules to tokens. It turns out that it failed because there is still vagueness, and many companies left the US market for good.
This is the opening for the new Commission to oversee these rules and say, “You tried, but we can see that it’s not working. So we’ll offer our own rules.” But the power to offer rules is limited. If they offer some regulations that would lay an unbearable economic burden on companies, or something bizarre, there are also laws that allow companies or any damaged party to challenge this regulation in court and say, “We don’t like what the SEC has been doing because it’s damaging the market.”
In 2011, there was a case when the SEC applied new rules on how shareholders vote through a proxy. And the business community said, “it’s bizarre, it’s burdensome, and we don’t like it.” There was a case, Business Roundtable vs SEC, and [business] won.
Magazine: What was the Chevron decision by the Supreme Court and how does its overturning in 2024 impact court cases about rulemaking by agencies like the SEC and CFTC?
Brisov: Chevron was a famous case of 1984. The court basically said that if the law is vague or there are uncertainties and ambiguities in the statute, then we should use the agency’s interpretation as the law. In June 2024, Loper Bright was a new precedent that overruled Chevron. It’s now saying that we don’t have to. Of course, [the SEC is] a strong authority: Who knows securities laws better than the SEC? But the court should use its own brains and apply the Howey case itself.
Magazine: So that makes it more likely that SEC rules could be overturned?
Brisov: In some cases, the courts can come up with a different conclusion.
You cannot just come and say “we don’t like this regulation.” For instance, if you’re a traditional broker-dealer or traditional participant of the investment market in the United States and you say, ‘Look, I’m suffering because of this new regulation’ they should be able to prove that there was not enough research and that it’s burdensome for the business, and it’s not profitable for the US market. If they prove damages and if they prove a lack of research, then the court can overrule this regulation.
From what I can see, Paul Atkins and the SEC have been consulting with many crypto firms, with VCs. They’ve been doing their research, so it’s not something they just came up with within a day.
Related: OKX, NYSE parent file to launch tokenized US stock platform
Magazine: Let’s assume the SEC and CFTC rules survive for the next two years, and businesses invest a lot of money into infrastructure around tokenized stocks based on the new rules. Could a new SEC unilaterally reverse the rules or do they have to take into account the businesses built on top of the old interpretation?
Brisov: They have to take them into account. If there is the potential for the US market to grow and to benefit from this regulation, they won’t be able to just overrule it. There is the same thought process that either an agency or a court goes through. It’s called IRAC: issue, rule, analysis, conclusion. They would have to apply understandable, transparent logic.
They can’t just say we don’t like it. They have to explain. They have to bring up an economic background for it. They have to bring up research, and they have to prove that it’s insufficient. And only then can they come to a different conclusion.
For the sake of argument, we could say that Paul Atkins hates the Howey test, and he would have been happy just to abandon it — but he can’t do it. In every note, he keeps repeating that the Howey case still works, it’s still a valid regulation in the United States. However, we can interpret it in this case, and this case, differently — and this is our logic. This is what allows us to do that, and he explains it transparently.
Magazine: The SEC appears to have been working on the innovation exemption for years. But the SEC more recently came up with an FAQ saying that a crypto company buying back its own token does not make a commodity token a security. Could I be secure and comfortable launching a token buyback scheme on the basis of an FAQ by the SEC?
Brisov: If you follow it, and it’s created by the people who know what they’re saying, probably you will be in the clear. But it’s not legislation. An FAQ is just like a manual. It doesn’t have any authority, even for the staff.
Magazine: So the FAQ isn’t saying they changed the rules; it is just saying this is what the rules are?
Brisov: It’s just some extra explanation, like a casebook in the university. They are staff notes. A manual that explains for the staff how they should work and how they should understand this. They rewrite them quite often.
Magazine: They rewrote the FAQ after a week because a16z’s legal counsel said it left a massive loophole.
Brisov: Exactly, and that’s how it should be done. It’s not regulation or legislation, they can change them every week.
Magazine: Could THORChain face prosecution over stolen Bitget funds? Legal opinion
Cointelegraph publishes long-form journalism, analysis and narrative reporting produced by Cointelegraph’s in-house editorial team with subject-matter expertise. All articles are edited and reviewed by Cointelegraph editors in line with our editorial standards. Some articles contain affiliate links, from which Cointelegraph may earn a commission. These relationships do not influence which products we review or our editorial conclusions. Content published in here does not constitute financial, legal or investment advice. Readers should conduct their own research and consult qualified professionals where appropriate. Cointelegraph maintains full editorial independence.
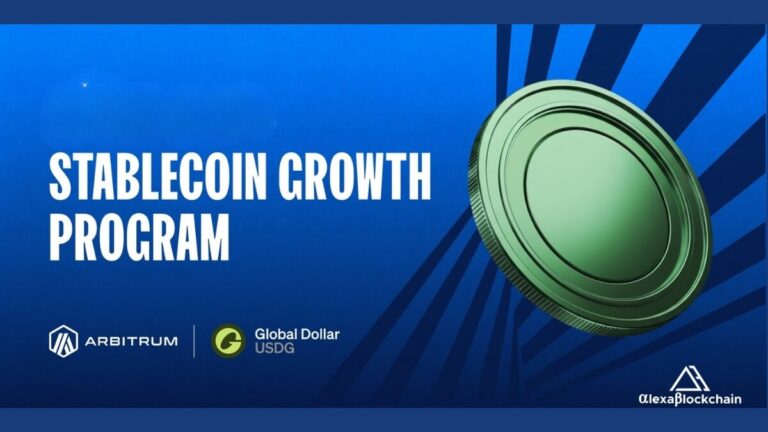
The Arbitrum Stablecoin Growth Program is now open to protocols with at least $1M in stablecoin balances. Eligible protocols that commit to building with USDG as their primary stablecoin may be eligible for performance based incentives from the Arbitrum Foundation as they grow. The first 10 teams in the program to reach $10M in TVL will each receive an additional 200K ARB from a 2M ARB prize pool.
Global Dollar (USDG) is issued by Paxos Digital Singapore Pte. Ltd., a Major Payments Institution supervised by the Monetary Authority of Singapore, and by Paxos Issuance Europe Oy under the supervision of the FIN-FSA and in compliance with MiCA. Learn more at globaldollar.com and https://arbitrum.io/products/usdg-vaults
Builders drive the demand for onchain dollars. The Arbitrum Stablecoin Growth Program is designed to support the teams that bring that demand to Arbitrum. Protocols that make USDG their preferred stablecoin, collateral or on-ramp asset on the Arbitrum Platform can access incentives and ecosystem support to help them grow, without the cost and complexity of issuing their own stablecoin.
The Arbitrum Platform is home to an established DeFi and blockchain ecosystem, with deep liquidity, active markets and teams building across a large variety of categories. The Arbitrum Stablecoin Growth Program gives protocols an opportunity to tap into this ecosystem while growing their own products. Whether you’re expanding an existing protocol or bringing a new deployment to Arbitrum, the program is designed to help teams attract liquidity, increase usage and build for the long term.
Launching and maintaining a stablecoin introduces additional operational, technical and business considerations. By integrating USDG as a primary stablecoin, protocols can focus on their core product while participating in a program designed to support stablecoin adoption
across Arbitrum, with the opportunity to earn more as their stablecoin activity on Arbitrum grows.
Teams can build stablecoin utility directly into their existing products, from lending markets and liquidity pools to payments and other financial applications, while working toward their own growth objectives.
What teams get
Accepted teams may be eligible for performance based incentives linked to their growth on the Arbitrum Platform, and they can put them straight back into their own growth.
Teams may also receive access to Arbitrum’s support suite, which may include marketing resources and co-marketing, introductions to ecosystem partners, integration and technical support, direct access to the ecosystem team, and potential access to incentives through the DeFi Renaissance Incentive Program (DRIP), as well as other perks.
The program also includes a 2M ARB prize pool. The first 10 teams to reach $10M in TVL, measured as a 30-day average, will each receive 200K ARB, in addition to the incentives and support above.
Eligible teams
The program is for stablecoin-centric protocols, such as lending, yield, AMMs or payments, that want to make Arbitrum their home. Eligible teams meet the following.
● At least $1m in stablecoin balances at the time of application, verified on DefiLlama
● Stablecoins at the core of the product, with a live product and audited contracts
● A commitment to building on Arbitrum, with new deployments and token launches happening here
● USDG as the primary stablecoin on Arbitrum, with at least $1m of TVL moving into USDG
How to apply
Apply through the application form. The Arbitrum team reviews every application and gets in touch with teams that are a fit. Participation is subject to eligibility, approval by the Arbitrum Foundation and the Program Terms & Conditions.
Read Also: This is the First U.S.-Chartered Depository Bank to Offer Stablecoin Invoicing
Disclaimer: The information provided on AlexaBlockchain is for informational purposes only and does not constitute financial advice. Read complete disclaimer here.
Cointelegraph is committed to providing independent, high-quality journalism across the crypto, blockchain, AI, and fintech industries.
All news, reviews, and analyses are produced with full journalistic independence and integrity. For more details on our standards and processes, please read our Editorial Policy.
Australia’s securities regulator opened consultation Thursday on proposed capital, custody and trading requirements for crypto platforms, as it prepares to implement legislation passed in April that expands oversight of the industry.
The proposals include three alternative capital models, restrictions on platforms trading for their own account and quarterly reporting of wallets holding customer assets. ASIC also proposes allowing offshore custody while seeking feedback on safeguards if an overseas parent or related company fails.
“Our proposed guidance and standards acknowledge the increasing role of digital assets and tokenization, including in traditional parts of the financial system,” said ASIC Commissioner Alan Kirkland.
The proposed guidance and standards would give crypto operators greater clarity on requirements to obtain a license, safeguard customer assets and meet financial requirements under the new framework. The consultation follows Parliament’s passage of the Corporations Amendment (Digital Assets Framework) Act earlier this year.
“ASIC’s release of CP 392 is an important milestone for Australia’s digital asset industry, Amy-Rose Goodey, CEO of the Digital Economy Council of Australia, told Cointelegraph. “After years of engagement on regulatory reform, it’s encouraging to see the focus shift towards practical implementation.”
OKX Australia CEO Shange Chandra also welcomed the proposals, saying they could drive industry consolidation.
“These standards are appropriately onerous,” he told Cointelegraph. “They will reward operators who have already invested in compliance, capital and custody. They will challenge operators who have waited to make that investment.”
ASIC is weighing three alternative capital models, including one requiring operators without qualifying third-party custody arrangements to hold at least 14 million Australian dollars ($9.7 million) in net tangible assets or 10% of average revenue, whichever is greater.
“We’ll be working closely with our members to examine the three proposed capital models in considerable detail, particularly their proportionality across businesses of different sizes and the concessions available for third-party custody,” Goodey said.
“From our perspective, it is not at all contentious that this level of resourcing and care should be taken when clients entrust you with their assets,” said Chandra.
The regulator has also proposed allowing offshore custody, while seeking feedback on whether Australian operators should have emergency access to private keys if the overseas parent or custodian fails.
Related: Australia warns unlicensed crypto firms of fines up to 10% of annual turnover
“The proposal not to mandate domestic custody is also significant, recognizing the global nature of digital asset markets,” Goodey said.
ASIC also proposes restrictions on platforms trading for their own account and accepting benefits to favor particular tokens, targeting potential conflicts of interest.
“The proposed restrictions on principal trading, affiliated liquidity arrangements and best execution requirements will also warrant careful consideration, given their implications for how Australian exchanges operate and access liquidity,” Goodey said.
Chandra also called for a streamlined license process for established firms with a track record of compliance.
The consultation forms part of ASIC’s 18-month implementation roadmap, published after the Digital Assets Framework Act was passed in April.
Feedback is due Nov. 27, with ASIC aiming to publish final standards and guidance in March 2027. The law is set to take effect on April 8, 2027, and operators will have until Oct. 7, 2027, to apply for the relevant license and can operate while ASIC assesses their applications.
Magazine: China’s P2P stablecoin wallets surge 43x, Korea’s $450B crypto economy: Asia Express
The Crypto Council for Innovation (CCI) and Blockchain Association (BA) said they would join the Digital Chamber and others to push for a court to address the merits of a lawsuit over Illinois’s digital-asset tax, set to take effect in 2027.
In a Tuesday filing in the Circuit Court of Sangamon County, the crypto advocacy organizations asked the court to approve an expedited schedule for summary judgment “to reach a decision on the tax’s lawfulness as quickly as possible.” The filing cited the CCI’s and BA’s lawsuit against Illinois state officials, as well as one filed separately by the Digital Chamber and Illinois Blockchain Association.
“While pausing enforcement of the Digital Asset Tax Act protects Illinois consumers and businesses from this onerous and legally flawed tax until July 1, it remains imperative that the merits are determined as soon as possible,” said CCI CEO Ji Kim.
Earlier this month, Illinois officials agreed to delay implementation of the 0.2% crypto tax law for six months, from Jan. 1 to July 1, 2027. The decision, part of the Digital Chamber’s lawsuit, came in response to claims that the digital asset tax had been “slipped into the state’s budget” without debate or public feedback. Digital Chamber CEO Cody Carbone said at the time that the organization would continue with legal proceedings “until this tax is struck down for good.”
Related: French lawmakers back stablecoin swap tax in 2027 budget bill
The expedited schedule, subject to court approval, could allow a decision on the merits of the law by March.
On Friday, Summer Mersinger is scheduled to step down as CEO of the Blockchain Association as part of a leadership transition. Mersinger joined the advocacy group last year after resigning from the US Commodity Futures Trading Commission.
Kristin Smith, the organization’s former CEO, will step in as interim head, though Mersinger is expected to stay on until the end of 2026.
Magazine: ‘Bunker mode’ won’t protect your crypto, critics say
The US Office of the Comptroller of the Currency (OCC) released a report on debanking efforts, including ties to digital assets as activities that influenced banks to limit financial services.
In a report released Wednesday, the OCC said certain banks had “public and nonpublic policies” restricting services for many industries, including oil and gas, tobacco, firearms and digital assets. According to the banking regulator, the report was in accordance with an August 2025 executive order from US President Donald Trump to prevent what he called “unlawful debanking.”
“Many institutions also placed restrictions on banking digital asset activities, including on issuers, exchanges, or administrators, often attributed to financial crime considerations,” said the OCC.
In November 2024, more than 30 tech and crypto executives claimed to have been denied access to banking services. Many in the crypto industry unofficially dubbed the effort as “Operation Chokepoint 2.0” after the Obama-era initiative to fight fraud and money laundering facilitated by banks.
However, Wednesday’s 47-page report did not include specific examples of debanking relating to digital asset activities. The OCC said it had been “unable to quantify on a comprehensive basis the full extent of debanking or alleged debanking actions” based on a review of nine major banks, and the agency’s head, Jonathan Gould, focused largely on the report’s claims around debanking due to ties to coal and firearms.
“These decisions were not based on financial risk,” said Gould, referencing the debanking due to connections to coal. “Instead, banks cited concerns about negative headlines, public protests, and the perceived reputational consequences of supporting the industry.”
The 2025 executive order from Trump followed calls from many in the industry surrounding claims — including “Operation Chokepoint 2.0” — that the US government under former President Joe Biden may have influenced financial institutions into cutting off crypto firms from certain services.
Related: Fed seeks feedback on proposal critics say could end Operation Chokepoint 2.0