Crusoe said Friday it is developing a new 900 megawatt AI factory campus in Abilene, Texas, to support Microsoft, expanding one of the largest AI infrastructure hubs in the US as hyperscalers race to secure power and data center capacity for next-generation AI workloads.
The new campus will sit next to Crusoe’s existing Abilene infrastructure and include two buildings plus an onsite power plant designed to support grid resilience. Crusoe said the addition will bring the site’s total projected capacity to 2.1 gigawatts, with land clearing already underway and the first building expected to be energized in mid 2027.
The move builds on Crusoe’s earlier Abilene expansion. In March 2025, the company said it was increasing the campus to 1.2 gigawatts across eight buildings, with the second phase then expected to finish in 2026. Crusoe has described the first Abilene phase as a 200 megawatt initial build that scaled into one of the biggest AI infrastructure developments in the country.
The announcement comes days after Microsoft agreed to lease a large data center in Abilene, Texas, from Crusoe, which was originally planned for Oracle and OpenAI. The leased capacity is about 700 megawatts, and the site sits adjacent to the Stargate campus, highlighting how quickly tenants and build plans are shifting in the AI infrastructure race.
That backdrop matters because Abilene has emerged as a strategic AI buildout zone. Recent coverage has tied the area to Stargate-related expansion efforts, while Crusoe has kept pressing ahead with its own campus growth and manufacturing push.
Crusoe said earlier this month it is also building a manufacturing facility for modular AI factories, underscoring how developers are trying to standardize and accelerate deployment as power becomes the main bottleneck.
Crusoe said the new Abilene campus is designed around energy availability first. It will feature 900 megawatts of behind-the-meter onsite generation, battery storage, ultra-high-density compute capacity, and closed-loop non-evaporative liquid cooling.
The company said the project is expected to create thousands of construction jobs and hundreds of permanent roles, while the first eight buildings of the existing campus are already expected to contribute meaningfully to Abilene and Taylor County tax revenue.
Disclosure: This article was edited by Estefano Gomez. For more information on how we create and review content, see our Editorial Policy.
The war just got bigger. Bitcoin briefly got smaller.
Bitcoin dipped to $65,112 early Monday morning, its lowest level since the February crash, before recovering to $67,402 as Asian markets opened.
The 24-hour range of $65,112 to $67,389 reflects a market that sold hard on overnight escalation headlines and found buyers near $65,000, a level that hasn’t been tested since the war’s opening weekend five weeks ago.
Ethereum recovered 2% to $2,044, Solana gained 0.9% to $83.48, and XRP added 1.4% to $1.35. The 24-hour green across the board masks a rougher weekly picture though. BTC is still down 1% on the week, ETH 0.9%, XRP 1.9%, and SOL 3.7%. Tron is the one name sitting in green, up 2.6% in a day and 4.6% on the week, quietly outperforming the entire majors complex.
The escalation this time came from multiple directions simultaneously. Iran-backed Houthi forces entered the conflict, opening a new front beyond the direct U.S.-Israel-Iran theater. Additional U.S. troops arrived in the Middle East, fanning fears of a ground operation.
The Wall Street Journal reported Trump is weighing a military operation to extract uranium from Iran, though no decision has been made. And Iran attacked two aluminum production sites in the region, sending the metal up as much as 6% and extending the war’s economic damage beyond oil and into industrial commodities.
Brent crude rose 2.5% to around $115 a barrel, now up roughly 90% year-to-date. Asian equities fell sharply, with South Korea’s benchmark down 3.2% on a technology stock selloff and Japan’s Nikkei dropping 3.4%. S&P 500 futures pared losses and were trading roughly flat, suggesting some stabilization after the initial reaction.
The $65,112 low matters technically. That level is within range of the $64,000 low from Feb. 28, the day the war started. Bitcoin has spent five weeks building a pattern of higher lows on each escalation, from $64,000 to $66,000 to $68,000 to $69,400 to $70,596.
Monday’s dip below $66,000 is the first time in weeks the floor has moved lower rather than higher. Whether it recovers and re-establishes the uptrend or marks the beginning of a break below the range that has held since the war began is the question for the rest of the day.
Meanwhile, oil at $115 and aluminum spiking on direct attacks on production facilities means the inflationary impact is broadening beyond energy into industrial supply chains. That makes the Fed’s position even harder and the rate cut timeline even more distant.
In South Asia’s fintech story, Bangladesh has always been something of an outlier. Not because it lacks scale, but, because it has built that scale quietly, through infrastructure, inclusion and institutional alignment rather than headline-driven disruption.
When I last wrote about Bangladesh’s fintech ecosystem, the country was already emerging as a mobile money leader. In 2026, that narrative has deepened. What was once a payments-driven ecosystem is now evolving into a broader digital financial architecture-connecting banks, telecoms, government systems and millions of users across the country.
Digital Transformation as Economic Strategy
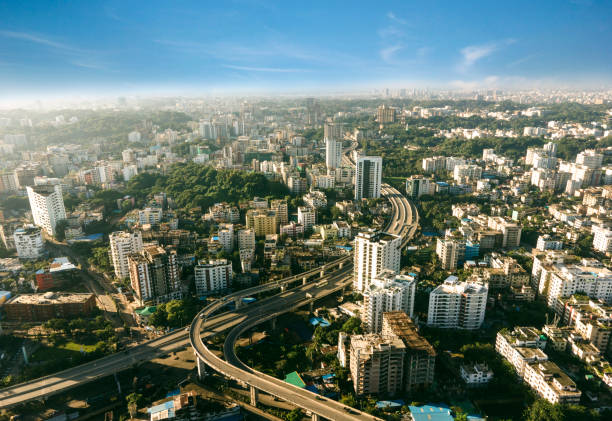
Dhaka is the capital and largest city of Bangladesh IMAGE SOURCE GETTY.
Fintech in Bangladesh is inseparable from the country’s wider digital transformation agenda.
Over the past decade, initiatives such as digital economic development strategy “Digital Bangladesh” have laid the groundwork for a technology-driven economy, focusing on connectivity, digital services and financial inclusion. That foundation is now translating into scale.
Mobile financial services (MFS) transactions alone reached approximately $158billion in 2024, reflecting a 28 per cent year-on-year increase. At the same time, Bangladesh has become a global leader in mobile money usage, accounting for a significant share of global transaction volumes and bringing digital financial services to a large previously unbanked population.
Government-led digital programmes are reinforcing this ecosystem. The launch of the Family Card Digital Welfare Platform this year, designed to deliver financial assistance through a unified digital system, reflects how fintech is being embedded into public service delivery.
This is a defining feature of Bangladesh’s approach: fintech is not operating on the margins; it is integrated into the country’s economic and social infrastructure.
Financial Services Sector: Digital Transformation at Scale
Bangladesh’s financial services sector has undergone a profound digital transformation over the past decade.
Traditionally bank-led, the system has evolved into a hybrid ecosystem where banks, mobile financial services providers and fintech platforms operate in parallel. Bangladesh Bank (the central bank) has played a key role in enabling this transformation.
Bangladesh Bank has allowed 28 banks to operate mobile financial services, creating a bank-led but technology-enabled framework for digital finance.
At the infrastructure level, the National Payment Switch Bangladesh (NPSB) has enabled interoperability across 57 banks, facilitating card, ATM and digital transactions across the financial system.
More recently, the central bank has moved further. Last year, it began developing the Interoperable Instant Payment System (IIPS), which is a unified platform designed to connect banks, mobile financial services providers and fintech platforms in real time.
Complementing this is the rollout of Bangla QR, a national QR payment system supported by banks, card networks and mobile financial services providers, with regulatory moves requiring merchants to adopt cashless payment options.
Together, these initiatives point to a clear direction: Bangladesh is building a fully interoperable, real-time digital payments infrastructure.
Fintech Ecosystem: Scale and Expansion
Bangladesh’s fintech ecosystem has expanded significantly in recent years.
Estimates suggest that the country now hosts over 300 fintech companies, with some industry bodies placing the broader ecosystem at over 500 startups, reflecting rapid growth across payments, lending and financial infrastructure.
This growth builds on earlier momentum.
The strength of mobile financial services providers such as bKash, Nagad and Rocket is notable with bKash alone serving tens of millions of users and acting as a cornerstone of the ecosystem.
Today, that ecosystem is diversifying.
Fintech companies are expanding into the likes of merchant payments and QR-based transactions, digital lending and small and medium-sized enterprises (SME) financing, API-driven financial services and cross-border remittances
This evolution reflects a broader trend: Bangladesh is moving from a payments-led fintech model to a more integrated financial services ecosystem.
Financial Inclusion: A Global Case Study with Remaining Gaps
The traffic of Dhaka is one of the worst in the world, according to the official statistics, every Dhaka resident averagely spend 3.5 hours on street each day. IMAGE SOURCE GETTY
Bangladesh is widely regarded as one of the world’s most successful examples of fintech-driven financial inclusion.
Mobile financial services have brought digital finance to millions, with adoption rates among previously unbanked populations increasing significantly. By 2024, digital financial services had reached a substantial portion of the population, helping reduce exclusion at scale.
Yet challenges remain. Despite progress, an estimated 60 per cent of the population remains unbanked or underbanked, highlighting persistent structural gaps.
The ecosystem also reflects a paradox. While digital payments are growing rapidly, Bangladesh remains a largely cash-dependent economy. Studies note that despite strong mobile money adoption, cash continues to dominate many everyday transactions.
For fintech providers, the opportunity lies in deepening usage, moving users from basic transfers to savings, credit and insurance products.
Partnerships and Ecosystem Momentum
Recent developments highlight the continued evolution of Bangladesh’s fintech ecosystem.
The central bank’s push towards digital banking licences represents a major structural shift, enabling fully digital banks to operate without physical branches.
At the same time, partnerships between fintech firms, banks and global payment networks are accelerating. The integration of Visa and QR-based payment systems, alongside API-driven platforms, is expanding interoperability and enabling more seamless transactions across the ecosystem.
Telecommunications infrastructure also plays a central role. Operators such as Grameenphone, which has invested over $4.1billion in network infrastructure, underpin the connectivity required for digital financial services.
These developments point to a clear trajectory: Bangladesh is moving towards a more integrated, globally connected digital financial system.
Bangladesh’s fintech ecosystem in 2026 is not defined by experimentation. It is defined by scale and by integration. The country has moved beyond building digital financial access. It is now constructing a digital financial architecture that connects institutions, services and users across the economy and boosting wider digital economic development.
Circle’s stock ended last week at $93.6, down roughly 26% from its pre-crash open near $126.
A Senate that could ban passive stablecoin yield directly threatens Circle’s dominant revenue stream.
Analysts say the decline reflects uncertainty about Circle’s business model, not just a market overreaction.
Circle Internet Group’s stock has shed roughly a quarter of its value over the past week, weighed down by three unresolved pressures that appear to challenge the core assumptions behind the company’s investment case.
It opened March 24 near $126, crashed 20% to close at $101, then posted a brief recovery the following session before sliding again over the next two days to end the week at $93, with three of the past four sessions closing in the red, according to historical data on Google Finance.
The drop from Tuesday last week came after two pieces of bad news that landed the same day: a Senate draft bill that could ban the returns Circle distributes to stablecoin holders, and an announcement from its rival, Tether, that it had hired a major accounting firm to audit its reserves for the first time.
Weeks before the decline, Circle was posting double-digit gains, surging roughly 60% since its Q4 earnings report. Analysts had also been broadly optimistic, with Clear Street raising its price target for Circle to $152 earlier this month.
But the Senate’s language on a possible yield ban and the Tether audit announcement remain unresolved, and both appear to have continued weighing on the stock in the sessions that followed.
The draft text is expected to be released publicly this week, arriving ahead of a Senate Banking Committee markup targeted for the second half of April, a deadline legislators have said the bill must clear to avoid stalling until after the midterm elections.
Under pressure
Circle’s stock decline points to broader uncertainty about Circle’s business model, and whether the factors behind the initial drop are temporary headwinds or something more structural, analysts told Decrypt.
“Passive yield is likely one of the biggest reasons retail users on Coinbase hold USDC,” Siwon Huh, researcher at Four Pillars, told Decrypt. “Replacing this with activity-based incentives would require building an entirely new user engagement structure.”
Activity-based rewards programs are structurally different from passive yield in that they require ongoing product investment, and returns diminish if “user engagement plateaus,” Huh explained.
If the Senate’s passive yield ban holds, the transition to activity-based rewards could take at least a year and cost Circle a chunk of its retail user base in the process, he noted.
Still, USDC’s circulation reaching record levels despite the broader market downturn suggests holders are drawn to it as a payments tool, which could mean the stock’s decline overstates the actual risk, Huh said.
If the yield ban holds, Circle’s USDC could lose “its core carry trade,” Dominick John, analyst at Zeus Research, told Decrypt, noting how its model would then shift to “usage-driven economics.”
Activity-based rewards “can drive flow,” but without a “yield engine,” this could mean “lower margins and weaker balance sheet stickiness,” he said, estimating that the transition could take two to four quarters to reset and up to 18 months to stabilize.
Beyond the yield ban, the Tether audit poses a separate competitive risk.
John estimates a successful Deloitte sign-off could put 5 to 15% of USDC’s institutional market share “at risk near-term,” mostly from yield-agnostic flows that can shift on liquidity and perception.
Anything larger would require “consistent proof of long-term reserves,” he noted.
Consensus around the CLARITY Act’s passive yield ban “makes it virtually impossible for stablecoin issuers to adopt a traditional bank-like deposit and profit-sharing model,” and this has become a key factor to capping Circle’s structural upside, Ryan Yoon, senior analyst at Tiger Research, told Decrypt.
Still, Circle’s strength lies in its deep integration with institutional finance and the broader B2B ecosystem, Yoon said.
Circle is “already firmly entrenched in the market” and has “sufficient financial runway to absorb regulatory uncertainties,” making the current slump difficult to read as a definitive decline in corporate value, Yoon said.
Daily Debrief Newsletter
Start every day with the top news stories right now, plus original features, a podcast, videos and more.
OKX’s X Layer is the 21st blockchain to integrate Aave, which recently surpassed the $1 trillion mark in cumulative lending volume.
Aave, the largest decentralized lending protocol with $23.5 billion in total value locked, has launched on X Layer, an Ethereum layer-2 blockchain launched by crypto trading platform OKX.
It marks a significant milestone for X Layer, a blockchain with just $25 million in total value locked, which launched in 2024. The integration would allow OKX Wallet and X Layer users to lend, borrow and earn yield without needing to bridge out to another chain.
“This is a very versatile expansion of our DeFi ecosystem and as such should benefit the full range of customers we have on X Layer,” an OKX spokesperson told Cointelegraph.
X Layer launched in May 2024 in a highly crowded Ethereum layer-2 market. Like many of its competitors, X Layer is focused on scalability, offering $0.0005 transactions on average at one-second block times.
Other notable DeFi platforms integrated on X Layer include Uniswap for decentralized swaps, Chainlink for oracle services and Stargate for cross-chain money transfers.
Aave recently crossed a historic milestone
The integration comes as Aave surpassed the $1 trillion mark in cumulative lending volume in late February, marking an industry first.
Aave secures $23.5 billion in total value locked, enabling users to earn interest on deposits and borrow instantly using crypto as collateral.
Aave is integrated on more than 20 chains, including Ethereum, Arbitrum and Base, and has over $40.4 billion worth of net deposits on the platform compared to Morpho’s $10 billion.
Related: Aave DAO backs V4 mainnet plan in near-unanimous vote
The $23.5 billion figure is more than three times Aave’s closest competitor, Morpho, in the DeFi lending market.
Aave has also taken in over $6.2 million in revenue over the last 30 days, more than five times that of second-place Morpho.
Magazine: Bitcoin may face hard fork over any attempt to freeze Satoshi’s coin
Cointelegraph is committed to independent, transparent journalism. This news article is produced in accordance with Cointelegraph’s Editorial Policy and aims to provide accurate and timely information. Readers are encouraged to verify information independently. Read our Editorial Policy https://cointelegraph.com/editorial-policy
Crypto Treasury Firms Regain Stability After Market Reset
Market turbulence forced a reset across crypto-linked equities, but Grayscale Head of Research Zach Pandl indicated on March 26, 2026, that digital asset treasuries, or DATs, are regaining stability after months of pressure. The analysis points to structural adjustments that helped firms recover from steep valuation declines.
After many DATs fell to trading below the value of their crypto holdings in late 2025, companies introduced targeted changes to restore investor confidence and operational footing. Zach Pandl wrote:
“There are pros and cons to investing in DATs vs crypto ETPs. But the DATs have arguably been a stabilizing force this year, and we believe they will likely be a permanent feature of the crypto investing landscape.”
Strategy Inc. (Nasdaq: MSTR), widely viewed as the bellwether for DATs due to its scale and influence on investor sentiment, played a central role by overhauling its capital structure. The company reduced reliance on convertible debt that had amplified downside exposure, while increasing preferred equity to stabilize financing conditions, and expanded its U.S. dollar reserves to strengthen liquidity during volatility. It also avoided potential exclusion from major benchmark indexes, a key factor in maintaining institutional demand and signaling durability for the broader DAT model. In parallel, Forward Industries used borrowed capital to repurchase shares, reinforcing confidence in valuation recovery. Strategy currently holds 762,099 BTC, valued at around $50.65 billion.
Yield Strategies and Diversification Drive Recovery Momentum
Income generation also supported the rebound. Ethereum-focused firms such as Bitmine Immersion and Sharplink Gaming began staking and restaking assets to produce yield. Solana-aligned Upexi outlined plans to allocate capital into decentralized finance ( DeFi) protocols. These strategies created recurring revenue streams. They reduced dependence on equity issuance during weaker market cycles. They also supported more sustainable operating models.
Diversification further strengthened resilience across the sector. Bitmine expanded into adjacent verticals, including the creator economy, digital identity, and staking infrastructure. Bitcoin-focused entities pursued acquisitions spanning media and fund management. Procap outlined plans to enter artificial intelligence through a proposed acquisition of CFO Silvia. This reflects a shift toward multi-segment business models. Collectively, Strategy’s restructuring, alongside yield generation and diversification efforts, enabled DATs to stabilize after the market reset. Continued asset accumulation reinforced their role in crypto markets.
FAQ 🧭
Why are digital asset treasuries stabilizing now? Structural capital changes and new income strategies are improving resilience and investor confidence.
How are DATs generating returns beyond price appreciation? Firms are using staking, restaking, and DeFi allocations to create recurring yield.
What risks remain for crypto-linked equities? Market volatility and execution risks in new business lines still weigh on valuations.
Why do DATs matter for long-term crypto investment trends? They provide institutional exposure with evolving revenue models tied to digital assets.
Lido’s decentralized autonomous organization is considering a one-off $20 million buyback of its governance token to address so-called price dislocation, which is at “historically depressed levels” relative to Ether, according to the DAO.
The proposal, submitted Friday, seeks permission to swap 10,000 Lido Staked Ether (stETH) tokens, currently worth $20 million from the DAO’s treasury for Lido DAO (LDO), arguing that LDO is undervalued.
“This is not a routine fluctuation. It represents one of the most significant dislocations between LDO’s market price and its underlying protocol fundamentals in the token’s history.”
A token buyback of this size could boost the price of the token, which has fallen roughly 96% from its all-time high. In November, a Lido DAO member pitched an automated buyback mechanism for LDO to improve the token’s price. However, that proposal hasn’t been implemented.
LDO’s change in price relative to ETH since 2024. Source: Lido DAO
Lido DAO pointed out that LDO is trading at a steep discount to Ether (ETH) at a ratio of 0.00016, roughly 63% below its two-year median.
This is despite the protocol holding the top spot of the Ethereum liquid staking market, with a 23.2% share of staked Ether, according to Dune Analytics data. The protocol’s dominance has even been flagged as a centralization risk to the network in previous years.
Share of Ethereum network validators. Source: Dune Analytics
Related: Ethereum builders propose ‘economic zone’ to tackle L2 fragmentation
LDO is currently trading at $0.30, down 95.9% from its $7.30 high set in August 2021, according to CoinGecko data. LDO’s $255 million market cap makes it the 141st largest token by value at the time of writing.
“That dislocation is not justified by a proportional deterioration in protocol performance,” Lido DAO said.
Lido DAO proposes buying stETH in batches
Lido DAO proposed buying up to 10,000 stETH in smaller batches of 1,000 to buy LDO.
Lido DAO said it would use limit orders or adopt a dollar-cost averaging strategy to avoid market volatility.
However, each batch would need approval and could be stopped by tokenholders.
After each batch, results would also need to be reported before continuing execution further.
The proposal also comes as Lido’s revenue fell 23% to 40.5 million in 2025, mostly due to staking fees falling 23% to $37.4 million.
Lido DAO argued the protocol’s fundamentals remain strong, noting that rewards declined just 20% amid the broader market pullback, costs improved 13% in 2025 compared with 2024 and Lido’s take rate rose from 5% to more than 6.1%, enhancing fee capture.
Take rate refers to the percentage of staked ETH rewards the protocol keeps as fees.
Magazine: Bitcoin’s ‘narrative vacuum,’ Ethereum now inevitable: Trade Secrets
Cointelegraph is committed to independent, transparent journalism. This news article is produced in accordance with Cointelegraph’s Editorial Policy and aims to provide accurate and timely information. Readers are encouraged to verify information independently. Read our Editorial Policy https://cointelegraph.com/editorial-policy
The crypto market is heating up fast, and everyone is chasing the next 100x crypto that could turn small moves into massive wins. Right now, Pudgy Penguins and Pi Coin are grabbing attention for their unique paths, one driven by strong community culture and branding, the other powered by mobile-first mining and global accessibility. These projects continue to hold their ground among the best crypto coins as the market evolves and new narratives take shape.
Now, APEMARS is stepping into the spotlight with a completely different energy. Built around explosive presale momentum and precision-timed growth stages, it is capturing attention as a high-potential breakout contender. As investors hunt for the next 100x crypto, APEMARS is quickly becoming the name that keeps popping up in conversations about timing, opportunity, and serious upside potential.
APEMARS ($APRZ): Stage 14 Is Live and Momentum Is Exploding
The burning mechanism is engineered to create scarcity in real time. Every stage progression is tied to controlled token supply adjustments, ensuring that as demand rises, available tokens shrink. This dynamic not only increases perceived value but also strengthens long-term holding incentives. Investors are not just buying tokens, they are entering a shrinking supply ecosystem designed to reward early commitment.
The presale stage structure is where APEMARS truly dominates. Each stage has a limited allocation and a predefined price increase, meaning hesitation directly translates to lost profit margins. The automated timer system ensures fairness while also accelerating urgency. Once a stage sells out early, the next stage activates instantly with a higher price, leaving no room for second chances at lower entry points. This design keeps momentum high and continuously rewards early adopters.
$3,000 Positioned Before Final Stage Transition
A $3,000 investment in the APEMARS presale could grow to approximately $95,700 at listing under the projected ROI. Stage 14 is approaching the point where growth begins to level out. Entering now ensures participation in the final stretch of expansion before stabilization occurs. The APEMARS presale at this stage rewards timely action over delayed certainty. Positioning here defines the remaining potential.
How to Buy APEMARS
Getting started with APEMARS is simple and designed for accessibility. Visit the official website, connect your wallet, choose your preferred payment method, and secure your tokens before the stage advances. The process is streamlined to ensure quick participation without unnecessary delays.
Pudgy Penguins: Community Strength and Brand Expansion
According to the best crypto to buy now, Pudgy Penguins continues to build its reputation as a strong community-driven project. Its focus remains on expanding brand partnerships and strengthening its presence beyond NFTs. The project has successfully leveraged its identity to create real-world connections, including merchandise and collaborations that extend its reach into mainstream audiences.
Recent developments highlight its commitment to long-term sustainability through ecosystem growth rather than short-term hype. By focusing on community engagement and brand value, Pudgy Penguins maintains its position among the best crypto coins for those who prioritize stability and cultural relevance within the crypto space.
Pi Coin: Mobile Mining and Growing Ecosystem
Pi Coin stands out with its mobile-first mining approach, allowing users to earn tokens directly from their smartphones. This accessibility has helped it build a massive user base globally, making it one of the most widely recognized crypto projects in terms of participation.
The project continues to focus on expanding its ecosystem and transitioning toward broader usability. Its development strategy revolves around creating a functional network where users can eventually utilize Pi for real-world transactions. This gradual approach keeps it relevant in discussions around long-term crypto adoption.
Final Words: The Race for the Next 100x Crypto
The search for the next 100x crypto always comes down to timing, utility, and momentum. Pudgy Penguins offers strong community value, while Pi Coin provides accessibility and long-term vision. However, APEMARS stands out with its structured presale growth, aggressive ROI potential, and rapidly increasing demand.
With Stage 14 already live and progressing quickly, the opportunity to secure tokens at this level is shrinking by the day. Investors who act early often capture the highest rewards, while those who wait may face significantly reduced upside. Among the best crypto coins available right now, APEMARS is positioning itself as a high-impact contender that combines urgency with opportunity.
For More Information:
Website: Visit the Official APEMARS Website
Telegram: Join the APEMARS Telegram Channel
Twitter: Follow APEMARS ON X (Formerly Twitter)
FAQs about Next 100X Crypto
What makes APEMARS a next 100x crypto opportunity?
APEMARS combines a structured presale model, strong demand indicators, and a built-in scarcity mechanism. These factors create conditions where early investors can benefit from significant price appreciation over time.
Are Pudgy Penguins among the best crypto coins today?
Pudgy Penguins remains relevant due to its strong community and brand expansion strategy. Its focus on partnerships and real-world presence helps maintain its position among the best crypto coins.
How does Pi Coin compare to other best crypto coins?
Pi Coin focuses on accessibility through mobile mining, making it unique. Its gradual ecosystem development aims for long-term usability rather than immediate market hype or rapid price movements.
Why is timing important in the next 100x crypto investments?
Timing determines entry price and potential returns. Early participation in structured projects often leads to higher ROI, while late entry reduces profit margins significantly in high-growth opportunities.
Is APEMARS better than other best crypto coins for beginners?
APEMARS offers a straightforward entry process and clear stage-based pricing, making it easier for beginners to understand. Its structured growth model helps simplify investment decisions compared to complex projects.
Summary
This article explored the competition for the next 100x crypto by comparing APEMARS, Pudgy Penguins, and Pi Coin. Each project offers unique strengths, from community engagement to accessibility and structured growth. Among the best crypto coins, APEMARS stands out for its momentum-driven approach, while Pudgy Penguins focuses on branding and Pi Coin emphasizes usability. Together, they represent different paths within the evolving crypto landscape.
Trusted Editorial content, reviewed by leading industry experts and seasoned editors. Ad Disclosure
Bitcoin price struggles over the last week were also in its ETF market, as the Bitcoin spot ETFs posted their first net outflows in a month. Before this trading session, these investment funds had experienced a 4-week bullish streak, resulting in a combined net inflow of $2.21 billion.
Bitcoin ETFs See Red Again, While Potential New Member Awaits
According to data from SoSoValue, the combined trading activity across the 12 Bitcoin Spot ETFs resulted in a negative inflow of $296.18 million over the past week. This development represents the seventh weekly outflow of 2026, and the fifteenth since the crypto bear market commenced in October 2025. A daily analysis shows the net withdrawal performance is highly linked to consecutive outflows on Thursday and Friday, combinedly valued at over $396 million. For context, the $225.48 million outflow registered on Friday represents the market’s largest net outflow since March 3rd.
Looking at individual fund performance, BlackRock IBIT experienced the largest net redemptions valued at $158.07 million. Meanwhile, Grayscale’s GBTC, Bitwise’s BITB, and Ark/21 Shares ARKB also registered a total netflow of $169.26 million. ETFs such as Grayscale’s BTC and VanEck’s HODL also posted respective net withdrawals of $5.45 and $10.28, marking minor contributions to the general market’s negative performance. On the other hand, Fidelity’s FBTC accounted for the only recorded net inflow, valued at $46.88 million.
Other ETFs, such as Invesco’s BTCO, Valkyrie’s BRRR, Wisdom Tree’s BTCW, Franklin Templeton’s EZBC, and Hashdex’s DEFI, all experienced zero weekly net flows. At press time, the Bitcoin Spot ETF reported a cumulative total net inflow of $55.93 billion and total net assets of $84.77 billion.
Meanwhile, recent reports indicate that American banking giant Morgan Stanley has filed to launch its own Bitcoin spot ETF under the ticker MSBT. According to Bloomberg analyst Eric Balchunas, the proposed fund will offer the lowest fee in the market at 0.14%, just below Grayscale’s 0.15%. If approved by the SEC, MSBT will be the first Bitcoin spot ETF directly listed by a US bank. For context, Morgan Stanley ranks as a leading financial services operator in the world with an asset under management of $1.9 trillion and a market cap of $251 billion.
Related Reading: Greatest Wealth Transfer Is about To Happen For Altcoins, Analyst Warns
Ethereum Spot ETFs Record Consecutive Outflows
In separate news, the Ethereum ETFs extended their negative performance for a second consecutive week after registering weekly net withdrawals of $206.58 million. At the time of writing, the cumulative total net inflow for the Ethereum spot market is $11.52 billion, while total net assets are valued at $11.33 billion.
BTC trading at $66,859 on the daily chart | Source: BTCUSDT chart on Tradingview.com
Featured image from iStock, chart from Tradingview
Editorial Process for bitcoinist is centered on delivering thoroughly researched, accurate, and unbiased content. We uphold strict sourcing standards, and each page undergoes diligent review by our team of top technology experts and seasoned editors. This process ensures the integrity, relevance, and value of our content for our readers.
Citigroup, a key player in global finance, is weighing a potential acquisition of a US regional bank or brokerage to boost deposits, expand branches, and strengthen lending operations, Bloomberg reported Friday, citing sources with knowledge of the matter.
Discussions have included banks with around $500 billion in assets and brokerages like Stifel and Raymond James, with regulatory approval required under existing consent orders, according to the report.
A successful acquisition would represent a major step under CEO Jane Fraser and could transform Citigroup’s footprint to better compete with JPMorgan and Bank of America.
Capital freed by recent divestitures
The report comes as Citi sits on capital from a series of divestitures.
On February 18, 2026, the company finalized the sale of its Russian subsidiary to Renaissance Capital, a transaction that generated an estimated $4 billion in Common Equity Tier 1 capital benefit.
Five days later, Citigroup sold a 49% stake in Banamex, its Mexican consumer banking arm, for roughly $2.5 billion.
Executives have said they do not anticipate additional Banamex disposals this year, suggesting that the freed capital could be redirected toward growth investments in the US.
Recent financial performance
Corporate banking revenues rose 78% year over year to $2.2 billion in Q4 2025, driven by the bank’s focus on institutional and wholesale clients.
Shares of Citigroup were trading at $108 at the time of reporting, well below the analyst consensus price target of $135.
Citi prepares infrastructure for Bitcoin custody and wallet services
Citi has been quietly developing infrastructure for Bitcoin integration for over three years and is now ready to launch services that bring digital assets into traditional financial systems.
The offering will incorporate the same risk controls and reporting as conventional securities, allowing Bitcoin positions to be integrated into existing workflows.
Citi is also exploring stablecoins and blockchain-based deposit tokens to modernize cross-border payments.
Disclosure: This article was edited by Vivian Nguyen. For more information on how we create and review content, see our Editorial Policy.