Home Blog Page 63

Crypto’s favorite $90 trillion trading product is coming to Wall Street, but big banks are taking it slow

0

Perpetual futures have spent years as one of crypto’s most popular trading products, especially for investors outside the United States. Now that the contracts are entering regulated American markets, Wall Street is trying to decide whether they are a passing retail craze or a lasting threat to traditional futures.

The early numbers have been hard to ignore.

Kalshi’s perpetual futures topped $1 billion in trading volume within a week of launch in June, making them the company’s biggest product debut since prediction markets. The exchange has since sought regulatory approval to offer perpetual futures tied to gold and silver, a sign that the product may not stay confined to bitcoin (BTC) and other digital assets.

Perpetual futures, often called perps, resemble standard futures contracts but do not expire. Traders do not need to close or roll a position into a new contract each month or quarter. Instead, periodic funding payments help keep the contract’s price close to the underlying asset.

The product has become a core part of global crypto trading. Bank of America has estimated annual perpetual futures volume at about $90 trillion.

On May 29, the Commodity Futures Trading Commission (CFTC) cleared Kalshi to offer the contracts. Coinbase (COIN) also received approval to list regulated perpetual futures in the U.S.

Inside Wall Street, however, interest does not mean immediate adoption.

People familiar with discussions said perps are coming up more often, in part because U.S. regulators are allowing markets that once operated offshore to move onshore. Yet most large financial institutions are still studying the products rather than preparing major launches. The first movers are more likely to be proprietary trading firms, market makers and newer clearing firms.

Unlike large banks, prop shops trade their own capital. That gives them more freedom to test new venues, accept operational risk and withdraw if the economics stop working. Big banks face stricter capital rules, client obligations and reputational risk. For them, the profit available in a young market may not yet justify the cost of building compliance, clearing and risk systems around it.

That difference matters because the phrase “Wall Street” covers several groups moving at different speeds. Individual traders and smaller firms often arrive first. Market makers tend to follow once volume grows. Banks usually want years of data, clear regulatory treatment and stable infrastructure before committing large sums.

Still, the potential use cases extend beyond speculation. Perps could help traders manage weekend risk. Traditional futures markets close for part of the weekend, even though wars, elections and policy decisions do not. A trader holding options exposure on Friday may have to wait until Sunday night to hedge a sharp move.

A liquid 24-hour perpetual market could change that. Firms could adjust positions as events unfold, then use weekend prices to estimate where CME futures may reopen. Insiders said that could make perps useful as both a hedge and a source of price discovery.

“The demand has to be there, or the capital won’t be,” one industry insider said, arguing that firms won’t commit balance sheet until customer activity justifies it.

The problem is depth. A contract may trade around the clock, but that does not mean institutions can move large positions without shifting the market. Weekend liquidity remains thin, and collateral systems do not always move as quickly as the markets they support.

There is also a regulatory fight taking shape. One key question is whether some perpetual contracts should be treated as futures or swaps. That distinction affects margin rules, registration duties and who can provide liquidity. Industry insiders said those legal questions may become more important as exchanges push perps into commodities, equities and other traditional markets.

The debate is also becoming a competitive one. CME has challenged the CFTC’s treatment of Kalshi’s bitcoin perpetuals, arguing the contracts should be regulated differently. Similar disputes could emerge if exchanges seek to expand perpetuals into equities and other asset classes.

“A lot of this stuff… is more commercial than people are going to admit to out loud,” another industry insider said, suggesting some opposition reflects incumbent exchanges protecting existing businesses as much as concerns about market structure.

For now, Wall Street’s view is cautious rather than hostile. Trading firms see a product they understand, regulators see a market moving onshore and exchanges see a chance to capture new volume.

But the largest banks are unlikely to lead. They will wait for the rules, liquidity and infrastructure to catch up.
What are perps, anyway? Everything you need to know about crypto’s hottest trading instrument

0

Perpetual swaps, also called perpetual futures or “perps” for short, are the dominant trading instrument in the crypto market, processing an estimated $40 to 50 trillion a year in volume. They dwarf spot trading, and they are the product that professional traders, hedge funds and retail speculators reach for when they want leveraged exposure to the price of bitcoin or tther without owning the underlying asset. Despite their ubiquity, the mechanics that make them work are not widely understood.

To understand perps, it helps to understand what came before them. In traditional finance, leveraged exposure to an asset typically comes through a futures contract, an agreement to buy or sell something at a set price on a specific date. When that date arrives, the contract expires and settles. Traders who want to maintain their position must roll it into the next contract.

In crypto’s early days, this practice created persistent problems. Futures traded at a premium to the spot price of bitcoin, a concept known as basis, which confused retail traders who wanted straightforward directional exposure. And every time a contract expired, positions closed regardless of whether traders wanted them to. BitMEX, the derivatives exchange founded by Arthur Hayes and Ben Delo in 2014, spent the better part of a year shortening contract durations trying to solve this, moving from quarterly to monthly to weekly to 48-hour to 24-hour expiries, but none of that was enough.

A contract that never expires

The perpetual swap, which Delo developed and BitMEX launched in 2016, resolved the problem by eliminating the expiry date entirely, creating a derivative contract that tracks the price of an asset indefinitely. There is no settlement date, no rolling and no expiry. Traders can hold a position for hours or years. This created an immediate structural challenge: without an expiry date to act as an anchor, nothing would naturally force the contract price back toward the spot price of the underlying asset. BitMEX solved this through a mechanism that has since become the industry standard.

Every eight hours, a payment is exchanged between traders on opposite sides of the market. If the perpetual swap is trading above the spot price, indicating excess demand for long positions, traders who are long pay traders who are short. If the perpetual swap is trading below spot, the payment runs the other way. The exchange takes no cut. The rate of this payment, known as the funding rate, is calculated based on how far the perpetual swap price has deviated from spot over the preceding eight-hour window. The further the deviation, the higher the rate. This creates a self-correcting equilibrium. When longs are being charged a substantial funding rate, it becomes expensive to hold the position, which reduces demand and pulls the price back toward spot. Market makers accelerate this process by shorting the perpetual swap and buying spot whenever a meaningful premium opens up, capturing the difference as profit. The funding rate mechanism is now used, in essentially the same form, by every major derivatives exchange in the world.

The role of leverage

The other defining feature of perpetual swaps is leverage. Most exchanges allow traders to control positions significantly larger than their deposited capital, with limits varying by platform and jurisdiction. At BitMEX in its prime, leverage of up to 100 times was available, meaning a 1% move in Bitcoin’s price would produce a 100% gain or loss on a fully leveraged position. To manage the risk this creates for the exchange, perpetual swap platforms use automated liquidation systems. If a trader’s losses approach the value of their deposited margin, the system closes the position before it can go negative, protecting the exchange from absorbing the deficit. The speed and reliability of that liquidation engine became a key competitive differentiator in the early years of the market, and remains central to how exchanges compete today.

Perpetual swaps are now the primary venue for price discovery in crypto. When bitcoin moves sharply, the move typically originates in perp markets before spreading to spot. The structure Delo built in 2016 has proven durable enough that regulators in the U.S. are now exploring its application to traditional assets, with the CME potentially listing perpetual swaps on equities. What began as a workaround for the limitations of crypto futures has become one of the most traded financial products in the world.

Bitcoin ETFs post third straight weekly inflows despite $465 million in late-week losses

0

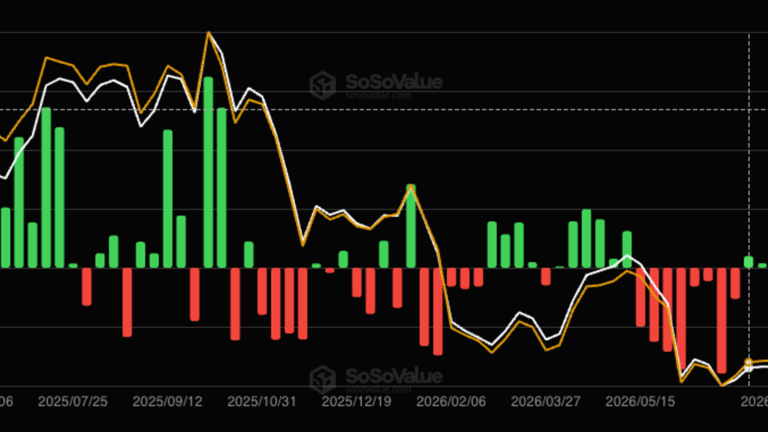
The U.S.-listed spot bitcoin exchange-traded funds (ETFs) have logged their first three-week inflows streak since early May.

These funds attracted $33.79 million in the week ended July 24. That figure would have been much bigger had it not been for net outflows of around $225.2 million and $240.1 million on July 23 and 24 respectively, according to data tracked by SoSoValue.

These late-week outflows also make the total weekly figure the smallest compared to the previous two weeks of inflows of $197 million and $75.67 million.

The story, therefore, is that institutional demand has returned, but it’s anemic and not as powerful as typically observed during bull runs.

“After May and June’s heavy outflows, July’s repair phase has brought relief, but institutional demand is still cautious,” crypto analytics firm BRN said in a email to CoinDesk.

Bitcoin rallied to a July high of over $66,500 on the Tuesday, before retreating below $64,000 by the end of the week, amid profit-taking and weak action in the stock market with the Nasdaq 100 pulled down by chipmaker stocks, a bellwether for the AI industry.

Prices retake $65,000 as oil slides, ETH outperforms

0

Risk-on peace trades are back in vogue after the U.S. and Iran held fire on Sunday, sending oil prices lower.

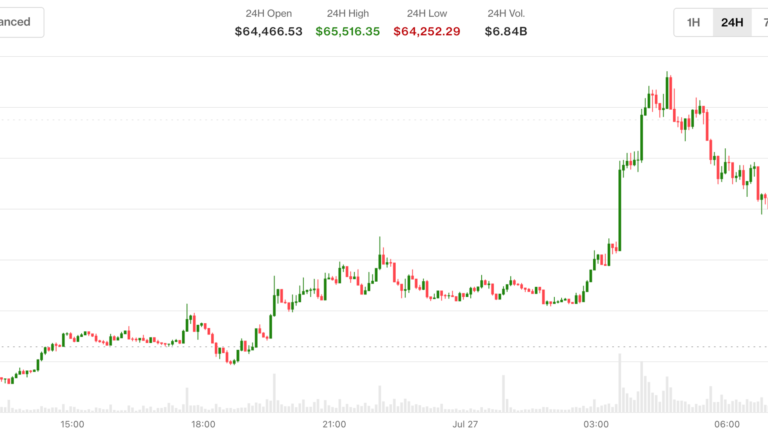
Bitcoin , the leading cryptocurrency by market value, is back above $65,000, with prices up about 1.2% over 24 hours. Ether (ETH) has risen by over 3% to nearly $1,950 alongside 1% to 2% gains in other top 10 token, including solana (SOL) and XRP (XRP).

Futures tied to WTI gapped lower on Monday, trading around 5% lower at $85 as of this writing, while those linked to Nasdaq and S&P 500 traded half a percent higher. Currency markets also showed risk-on trends, with the Aussie dollar and euro gaining against the U.S. dollar.

The United States and Iran paused military strikes against each other for a second consecutive day, creating room for a diplomatic breakthrough. The war, which began in late February, entered a fragile ceasefire in the second quarter, but it quickly unraveled.

Iran reportedly said that it would continue to halt airstrikes as long as the U.S. did the same, marking a tenous start of what appears to be yet another peace process.

Bitcoin (BTC) is the canary in the coal mine for the quantum computing threat

0

Quantum computing is a risk factor for every encrypted system on the planet, including major banks. But crypto, due to the way it works, may be the technology that gets tested first.

“Cryptocurrencies are the canary in the coal mine,” Eddy Zervigon, CEO of Quantum Xchange, said in an interview with CoinDesk. Zervigon’s firm builds infrastructure to shield networks, including financial ones, from quantum-enabled attacks, and he’s blunt about where the first casualty is likely to show up.

“That’s the first place of attack because of the decentralized nature,” Zervigon said. “Once you see it happening there, then you know that someone somewhere has a cryptographically relevant quantum computer.”

A cryptographically relevant quantum computer, capable of breaking the elliptic-curve cryptography underpinning the Bitcoin blockchain’s signatures, along with the encryption securing bank rails, doesn’t exist yet. The consensus estimate for when it will is compressing, not stretching.

“The folks spending billions of dollars, like Microsoft, IBM, and others developing quantum computers, generally believe there will be a commercially relevant, cryptographically relevant quantum computer in the 2029 timeframe,” Zervigon said. “That’s not me making stuff up. That’s based on what people like Arvind Krishna at IBM have said.”

Ether leads crypto higher as bitcoin trades around $65,500

0

Bitcoin is likely to stay range-bound, said Jeff Ko, chief analyst at CoinEx, and he points to three reasons the backdrop has calmed.

Oil has retreated from last week’s highs after another pause in U.S.-Iran hostilities. The 10-year Treasury yield, approaching 4.7%, is doing part of the Fed’s tightening work on its own. And the Fed may want to keep its options open ahead of this week’s PCE inflation and second-quarter GDP data.

The bigger swing factor is corporate. Apple, Microsoft, Meta and Amazon all report this week, and Ko said their free cash flow and AI-spending guidance could move Treasury yields and the Nasdaq, indirectly shaping the liquidity that flows into crypto.

Ko added that the composition of ETF flows will matter as much as the headline numbers.

South Korea trade giant POSCO puts receivables onchain in tokenization test with LG

0

POSCO International, South Korea’s largest trading company, has begun tokenizing trade receivables on blockchain in a test that could speed up commercial payments between its global subsidiaries.

The company, which generated $22.2 billion in revenue last year from businesses spanning steel, energy and battery materials, is working with LG CNS, the technology arm of LG Group, to issue, transfer and settle receivables on layer-1 blockchain Injective , the firms told CoinDesk in a press briefing.

The pilot is using receivables generated by real trade between POSCO’s overseas operations and their counterparties rather than simulated transactions.

Trade receivables represent money owed to a company after goods have been shipped but before payment is received. Today, those claims are typically tracked separately by buyers, sellers and banks, with reconciliation often taking days before cash can be released.

The companies said putting receivables on a shared blockchain ledger creates a single record that can be transferred and settled while carrying compliance rules with the asset itself.

Russia’s Biggest Bank Plans Crypto Trading Infrastructure By Year End

0

Sberbank, Russia’s biggest bank, plans to build cryptocurrency trading infrastructure including a digital depository no later than Dec. 1 as the country brings crypto trading, custody and settlement into its regulated financial system.

That digital depository, Interfax reported, will record ownership of cryptocurrency and process most transactions outside of the main blockchain. Sberbank will operate active wallets for client-initiated deposits, withdrawals and transfers.

“One of the key elements of the new infrastructure will be a digital depository, which will maintain records of clients’ cryptocurrency rights and account for transactions outside the main blockchain,” said Alexander Vedyakhin, first deputy chairman of Sberbank’s management board, the state-affiliated press service said. “It will also facilitate transactions on active wallets to fulfill clients’ currency transfer orders.”

Russia’s lawmakers earlier this month moved the country closer to its first comprehensive crypto market framework after completing final readings on a bill that would regulate digital asset activity.

The bill would give the Bank of Russia broad oversight of the regulated market, including authority to determine which crypto assets may be offered through licensed intermediaries and to issue implementing regulations.The central bank has set liquidity thresholds, including an average market capitalization of more than 5 trillion rubles (~$64 billion) and an average daily volume of more than 1 trillion rubles (~$12.8 billion) over two years.

Once in place, it also establishes five categories of regulated market participants, including crypto exchanges, brokers, asset managers, custodians and exchange service providers, defining who can buy, sell, hold and exchange crypto assets as of the framework’s effective date of Sept. 1, 2026.

Recommended: Bitcoin advocacy group to join US State Department’s ‘digital freedom’ program

Moscow adopts crypto framework as EU tightens sanctions

Moscow is moving to put a working crypto infrastructure in place as the European Union turns up the heat on the country with a package of sanctions targeting Russia amid the country’s war on Ukraine. Last week, the bloc listed cryptocurrency exchange HTX, formerly Huobi Global, in its sanctions.

In a Thursday decision, the European Council amended its previous measures “in view of Russia’s actions destabilizing the situation in Ukraine” to include HTX in a list of 18 entities “providing crypto-assets services or payment services established outside of the Union that are significantly frustrating the purpose of the prohibitions” against Russia. The country continues to face sanctions globally over its war in Ukraine following a military invasion in 2022. 

The sanctions against HTX came the same day EU officials announced they would prohibit Belarusian nationals and residents from owning, controlling or managing crypto exchanges and digital asset service providers in compliance with the region’s Markets in Crypto Assets (MiCA) framework. 

The UK government imposed similar sanctions on HTX in May, saying there were “reasonable grounds to suspect” that the exchange supported Russia’s government by using financial services and funds facilitated by sanctioned entities.

Magazine: Will the US get CLARITY this week? Bitcoin’s new $80K target: Hodler’s Digest, July 19

2 weeks left for Clarity: State of Crypto

0

The crypto industry, naturally, is urging passage. The common refrain online is that Clarity includes some investor protection rules and creates some structure for crypto products, while not passing the bill would mean there are no investor protections.

If the bill is to pass the Senate before summer recess begins, the first thing to watch for is a motion to proceed on Monday or Tuesday. This kicks off the formal process. If the motion to proceed is filed by Wednesday, one individual following the process said, that would still give the Senate enough time to vote on the bill before August 7, the last day of the summer session.

If the motion to proceed ripens — meaning it’s been an hour into the second day after the motion is filed, according to the Congressional Institute, a not-for-profit organization — there can be a cloture vote, most likely on the amendment in the nature of a substitute (i.e. the new text of the bill). If that passes, there can be another cloture vote later on for the actual passage of the bill.

“Recess deadlines are powerful tools,” Kristin Smith, the president of the Solana Policy Institute, told CoinDesk.

On a practical note, what this most likely means is we’ll see the motion to proceed Monday or Tuesday, two industry sources told CoinDesk, with a possible vote late next week.

CFTC Warns Prediction Markets Over Vague Self-Certification

0

For the second time this year, the US Commodity Futures Trading Commission (CFTC) issued a warning to prediction markets operators to follow the rules when creating contract certifications that operators consider cover a broad swath of events contracts.

The CFTC, which claims to be the primary regulator of prediction markets, on Friday issued an advisory clarifying that, notwithstanding ongoing policy discussions and proposed rulemaking concerning prediction markets, the markets retain the ability to certify event contracts as compliant with the Commodity Exchange Act and CFTC regulations without prior commission approval, subject to the statutory framework governing self-certification.

The agency on Friday warned about the number of instances of events contracts that are “self-certified” by the platforms under the agency’s jurisdiction “without supplying the terms and conditions of each proposed permutation and a concise explanation and analysis with respect to the product’s terms and conditions, the underlying commodity, and the product’s compliance.”

 “The guidance reiterates that broad, template-style certifications should not be submitted,” the CFTC said in its July 24 announcement. The regulator issued a similar warning about overly generalized submissions on March 12.

The advisory was issued just days ahead of the CFTC’s July 27 deadline to submit comments on its  proposed rule amendments governing public interest determinations for certain event contracts involving the Commodity Exchange Act’s enumerated activities.

The CFTC has proposed amendments to clarify how it determines whether certain event contracts are contrary to the public interest, establishing a three-step analytical framework for evaluation.

This framework will help assess contracts based on their involvement in activities like terrorism, assassination, or gaming, ensuring that only appropriate contracts are listed for trading.

The proposed rule, if adopted, would fundamentally reshape aspects of the regulatory landscape for prediction markets, law firm Ropes & Gray said in June.

Cointelegraph is committed to independent, transparent journalism. This news article is produced in accordance with Cointelegraph’s Editorial Policy and aims to provide accurate and timely information. Readers are encouraged to verify information independently.