Home Blog Page 524

Ethereum Leads The Tokenization Race With Billions In Assets

0

Trusted Editorial content, reviewed by leading industry experts and seasoned editors. Ad Disclosure

Ethereum is rapidly emerging as the dominant force in the race to tokenize real-world assets, with billions of dollars already flowing onto its network. From tokenized bonds and funds to real estate and treasuries, ETH has become the preferred infrastructure for institutions looking to bring traditional assets on-chain.

Institutional Capital Accelerates Ethereum Adoption

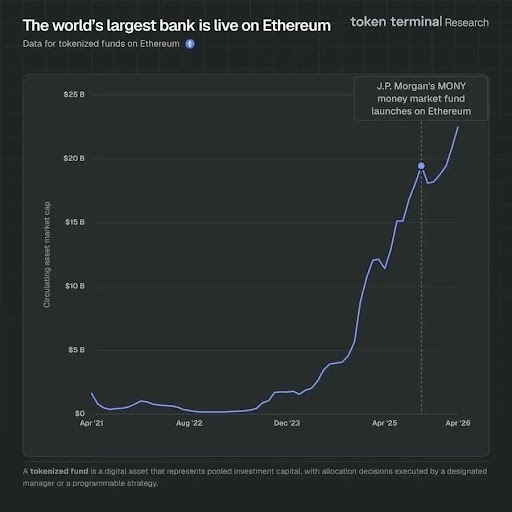
In a recent X post, The Etherealize revealed that Ethereum is rapidly emerging as the dominant layer for tokenized treasury products, with over $22.5 billion in fund assets already tokenized on the network, representing roughly 71.9% of the total market share across all blockchains.

The momentum is being driven by industry heavyweights like JPMorgan Chase, which launched its MONY market fund on ETH in early 2026, joining established offerings such as BlackRock’s BUIDL and Franklin Templeton’s on-chain money fund. These are institutional-grade treasury management products. These products are suited for autonomous agents with idle capital needs operating on permissionless infrastructure, allowing agents to access the system without a brokerage account.
Ethereum
Source: Chart from The Etherealize on X

Ethereum is steadily evolving into the most viable financial layer for autonomous agents managing real capital. The Etherealize has also mentioned that an autonomous agent with a $500,000 treasury will need a stable requirements money market fund with a predictable yield, deep liquidity, minimal smart contract risk, and no centralized counterparty that can freeze or seize its assets. This is where the ETH DeFi ecosystem is beginning to stand out, and it meets these criteria.

The hacks and losses persist, but they are increasingly rare and concentrated at the speculative edges of the ecosystem. A stable core of application has proven remarkably robust through repeated stress events, and that track record shows what other chains can’t replicate. This growing stability is reflected in the declining share of DeFi losses relative to total value locked (TVL) on the ETH mainnet.

How Institutional DeFi Moves Beyond Experimentation

The tokenized finance could see a defining moment, one that markets may only fully appreciate in hindsight. Marc Baumann, the Founder of fiftyonexyz, has pointed out that Broadridge Financial Solutions has already processed over $8 trillion per month in tokenized repo settlements and has now taken a critical step beyond settlement by enabling real on-chain governance for tokenized equity.

At the same time, Galaxy Digital is serving as the staking provider for BlackRock’s ETHB staked Ethereum ETF, linking institutional capital directly into blockchain infrastructure. Together, these firms are involved in enabling the first on-chain shareholder vote for tokenized equity.

Baumann explained that the proxy voting market is estimated at $200 billion, and traditional players such as custodians, transfer agents, and proxy solicitors should pay attention, as the infrastructure for a new financial layer of institutional DeFi is being built by firms that already run on Wall Street. Rather than emerging from a purely crypto-native startup, the transformation is being driven by the same companies that process 401(K).

Ethereum
ETH trading at $2,239 on the 1D chart | Source: ETHUSDT on Tradingview.com

Featured image from Getty Images, chart from Tradingview.com

Editorial Process for bitcoinist is centered on delivering thoroughly researched, accurate, and unbiased content. We uphold strict sourcing standards, and each page undergoes diligent review by our team of top technology experts and seasoned editors. This process ensures the integrity, relevance, and value of our content for our readers.
Michelle: The Lindy effect predicts project longevity, monetizing content through paywalls can yield quick income, and exercise stabilizes mental health

0

Key takeaways

  • The Lindy effect suggests that the longer a project has existed, the longer it is likely to continue, providing a framework for assessing longevity.
  • Monetizing content through a paywall can lead to meaningful income shortly after implementation.
  • Baseline happiness can be improved through specific practices, enhancing overall well-being.
  • Exercise helps prevent negative feelings rather than directly increasing happiness.
  • Simple, quick, and emotionally evocative charts tend to go viral.
  • Product management focuses on delivering business impact by solving significant problems.
  • Product managers should adopt a CEO mindset to align product success with business growth.
  • Real-life experiences provide the best insights, surpassing theoretical knowledge.
  • Refining and revisiting ideas can lead to better creative outcomes.
  • The creative process benefits from reflection and iteration, enhancing work quality.
  • Engaging storytelling and connecting with audiences are crucial in content creation.
  • Understanding the dynamics of content virality can improve audience engagement.
  • Strategic planning is essential for evaluating project longevity and sustainability.

Guest intro

I cannot write an accurate professional biography for Michelle to introduce as a guest on Lenny’s Podcast based on the search results provided. The search results contain information about multiple different people named Michelle (Michelle Bond, Michelle Lilly, Michelle Neufeld, and Michele Korver) working in crypto and fintech, but none of them appear to be the guest on this episode of Lenny Rachitsky’s podcast. The episode description indicates the guest is Lenny’s wife discussing her children’s book “Charts for Babies,” but the search results do not contain information about who Lenny Rachitsky’s wife is or her professional background. To write an accurate biography meeting your requirements, I would need search results specifically about the actual guest on this episode.

Understanding the Lindy effect

  • The Lindy effect implies that the longevity of a project can be predicted based on its current duration.
  • There’s this Lindy effect… as long as it’s been going for it will most likely last at least that long in the future

    — Michelle

  • This concept is valuable for strategic planning and assessing content sustainability.
  • Projects with a longer history are perceived as more likely to endure.
  • The Lindy effect can guide decision-making in content creation and business strategies.
  • Understanding this effect helps in evaluating the potential longevity of creative endeavors.
  • It provides a framework for predicting the future success of long-standing projects.
  • The Lindy effect emphasizes the importance of consistency in sustaining projects.

Monetizing content through paywalls

  • Implementing a paywall can lead to significant income shortly after launch.
  • I launched the paywall and it worked… I made meaningful dollars like a month in

    — Michelle

  • Paywalls offer a viable revenue model for content creators in the newsletter industry.
  • This strategy highlights the potential for monetization in content creation.
  • Understanding the challenges and opportunities in the newsletter industry is crucial.
  • Successful paywall implementation requires understanding audience willingness to pay.
  • Monetizing content can provide financial sustainability for creators.
  • Paywalls can transform content creation from a hobby to a profitable venture.

Improving baseline happiness

  • Everyone has a baseline level of happiness that can be improved through specific practices.
  • One of the things is just be optimistic… work on improving that baseline so that you come back to a higher place

    — Michelle

  • Positive outlook and mindset play a critical role in enhancing baseline happiness.
  • Practices like optimism can prevent the mind from spiraling into negativity.
  • Improving baseline happiness involves consistent effort and mindset shifts.
  • Understanding baseline happiness helps in developing strategies for personal growth.
  • This concept provides a mechanism for enhancing overall well-being.
  • Psychological principles underpin the idea of improving baseline happiness.

Exercise and mental health

  • Exercise doesn’t directly increase happiness but helps prevent negative feelings.
  • Exercise doesn’t make you happier but it brings you out of the negative

    — Michelle

  • Physical activity is crucial for maintaining mental health and preventing negativity.
  • Exercise acts as a stabilizer, bringing individuals from negative to neutral states.
  • This insight challenges common assumptions about exercise and happiness.
  • Understanding the psychological effects of exercise can inform mental health strategies.
  • Exercise is a tool for maintaining emotional balance rather than boosting happiness.
  • Recognizing the nuanced role of exercise can lead to more effective mental health practices.

Characteristics of viral content

  • Charts that are simple, quick, and evoke emotions are more likely to go viral.
  • What I like to make is things that are really simple and quick… if it makes them feel something

    — Michelle

  • Emotional engagement is a key factor in content virality.
  • Simplicity and quick comprehension enhance the shareability of content.
  • Understanding audience engagement dynamics is crucial for creating viral content.
  • Viral content often provides new perspectives or insights to the audience.
  • The emotional impact of content contributes to its viral nature.
  • Creating content that resonates emotionally can improve audience reach.

Role of product management

  • Product management focuses on delivering business impact by solving significant problems.
  • Your job as a product manager is to deliver business impact by prioritizing and solving the most impactful business problems

    — Michelle

  • Effective product management aligns with overall business strategy and growth.
  • Product managers play a strategic role in prioritizing business objectives.
  • Understanding the role of product management is crucial for business success.
  • Product managers should think like CEOs to ensure product alignment with business goals.
  • Strategic decision-making is a core aspect of product management.
  • The focus on business impact differentiates successful product management.

Value of real-life experiences

  • The best insights come from real-life experiences rather than theoretical knowledge.
  • The best stuff comes from actual experience… from people on the ground doing the thing

    — Michelle

  • Experiential knowledge provides valuable insights and practical advice.
  • Real-life experiences offer a grounded perspective that surpasses theoretical understanding.
  • Practical experience is crucial for effective learning and sharing in any field.
  • This insight emphasizes the importance of hands-on experience in generating insights.
  • Understanding the value of real-life experiences can enhance personal and professional growth.
  • Real-world experiences provide a richer source of knowledge than theoretical concepts.

Refining ideas for better outcomes

  • Refining and revisiting ideas often leads to better creative outcomes.
  • I put them to the side and then I come back… I might have an idea like oh yeah that’s what’s gonna make that better

    — Michelle

  • The iterative process of creativity involves reflection and improvement.
  • Revisiting ideas can spark new insights and enhance work quality.
  • Understanding the creative process is crucial for producing quality work.
  • Iteration and reflection are key components of successful creative endeavors.
  • The creative process benefits from continuous refinement and idea development.
  • Recognizing the importance of iteration can lead to more effective creative strategies.

Disclosure: This article was edited by Editorial Team. For more information on how we create and review content, see our Editorial Policy.

How Revolut scaled to over 52.5 million users globally

0

Revolut reached 52.5 million users by the end of 2024, according to Fortune. That number, reported alongside £790 million in net profit, marks a turning point: a neobank founded in 2015 with a prepaid currency card has become one of the most used financial institutions in the world. The path from startup to 52.5 million users tells a story about product strategy, geographic expansion, and the compounding power of a well-designed referral loop.

The early product decisions that built scale

Revolut launched with a single product proposition: a card that let you spend in foreign currencies at the interbank rate. The problem it solved was real and measurable. International travellers and frequent cross-border workers were losing 3-5% on every foreign currency transaction through their traditional bank cards. Revolut eliminated that loss. The future of digital banking runs through this playbook: identify an underserved pain point, build a product that solves it demonstrably, and use the trust earned to expand the customer relationship.

Geographic expansion as a growth multiplier

Reaching 52.5 million users required geographic expansion at a pace traditional banks cannot match. Revolut operates in over 35 countries and has localised its product for dozens of regulatory environments. The marginal cost of entering a new market with a mobile-first product is a fraction of the cost of establishing a physical banking presence. The UK attracted $3.6 billion in fintech investment across 534 deals in 2025 per Innovate Finance, including capital supporting Revolut’s expansion and UK banking licence.

The referral flywheel and low customer acquisition costs

One of Revolut’s most underappreciated competitive advantages is the efficiency of its customer acquisition. Unlike traditional banks that rely on branch networks, direct mail campaigns, and expensive TV advertising, Revolut grew largely through word-of-mouth and a carefully designed referral programme. When an existing user invites a friend, both parties receive an incentive — typically free access to a premium feature or a cash bonus — which creates a self-reinforcing loop that costs a fraction of conventional paid acquisition. This approach kept customer acquisition costs low even as the user base scaled from hundreds of thousands to tens of millions. The viral coefficient embedded in the product design meant that growth compounded without requiring proportional increases in marketing spend. How digital banks are transforming consumer banking in large part comes down to this advantage: when the product itself drives acquisition, incumbents with high branch overheads cannot compete on unit economics regardless of how aggressively they discount fees.

The superapp ambition and product depth

Revolut’s trajectory from currency card to 52.5 million users reflects a deliberate superapp strategy. The product roadmap has consistently added services that keep users inside the Revolut ecosystem rather than seeking solutions elsewhere. Stock trading, cryptocurrency exchange, savings accounts with competitive rates, travel insurance, junior accounts for under-18s, business accounts, and expense management tools have all been folded into a single app. Each new product increases the switching cost for existing users and gives the platform an additional monetisation vector. The breadth of financial services available on a single interface replicates what a full-service bank provides, but without the physical infrastructure costs. This product depth also means that average revenue per user rises over time as customers engage with more features, improving the economics of each account without requiring fresh acquisition spend. The result is a business model that becomes more efficient as it scales rather than running into the diminishing returns that constrain traditional branch-based retail banking.

Regulatory milestones and their significance

Revolut’s 2024 UK banking licence was among the most consequential regulatory milestones in recent neobank history. Operating as a licensed bank rather than an e-money institution changes the risk profile for customers — deposits become eligible for Financial Services Compensation Scheme protection up to £85,000 — and unlocks the ability to offer lending products directly from Revolut’s own balance sheet. This shifts the revenue model: net interest income from loans and mortgages becomes available in addition to subscription and interchange revenue. The banking licence also signals regulatory confidence in Revolut’s operational controls, which had been a source of scrutiny in earlier years. Why fintech is becoming a strategic priority for financial institutions is demonstrated clearly in Revolut’s case — the combination of technology infrastructure, a trusted brand built on 52.5 million users, and a full banking licence creates a competitive position that traditional banks will find increasingly difficult to erode.

The subscription model and revenue diversification

Revolut’s journey to profitability was built on subscription revenue rather than purely transactional fees. Its premium tier, Metal, and Ultra subscription plans generate predictable recurring revenue. This subscription layer sits alongside revenue from interchange fees, currency exchange margins, and financial products including stock trading, crypto, and savings. Mordor Intelligence projects the UK fintech market growing to $43.92 billion by 2031, a market in which Revolut’s diversified revenue model positions it well.

What 52.5 million users means for market position

Scale at 52.5 million users creates compounding advantages. Payment network effects mean that Revolut-to-Revolut transfers are instant and free, which incentivises users to invite their networks. Data advantages allow more precise fraud detection and credit underwriting. Fortune Business Insights projects the global fintech market growing to $1.76 trillion by 2034. Revolut at 52.5 million users is well-positioned to capture a significant share of that expansion. Venture capital’s early bets on Revolut have been validated by a growth trajectory that few could have predicted from the initial currency card proposit The 52.5 million user milestone is not merely a vanity metric — it represents an installed base of customers who have already replaced at least one traditional banking relationship with a digital alternative. For every user who uses Revolut as their primary current account, a legacy institution has lost not just fee revenue but the data relationship that underpins product cross-sell. That shift, multiplied across tens of millions of accounts, is what makes Revolut’s growth story structurally significant for the entire retail banking sector. The question now is not whether Revolut can sustain its growth, but how quickly the gap between neobanks and incumbents will widen as mobile-first customers become the norm rather than the exception.


Morgan Stanley Bitcoin ETF Trades $34M On Debut

0

The Morgan Stanley Bitcoin Trust (MSBT), the first spot Bitcoin exchange-traded fund (ETF) offered by a US bank, recorded $30.6 million in inflows on its trading debut, giving the Wall Street bank a respectable entry into the spot Bitcoin ETF market.

MSBT started trading on the NYSE Arca on Wednesday, generating $34 million in trading volume, slightly above the expectations of Bloomberg ETF analyst Eric Balchunas, who predicted first-day volume would reach $30 million.

As of April 8, MSBT held 444.4 Bitcoin (BTC), worth around $31.7 million, accounting for 0.03% of the estimated 1.29 million BTC collectively held by US spot BTC ETFs.

Offering the lowest fee among its peers, Morgan Stanley’s ETF trailed only BlackRock’s iShares Bitcoin Trust (IBIT) on the day, which saw $40 million in inflows, highlighting competition in a market dominated by a few large issuers.

The debut matters less as a challenge to BlackRock than as a sign that traditional finance still sees room in Bitcoin ETFs, but Morgan Stanley is arriving two years late to a market where the 2024 launch class set a far higher bar for first-day demand.

Total Bitcoin ETF flows negative amid outflows from FBTC and ARKB

IBIT and MSBT’s inflows were not enough to offset selling from other funds, as the Fidelity Wise Origin Bitcoin Fund (FBTC) and the ARK 21Shares Bitcoin ETF (ARKB) saw outflows of $79 million and about $75 million, respectively, according to Farside data.

The Grayscale Bitcoin Trust ETF (GBTC) added another $11 million in redemptions, bringing total daily outflows from US spot Bitcoin ETFs to $124.5 million.

Source: Farside

The outflows marked two consecutive days of selling, following Tuesday’s $159 million in outflows, after the funds recorded $471 million in inflows on Monday, the largest daily inflow since late February.

Related: Canary Capital submits application for US-based spot PEPE ETF

MSBT trails the 2024 launch wave

MSBT’s debut was modest compared with the January 2024 launch wave that followed the Securities and Exchange Commission’s approval of the first US spot Bitcoin ETFs.

GBTC and IBIT handled $2.3 billion and $1 billion in opening day volume, respectively. IBIT saw about $112 million in inflows on its first day, while GBTC recorded $95 million in outflows.

Although trailing, Morgan Stanley’s Bitcoin ETF is still on track to be among the top ETF launches in the past year, according to Bloomberg’s Balchunas.

Source: Eric Balchunas

The ETF analyst referred to funds including the Bitwise Solana Staking ETF (BSOL), the Canary XRP ETF (XRPC) and the Roundhill Memory ETF (DRAM), highlighting a $60 million volume threshold.

Magazine: Your guide to surviving this mini-crypto winter