Potentially taxable onchain crypto activity reached at least $457 billion globally in 2025, while international reporting rules may capture only a fraction of it, according to a new Chainalysis report.
The US accounted for an estimated $112.6 billion of the total, while North America led all regions with $134.6 billion, followed by the European Union at $125.1 billion.
The estimates include realized gains, income from activities such as mining, staking and lending, and crypto-denominated payments across six major blockchains, but exclude trading and other activity conducted within centralized exchanges.
Chainalysis said transactions covered by the Organisation for Economic Co-operation and Development’s (OECD) Crypto-Asset Reporting Framework (CARF) account for just 14% of the onchain taxable activity it identified. The remaining 86% includes activity on decentralized exchanges, peer-to-peer transfers, onchain income streams and payments.
CARF, developed by the OECD in 2022, requires covered crypto service providers to report customer transaction data to tax authorities.
CARF covers only 14% of potentially taxable onchain crypto activity. Source: Chainalysis
Related: Chainalysis sues US over $95M ICE contract with TRM Labs
CARF’s limits on onchain tax reporting
CARF data collection began on Jan. 1, 2026, in 48 jurisdictions, including the United Kingdom and European Union, requiring covered crypto platforms to collect additional customer and tax residency information.
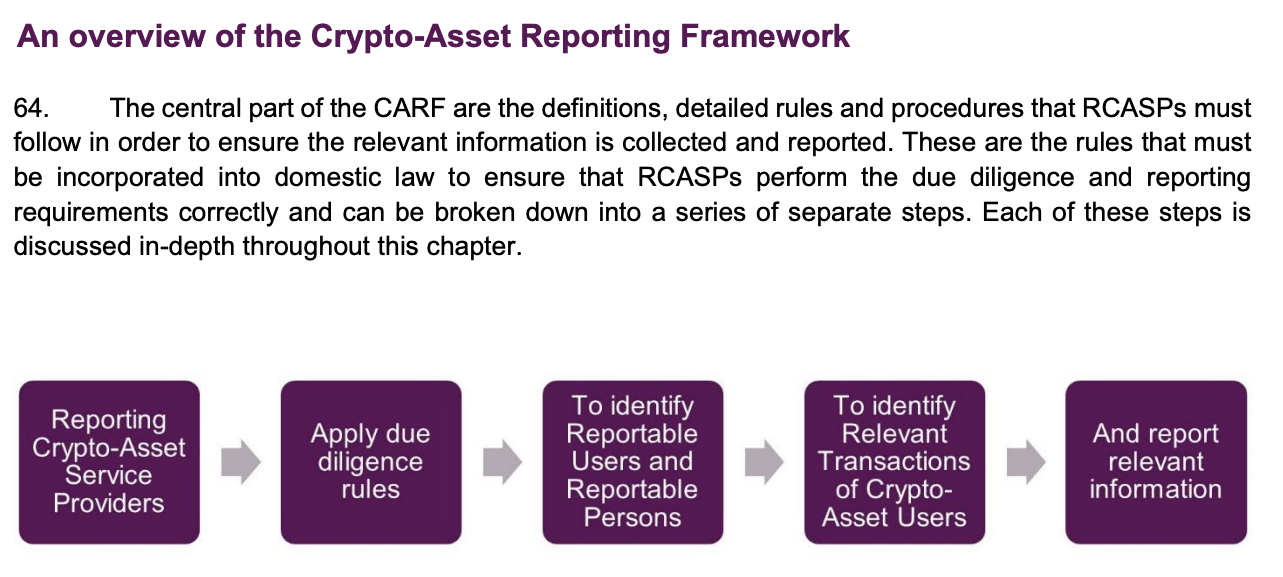
Under CARF, in-scope crypto providers collect customer and tax residency information and report transaction data to domestic tax authorities, which can then share that information across borders.
CARF framework. Source: OECD
CARF’s focus on crypto intermediaries also helps explain the gaps highlighted by Chainalysis. Colby Mangels, a former OECD adviser who worked on CARF, told Cointelegraph in January that the framework was designed around intermediaries that facilitate crypto transactions as a business.
Much of decentralized finance therefore remains outside the reporting perimeter, as there may be no centralized operator or custodial relationship on which to impose reporting requirements.
That could change as regulators develop rules for decentralized platforms. Mangels said tax authorities are watching developments in anti-money laundering regulation, including efforts to determine when DeFi platforms or their operators should be treated as regulated crypto service providers.
The US Securities and Exchange Commission (SEC) is moving forward with plans to overhaul custody rules for investment advisers and investment companies, potentially giving institutions greater clarity on how they can hold crypto assets for clients while complying with federal securities rules.
The proposed rule was sent on Aug. 25 to the Office of Information and Regulatory Affairs (OIRA), part of the White House Office of Management and Budget, for review before it can move back to the SEC and potentially be released for public comment.
SEC submits “Amendments to the Custody Rules” to OIRA. Source: Reginfo.gov
According to the SEC’s regulatory agenda, the agency is considering changing existing rules or introducing new ones under the Investment Advisers Act and Investment Company Act. The changes would cover how investment advisers and funds hold client assets, including crypto.
The regulator said the changes are intended to clear up uncertainty around how companies can hold crypto for clients while staying within its rules. The proposal has not yet been made public, and the White House Office of Management and Budget can request changes before sending it back to the SEC. The commission would then vote on whether to release it for public comment.
As Bloomberg reported, the proposed rule is part of the agency’s broader push to advance the Trump administration’s digital asset agenda as the CLARITY market structure bill remains stalled in the Senate. The bill is expected to face a cloture vote after lawmakers return from the August recess in September.
Related: CFTC follows SEC in scrapping ‘no-deny’ policy for settlements
SEC shifts from crypto enforcement to rulemaking
The SEC has taken a more crypto-friendly approach since Paul Atkins became chair in 2025, shifting its focus from enforcement actions toward developing clearer rules for the industry. Atkins vowed to end the agency’s previous “regulation through enforcement” approach and said policymaking should instead be carried out through formal rulemaking.
The shift has also been reflected in enforcement. The SEC dismissed several cases against major crypto companies in 2025, including its lawsuit against Coinbase, as it moved to reshape its approach to digital assets.
Cointelegraph is committed to independent, transparent journalism. This news article is produced in accordance with Cointelegraph’s Editorial Policy and aims to provide accurate and timely information. Readers are encouraged to verify information independently.
After what feels like a lifetime in the making, the SEC’s proposed new Regulation Crypto Assets rules could finally make public token sales easier in the United States.
The proposal would allow qualifying issuers to raise up to $75 million during any 12-month period, and potentially allow projects to return to investors to raise more funds year after year as they build out their networks.
That could create a new, staged model for token fundraising, and potentially make early allocations more attractive to investors betting on higher valuations later.
But before you put the champagne on ice, it’s unlikely to bring back the freewheeling initial coin offering mania of 2017, according to Lee Reiners, a Duke University lecturing fellow and financial regulation expert. He tells Magazine:
“My initial view is that the $75 million exemption could make public token offerings more feasible, but it is unlikely to produce a return to the ICO boom.”
Could projects raise $75M every year?
The Securities and Exchange Commission’s proposal, unveiled Aug. 18, creates two exemptions for certain investment contracts involving crypto assets.
SEC Proposes New Regulation Crypto Assets. Source: SEC
The first is a one-time exemption for startups for offerings of up to $5 million over four years, and the second is a larger fundraising exemption allowing up to $75 million in each 12-month period.
Related: MiCA cracks down on USDT in Europe… but no one else cares
The latter is modeled in part on Regulation A and comes with disclosure and ongoing reporting requirements.
Does the rolling nature of the $75 million limit mean a project could simply raise $75 million, build for a year, then come back for another $75 million?
The answer appears to be yes.
Drew Hinkes, partner at Winston & Strawn, tells Magazine the 12-month limitation would allow for “serial raises” of $75 million every 12 months, “provided they are actually distinct offerings.”
So what’s the catch?
Lilya Tessler, partner and leader of Sidley’s Global FinTech and Blockchain group, says that while “nothing prevents an issuer from relying on the exemption more than once,” each raise “isn’t automatic.”
Subsequent raises would require filing a new offering statement and undergoing an SEC staff review, and issuers would have to keep filing annual and semiannual reports. They would also need to “disclose what the issuer raised under the exemption in the prior 12 months so the cap can be verified,” Tessler says.
Still, the proposed rules offer a substantial upgrade from the status quo. A project seeking $225 million in total, for example, could potentially raise the funds in chunks and return to investors later with a more developed network — and a higher valuation.
Could a cap create ICO-style FOMO?
That raises another obvious question. Could the $75 million ceiling make early token allocations more sought-after, unleashing a frenzy of get-rich-quick-induced FOMO in the first round?
Possibly. Reiners says that’s one potential outcome:
“If investors expect a successful issuer to conduct later offerings at a higher valuation, an initial allocation may become more attractive precisely because it is limited.”
However, that’s not dissimilar to how many token and equity sales are currently structured. SpaceX sold fewer than 5% of its total equity during the recent IPO. “Scarcity in both token sales and exempt securities offerings of traditional securities long predate this proposal — issuers have always been able to limit round sizes and can continue to do so,” says Tessler.
Non accredited investors also won’t be able to go “all in” on any one token sale like they have in the past. Tessler says the SEC’s proposal limits them to buying “10% of the greater of their income or net worth,” regardless of which round they participate in.
Related: White hat hacker recovers $2M from faulty 2016 ICO smart contract
Why this probably won’t be 2017 all over again
There are other reasons not to expect 2017 to return — not least because a generation of crypto investors have been burned by the extravagant promises and terrible tokenomics of previous ICOs. Up to 90% of projects funded via ICOs between 2017 and 2019 ended up failing. Reiners points out that fundraising markets are “shaped by investor appetite, token economics, liquidity, custody, and the reputational damage left by the last ICO cycle.”
The SEC estimates that around 130 offerings would use the two new exemptions each year, and around 475 issuers will potentially use the broader investment contract safe harbor. That’s less of a tsunami and more of a steady trickle.
SEC proposed long-awaited regulation for primary token issuance. Source: Galaxy.
But the SEC proposal is still very positive for token issuers trying to navigate a legal minefield around securities laws in the US — the kind Tezos and Telegram would have chewed their right arms off after their multimillion-dollar US securities-law battles.
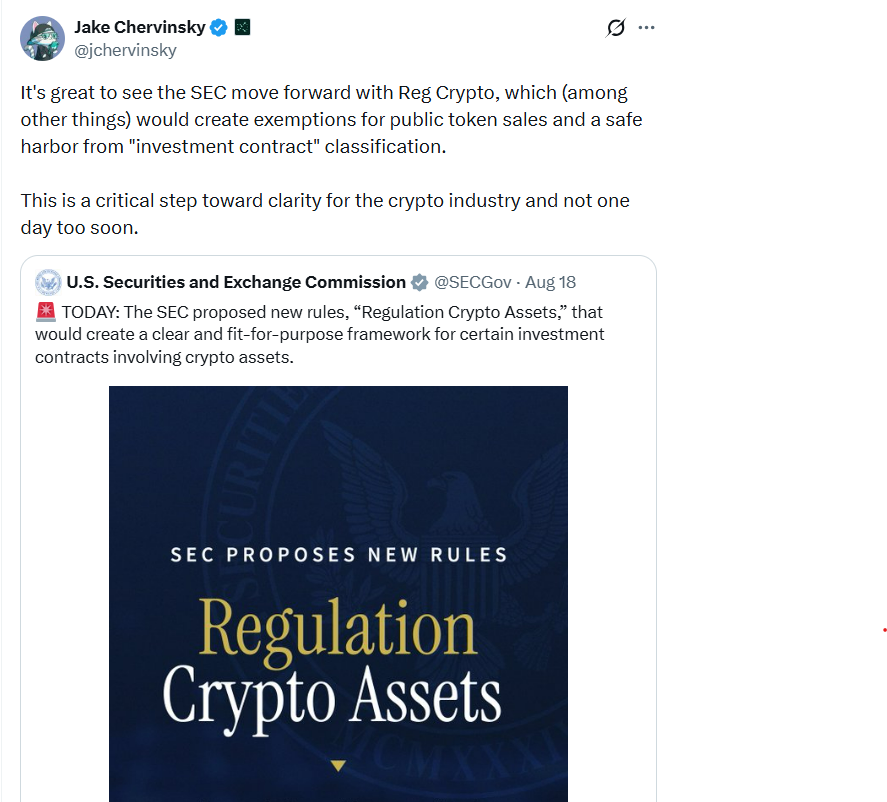
Rather than force issuers to self-evaluate whether their offerings fit within existing securities law frameworks, the SEC is proposing an explicit regulatory pathway for raising capital. As crypto lawyer Jake Chervinsky says, “not one day too soon.”
What happens when the token starts trading?
There are some potential minefield though. The SEC’s proposal says the investment contract associated with a crypto asset can continue to transfer to subsequent purchasers in secondary market transactions until the crypto asset separates from the issuer’s representations or promises.
In other words, if the team selling a non-security token suggest that investors in the secondary market can reasonably expect to profit from essential managerial team efforts, then it could become subject to an investment contract.
Related: ‘We refused to do an ICO’: The truth behind Canton’s tokenomics
Hinkes sees that creating a potential problem:
“If a transaction of a non-security covered crypto asset causes the transfer of the investment contract from cryptoasset seller to cryptoasset buyer, there is a risk that the sale of the crypto asset would be viewed as a securities transaction.”
That could become a problem for exchanges and other trading venues.
A new route for fundraising — but old risks remain
SEC moves forward with Reg Crypto. Source: Jake Chervinsky
The potential for tokens to fall into a no man land between security and non-security also worries Reiners. He says that projects could learn how to operate within the new framework without addressing the underlying investor protection concerns:
“A public offering exemption could become a vehicle for regulatory arbitrage […] A token issuer may satisfy the formal conditions for an exempt sale while continuing to market an asset whose value depends heavily on the issuer’s managerial efforts.”
That would leave retail investors in the same grey area as a decade prior, exposed to “opaque disclosures, concentrated insider holdings, and aggressive promotion.”
Magazine: Bitget CEO isn’t buying the Bitcoin rally — She’s waiting for $50K
Cointelegraph publishes long-form journalism, analysis and narrative reporting produced by Cointelegraph’s in-house editorial team with subject-matter expertise. All articles are edited and reviewed by Cointelegraph editors in line with our editorial standards. Some articles contain affiliate links, from which Cointelegraph may earn a commission. These relationships do not influence which products we review or our editorial conclusions. Content published in here does not constitute financial, legal or investment advice. Readers should conduct their own research and consult qualified professionals where appropriate. Cointelegraph maintains full editorial independence.
Japan’s regulators are racing to modernize national settlement systems to prevent institutional investors and foreign capital from fleeing to overseas markets.
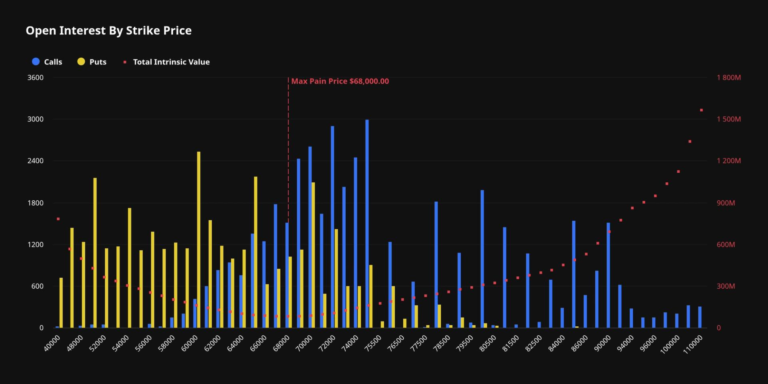
Friday’s expiry follows bitcoin’s surge from $62,000 to $80,000, leaving market makers with increased exposure to manage around several key strike prices.
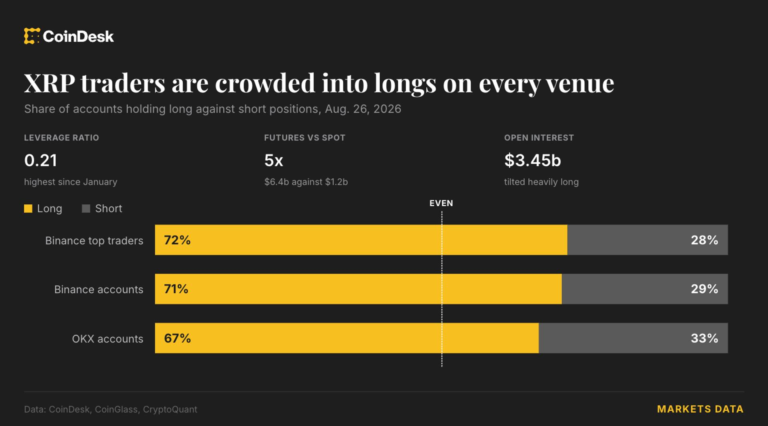
CryptoQuant data show XRP’s estimated leverage ratio on Binance at its highest since January, with long accounts outnumbering shorts as futures volume runs more than five times spot trading.
The crypto infrastructure firm failed to get approval when it first sought a U.S. charter, and the company is quickly back with what it said would be a narrower effort.