Home Blog Page 221

Movement and Zoth Target $1B Stablecoin Payments Corridor With RWA Yield Layer

0

Movement Network has signed a definitive agreement with Zoth to build a $1 billion cross-border payments corridor and stablecoin yield infrastructure for fintechs, neobanks and payment providers.

The deal places Zoth as Movement’s native real-world asset yield layer.

Under the agreement, partners building on Movement will be able to offer eligible users yield on stablecoin balances through Zoth’s zVault product, without structuring the underlying asset strategy themselves. Movement will provide the blockchain settlement layer, liquidity infrastructure and distribution network, while Zoth will supply the yield product and payment corridor infrastructure.

The announcement comes as Movement sharpens its focus on stablecoins, remittances and cross-border payments.

For users in emerging markets, the pitch is simple: stablecoins are already used as digital dollar accounts, but those balances often remain idle.

Movement and Zoth are trying to turn those balances into productive assets.

What the Movement – Zoth agreement covers

Zoth’s zVault is described as a yield-generating vault backed by investment-grade instruments. According to Movement, the product offers up to 12% yield with no lockup, with the underlying strategy linked to Brazilian credit card receivables settled through Visa and Mastercard acquiring infrastructure.

The vault will be launched on Movement.

Eligible partners would be able to integrate the product into their own apps while keeping the customer relationship.

Movement said Zoth has already processed more than $400 million in payment volume across South Asia, Southeast Asia and the Middle East and North Africa. The combined target for the Zoth-Movement ecosystem is $1 billion in payments volume.

The agreement also gives Movement exposure to regulated payment corridors.

Zoth previously signed a strategic partnership framework with Bakkt to support compliant cross-border stablecoin payments across emerging markets. That arrangement gave Zoth access to Bakkt’s U.S. licensing stack, including money transmitter licenses, a New York BitLicense and FinCEN MSB registration.

Through Bakkt and Movement, Zoth says it can serve users across all 50 U.S. states. The company has also secured a Money Services Business license in Canada, creating a route to serve diaspora payment flows.

The deal reflects a broader shift in stablecoins

Stablecoins are no longer being treated only as trading collateral or exchange liquidity. They are increasingly being used as payment, treasury and savings infrastructure, especially in markets where banking access is limited or local currencies are volatile.

Stablecoin transaction volumes reached $33 trillion in 2025, up 72% from the previous year, according to Artemis Analytics data cited by Bloomberg Law. USDC accounted for $18.3 trillion of that total, while USDT recorded $13.3 trillion.

That scale has attracted payment companies, banks and fintechs.

For emerging-market users, however, dollar stablecoins solve only part of the problem.

They can help protect against local currency depreciation, but they do not automatically generate yield. Yield products have typically required access to brokerage accounts, regulated banking relationships or DeFi protocols that may carry higher complexity and risk.

Movement and Zoth are trying to package payment settlement and yield access into one infrastructure layer.

If it works, fintechs and neobanks could offer stablecoin savings-like products without becoming asset managers or building their own treasury desks.

The Movement-Zoth deal fits into a wider race to build stablecoin payment infrastructure

In March, Mastercard agreed to buy stablecoin payments infrastructure firm BVNK for up to $1.8 billion. Mastercard expects the acquisition to support cross-border remittances, business payments and payouts using stablecoins, citing speed, cost and availability as advantages.

OpenFX, a stablecoin-based foreign exchange and payments startup, also raised $94 million in March to expand in Southeast Asia and Latin America. The company said its annualized payment volume grew from $4 billion to $45 billion in a year, driven by demand from fintechs, neobanks and payroll providers.

Klarna has also moved into stablecoins.

The Swedish fintech announced plans to launch KlarnaUSD, a dollar-backed stablecoin designed to reduce cross-border payment costs. The token is being tested for a 2026 mainnet launch and will run on Tempo, the blockchain developed by Stripe and Paradigm.

The trend is also visible in emerging-market currency flows.

Turkish lira-pegged stablecoins became the second-most used stablecoins among clients of Zodia Markets in 2025, behind dollar-backed tokens. Zodia said lira-pegged stablecoins were faster, more reliable and cheaper than sending lira through correspondent banking rails.

The risk question – how yield is generated and how risk is disclosed?

A stablecoin yield product backed by receivables is different from holding a plain dollar stablecoin. It may involve credit risk, liquidity risk, FX hedging risk and jurisdictional risk, even when the underlying assets are described as investment grade.

Movement says Zoth’s product is backed by short-duration investment-grade credit card receivables with a 45-day average maturity, FX hedging to USD, MPC custody through Fordefi, multisig guardrails, audited smart contracts and real-time monitoring.

Those controls may help institutional partners assess risk.

But they do not remove the need for clear disclosures, eligibility checks and local compliance, particularly in emerging markets where retail users may view dollar yield products as savings accounts.

A payments stack, not just a vault

The larger strategy is to make Movement a settlement backend for stablecoin payments and yield products.

Phase two of the integration is expected to add cross-border payment settlement through Zoth’s infrastructure across South Asia, Southeast Asia and MENA corridors.

It would position Movement as part of the operating layer for remittances, stablecoin savings and payment settlement, while giving Zoth broader distribution across blockchain-native fintechs.

The $1 billion target is significant, but the market is becoming crowded. Card networks, fintechs, exchanges and stablecoin issuers are all trying to own the same corridor between digital dollars, regulated settlement and user-facing financial apps.

Movement is betting on faster money movement added with yield on stablecoin holdings.

The above article “Movement and Zoth Target $1B Stablecoin Payments Corridor With RWA Yield Layer” was first published on AlexaBlockchain. Read the complete article here: https://alexablockchain.com/movement-and-zoth-target-1b-stablecoin-payments-corridor-with-rwa-yield-layer/

Read Also: Is India Moving From Crypto Uncertainty Toward a Clearer Policy Framework?

Disclaimer: The information provided on AlexaBlockchain is for informational purposes only and does not constitute financial advice. Read complete disclaimer here.
apxUSD Loses Dollar Peg as Bitcoin Slide Squeezes STRC-Backed Collateral

0

Apyx Finance’s apxUSD stablecoin slipped to $0.94 after Bitcoin fell to $63K, the first concrete peg break in the chain linking Strategy’s BTC treasury to on-chain dollar instruments.

Apyx’s apxUSD, a dividend-backed stablecoin collateralized largely by the preferred shares of bitcoin-treasury companies, broke its $1 peg this week, falling to about 92 cents as Strategy’s STRC preferred stock dropped below par and bitcoin extended a steep selloff.

The stablecoin slipped to roughly 90 cents at its low on June 4 and was trading at 92 cents on Friday, according to CoinGecko, with roughly $476 million in circulating supply, DefiLlama.

apyxUSD price. Source: CoinGecko

apxUSD is among the first stablecoins to channel the preferred equity of digital-asset treasury companies into an onchain dollar. A stablecoin backed by the preferred stock of a company whose treasury consists mainly of a volatile asset, such as bitcoin, inherits that volatility.

What Apyx Says Happened

Much of the depeg came after the U.S. market close on June 3, said Parker White of Apyx Finance over a Telegram message with The Defiant.

“Given the preferred stock collateral, there is a liquidity mismatch between crypto that trades 24/7 and STRC, which only trades on the Nasdaq,” he told The Defiant.

That mismatch matters because the Foundation aims to hold an equivalent mix of assets, White said. Filling overnight redemptions with stablecoins on hand “creates a potential issue if the preferred stocks fall significantly at the open” — a particular risk given how STRC moved on June 3.

“STRC fell pretty violently on June 3rd (-2.13%),” White said, calling it one of the stock’s largest single-day moves since Feb. 5. “This created a lot of panic that caused other market participants to step away and market sellers to be price agnostic.” Dislocations in apxUSD’s Pendle and Morpho markets compounded the stress, he added.

apxUSD has “historically had 60-90% in the prefs,” with the remainder “held in stables like USDC,” White said. Under normal conditions, that buffer dampens apxUSD’s volatility relative to STRC itself. apxUSD is Apyx’s non-yield base token; its yield-bearing counterpart, apyUSD, accrues STRC dividends.

There is no fixed threshold or automatic trigger tied to the peg, White said. During periods of severe stress, “the Foundation wants to avoid creating issues by fire selling prefs into a dropping, reduced liquidity market and creating extra slippage,” he said, so it may buy back or redeem apxUSD below net asset value to limit slippage and support the collateralization ratio. Those buybacks and redemptions typically occur during U.S. market hours, he said.

The Strategy Connection

Apyx’s primary collateral is STRC, a variable-rate perpetual preferred stock issued by Strategy, the largest corporate holder of bitcoin. STRC carries a $100 par value and an 11.5% annual dividend, and Strategy has described it as the largest preferred stock by market capitalization in the world, at about $8.5 billion. More than $270 million of STRC is held across DeFi protocols including Apyx and Saturn, the company said in a May filing.

The link to bitcoin runs through Strategy’s balance sheet. The company holds 843,706 BTC as of June 1, worth about $52 billion at Friday’s prices and acquired for roughly $63.8 billion, leaving an unrealized loss of about $11 billion. When STRC trades below $95, Strategy is contractually required to raise its dividend by 0.5%; the stock fell to an intraday low near $94.60 on June 3.

Bitcoin traded around $60,000 on Friday, down about 17% over the week and roughly 50% below its October 2025 high near $128,000, CoinGecko data show. Strategy sold 32 BTC for about $2.5 million in May to fund STRC dividend payments, its first bitcoin sale since 2022.

White said the Foundation will release “a comprehensive review on what happened, how the protocol weathered the storm, and some changes they plan to make,” both immediately and over time, to reduce volatility after hours.

Bitcoin Slumps Toward $61,000 as Zcash Bug, ETF Outflows and Strategy Sale Deepen Crypto Rout

0

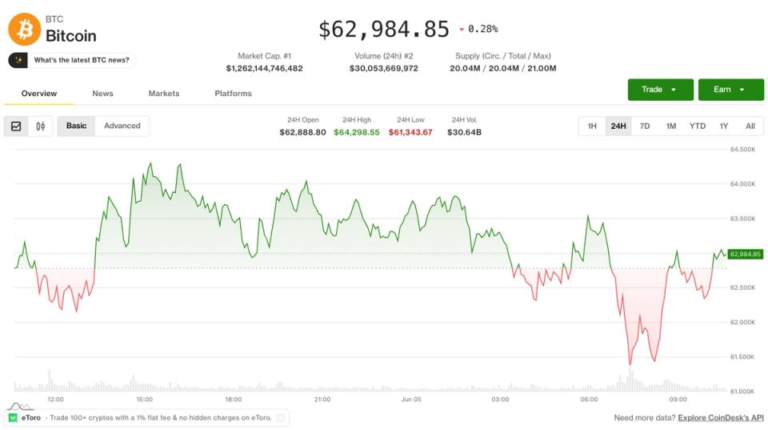
Bitcoin fell toward $61,000 on Friday, extending a weekly slide of about 16% and leaving it roughly 50% below its October 2025 record near $126,000. At the time of writing, Bitcoin was trading around $62,109, with an intraday high of $64,380 and low of $61,407, according to CoinMarketCap data.

Bitcoin fell toward $61,000 on Friday, extending a weekly slide of about 16% and leaving it roughly 50% below its October 2025 record near $126,000. Image Credit: CoinMarketCap

The move capped one of the sharpest risk resets in crypto this year.

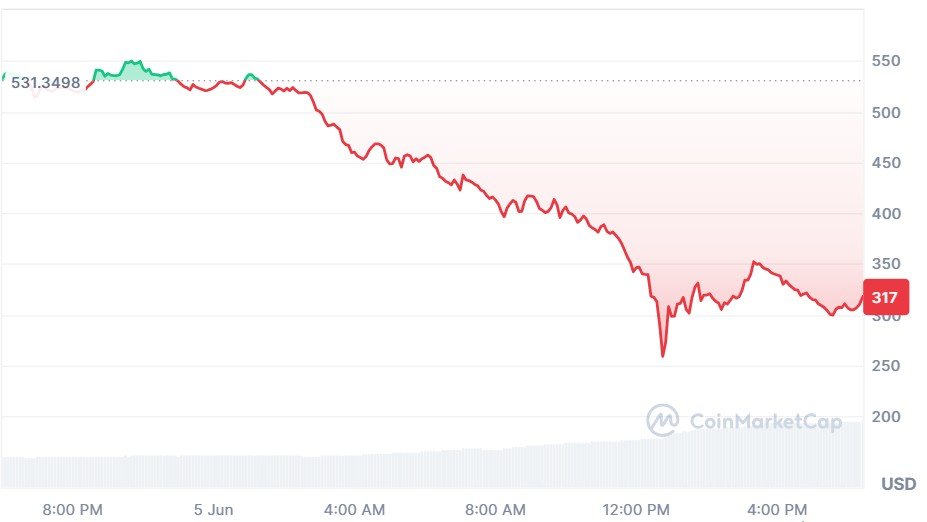
Crypto’s total market cap dropped to $2.14 trillion, as traders cut exposure across Bitcoin, Ether and smaller tokens. A mix of macro pressure, forced liquidations, ETF redemptions, and a fresh confidence shock from Zcash triggered this decline.

The privacy token ZEC plunged after Shielded Labs disclosed a critical flaw in Zcash’s Orchard shielded pool. The bug could theoretically have allowed undetectable counterfeit ZEC minting and had existed since Orchard’s activation in 2022, according to the disclosure.

The vulnerability has now been patched.

But the market reaction shows the harder problem: investors cannot easily prove whether the flaw was ever exploited. That uncertainty hit ZEC first, then spilled into broader altcoin risk, particularly assets where trust depends on complex cryptography and opaque supply verification.

ZEC fell more than 40% after the disclosure. Shielded Labs has proposed an upgrade that would allow verification of the privacy coin’s supply, an attempt to restore confidence after the incident.

Zcash (ZEC) plunged after disclosure of a critical Orchard pool bug that could have enabled unlimited counterfeit ZEC
Zcash (ZEC) plunged after disclosure of a critical Orchard pool bug that could have enabled unlimited counterfeit ZEC. Image Credit: CoinMarketCap

Bitcoin was not directly affected by the Zcash bug.

Still, in fragile markets, unrelated shocks often become liquidity events. Traders sell what they can, not only what caused the stress.

That dynamic was visible in derivatives markets.

Ryan Lee, Chief Analyst at Bitget Research, said the decline was driven by a broad risk-off move across global markets that triggered “the largest crypto liquidation event since January 2026,” with about $1.8 billion in leveraged positions wiped out over the past 24 hours.

“U.S. equities declined, oil remained elevated near $95-$97 per barrel due to geopolitical concerns, and investors continued to scale back expectations for near-term Federal Reserve easing,” Lee said. “The shift in sentiment pushed Bitcoin into the low $60,000 range and Ether toward $1,800.”

The scale of liquidations mattered more than the headline price move.

More than $1.5 billion of the liquidations came from long positions, according to Lee, showing how much bullish leverage had accumulated before the selloff. Open interest fell sharply, while funding rates turned negative as traders were forced out of crowded positions.

“The speed of the move suggests market structure was the primary driver of the selloff,” Lee said.

That makes this decline different from a simple spot-market retreat.

Macro conditions created the spark. Leverage supplied the fuel. Once Bitcoin broke lower, futures positions were closed automatically, deepening the move and pushing prices through levels that discretionary traders were watching.

“Macro conditions created the catalyst, but leverage amplified the decline,” Lee said. “Similar episodes over the past two years have occurred when crowded positioning met an external shock, creating rapid liquidations across futures markets.”

The external shock is not only crypto-specific.

Global markets are again trading around oil, inflation and geopolitical risk. Brent crude remained near $95 a barrel on Friday, while WTI traded above $92, as markets assessed Middle East tensions, Iran-related negotiations and supply disruption risks around the Strait of Hormuz.

Those pressures are feeding into the Federal Reserve debate.

Higher oil prices make inflation harder to bring down. That reduces the case for rapid rate cuts and raises the cost of holding long-duration, speculative assets. Bitcoin has increasingly behaved like a high-beta macro asset during periods of funding stress, even when some investors still describe it as an inflation hedge.

That explains the uncomfortable market signal.

Bitcoin can trade with gold when investors worry about currency debasement or inflation. It can also trade like technology stocks when liquidity tightens. In the latest selloff, the second impulse dominated.

ETF flows added another layer of pressure.

U.S. spot Bitcoin ETFs had seen 13 straight sessions of outflows totaling roughly $4.4 billion before recording a small $3.05 million inflow on Thursday, according to CoinDesk. Total Bitcoin ETF holdings were down about 7.2% from their October 2025 peak to 1.28 million BTC.

It’s crucial because ETFs have become one of Bitcoin’s key marginal buyers.

When ETF demand is strong, it can offset selling from miners, traders and early holders. When ETF demand weakens, Bitcoin becomes more dependent on spot buyers and corporate treasuries to absorb supply.

That is why Strategy’s Bitcoin sale unnerved the market.

Strategy, the largest corporate holder of Bitcoin, sold 32 BTC between May 26 and May 31 at an average price of $77,135, raising about $2.5 million net of expenses and fees. The company said it still held nearly 844,000 BTC, with an average purchase price of $75,699.

The sale was tiny compared with Strategy’s overall holdings. But symbolically, it sent negative messege in the matket.

Saylor had spent years positioning Strategy as a permanent Bitcoin accumulator. Even a small sale created questions over whether the company’s financing model, preferred dividends and debt-linked obligations could force more disposals if market conditions deteriorate.

The sale contributed to market anxiety, even though the amount sold was immaterial relative to Strategy’s balance sheet.

However, Standard Chartered’s Geoffrey Kendrick maintained a $100,000 year-end Bitcoin forecast despite the “painful” week.

So, did Strategy’s sale cause Bitcoin’s decline?

Not by itself.

It’d be better to say that it became a psychological accelerant. The market was already dealing with ETF outflows, macro stress, weak liquidity and a derivatives flush. Strategy’s sale challenged one of the market’s strongest narratives: that the largest corporate Bitcoin holder would never sell.

That was enough to worsen sentiment.

Saylor views the broader decline as a capital rotation toward artificial intelligence rather than a fundamental rejection of Bitcoin. The Wall Street Journal reported that he described the slump as investors redirecting funds toward AI opportunities.

That rotation is visible across markets.

Equities tied to artificial intelligence have continued to draw capital, while crypto has struggled to rebuild momentum after its 2025 peak. Bitcoin’s underperformance against major equity benchmarks this year has made the asset more vulnerable to redemptions from institutions that entered through ETFs.

The immediate technical focus is now $61,000.

A hold above that level could allow a short-term rebound toward $62,500 or $64,000, especially after the forced liquidation of crowded long positions. CoinDesk analysts described the recent rebound toward $64,000 as an oversold bounce rather than confirmation of a trend reversal.

A break below $61,000 would be more serious.

It would put the $60,000 area in focus and could open the path toward $55,000 if macro data disappoints, ETF outflows resume, or traders rebuild short exposure. Friday’s U.S. nonfarm payrolls report is therefore important because it will shape expectations for Fed policy.

A strong jobs report may reinforce the higher-for-longer rate narrative.

A weak report could cut two ways. It may support rate-cut expectations, which could help risk assets. But it could also deepen concerns about growth, encouraging investors to reduce exposure to volatile assets.

For now, Lee argues that the main signal is the leverage reset.

“The key signal is not the decline in asset prices but the scale of leverage removed from the system,” he said. “With speculative positioning reduced and open interest resetting, markets are likely to become increasingly driven by spot demand, ETF flows, and macroeconomic developments rather than derivatives-led momentum.”

That is the central question for Bitcoin after the crash.

If spot demand returns and ETF flows stabilize, the selloff may become another leverage-clearing event in a longer cycle. If institutional outflows persist and macro pressure intensifies, Bitcoin’s fall from its October peak could become a deeper repricing of the post-ETF bull market.

The above article “Bitcoin Slumps Toward $61,000 as Zcash Bug, ETF Outflows and Strategy Sale Deepen Crypto Rout” was first published on AlexaBlockchain. Read the complete article here: https://alexablockchain.com/bitcoin-slumps-toward-61000-zcash-bug-etf-outflows-strategy-sale-deepen-crypto-rout/

Read Also: Is India Moving From Crypto Uncertainty Toward a Clearer Policy Framework?

Disclaimer: The information provided on AlexaBlockchain is for informational purposes only and does not constitute financial advice. Read complete disclaimer here.
The Hyperinflation Of 1971 At The Kindergarten

0

I’m pretty sure it was 1971, but it could have been 1972. In any case, it was in kindergarten, and I was five years old. Our teachers had set up a system to motivate us kids to behave well. They had hung a big board on the wall, with all of our names listed. If you were particularly well-behaved, kind, helpful, or polite, they drew a black dot next to your name. Misbehave, and they gave you a red one. It was all about following the kindergarten rules, and the absolute transparency of it motivated most of us to try our best.

At some point, an extra prize was introduced for exceptionally good behavior: a small piece of fabric. From the group’s standpoint, that was worth much more than the top ranking in a row of black dots. And it was tangible. You could prove your elite status, even out in the sandbox.

Eventually, a trading system developed between us kids. For a scrap of fabric, you could get a bucket of sifted sand. For two, you could get a piece of candy. Suddenly, we could trade labor (sifting sand) for status symbols or sweets.

Then one day, a new teacher arrived. For whatever reason, she much more generously handed out those scraps of fabric. She simply changed the rules governing their distribution. All of a sudden, everyone had them, and you had to spend four for a piece of candy instead of two. Some of the kids started to complain. Their hard-earned scraps of fabric were now worth less, and they demanded more of them.

As you’d expect, the fabric scraps were given out more and more freely. Before long, anyone could take as many as they wanted. Eventually, they were lying around all over the place. They were worthless. No one wanted them anymore. You couldn’t trade them for anything. And so, at just five years old, I experienced genuine hyperinflation.

What does this have to do with Bitcoin?

In kindergarten, the rules were simply changed. The new teacher wanted to be nice, we kids whined, and suddenly more and more fabric scraps were handed out.

The rules of Bitcoin simply cannot be changed.

It’s a completely different story with our fiat currencies. They too have rules. The problem is that no one can ensure those rules are actually followed. Here is an example: the European Central Bank is not allowed to permanently finance governments through bond purchases, yet it does so anyway, brazenly and with no one doing—or even being able to do—anything about it. And who would intervene anyway?

Here’s another example. The Maastricht Treaty’s Stability and Growth Pact stipulated that the budget deficits of EU member states could not exceed 3% of their GDP, although permissible exceptions were built in. However, between 2000 and 2010, the Stability Criteria were repeatedly violated without sanctions—not only by Greece (11 times) but also by larger countries such as Italy (seven times), France (six times), and Germany (five times). According to the Maastricht Treaty, there are clear sanctions for countries that unlawfully fail to adhere to the deficit limit. But not once has such a sanction been imposed. No attempt was ever even made.

This may have been politically expedient and justified for whatever reason, but it shows how difficult it is for us to adhere to the rules. It’s like the New Year’s resolutions that we make with the greatest of convictions, but then usually don’t stick to for very long. The result is what matters. Currencies inflate and, sooner or later, become worthless. The U.S. dollar has lost 97% of its value over the last hundred years. The British pound, which originally represented a pound of silver, has suffered the same fate. All because more and more new dollars, euros, or pounds have been created, or to put it differently, printed.

The outcome is the same: when the fabric scraps become worthless, everyone who holds them loses their wealth.

This cannot happen with Bitcoin. Its rules are fixed, and no one controls the system nor can they simply change those rules.

Discover more in Bitcoin: The Honest Money!
This excerpt is just the beginning. Dive deeper into how inflation devalues your money, your savings, and your time in Bitcoin: The Honest Money by Alex von Frankenberg, Ph.D. The paperback is available now.

Order your copy here!

House GOP Moves to Limit Lawmakers’ Prediction Market Betting

Republicans in the US House of Representatives are moving to add prediction market restrictions to a stalled congressional stock trading ban, as lawmakers scrutinize whether members of Congress should be allowed to wager on elections or public policy.

House Administration Committee Chair Bryan Steil plans to attach prediction market provisions to H.R. 7008, the House’s stalled stock trading ban bill, before it reaches the floor, Bloomberg Government reported Thursday.

Steil said he expects House leaders to schedule a vote on the measure, which would combine stock trading limits with new restrictions on lawmakers’ use of prediction markets.

The push comes amid growing scrutiny of prediction markets and renewed efforts to tighten rules on lawmakers’ financial trading.

No full ban on lawmakers’ prediction market use in Steil proposal

Steil’s proposal does not seek to ban prediction markets outright for members of Congress, but would restrict certain types of contracts lawmakers could trade. He said bets tied to sports or entertainment outcomes, such as the Super Bowl, would remain allowed, while contracts tied to elections or public policy would be limited.

Steil said the House still lacks clear rules for how members should engage with prediction markets.

“I don’t think this is a critique of the underlying product one way or the other,” Steil said.

Related: Polymarket users cry foul after Strategy sale market resolves to ‘no’

Politico says influencers promoted Polymarket after payments

According to a Friday report by Politico, influencers promoted Polymarket after receiving payments linked to the company’s chief marketing officer.

PayPal transaction records reviewed by Politico show at least $350,000 in payments routed through a personal account tied to CMO Matthew Modabber, alongside a broader flow of more than $2.5 million to hundreds of recipients over 14 months.

At least 20 creators later posted about Polymarket on X, often without disclosing financial ties, including figures such as Brian Krassenstein and Riley Gaines.

Cointelegraph reached out to Polymarket for comment on the promotions but had not received a response by publication.

Source: Brian Krassenstein

Polymarket attracted attention in 2024 after users successfully bet on Donald Trump’s election victory, reinforcing claims that prediction markets can reflect political outcomes in real time.

Prediction markets have also faced regulatory pushback in multiple jurisdictions over election-related contracts, gambling concerns and alleged insider-style trading.

Magazine: Should users be allowed to bet on war and death in prediction markets?

Sky Launches Fixed-Rate Yield Product Built on Pendle, Targeting $6B sUSDS Pool

0

Sky (formerly MakerDAO) launched Fixed Yield on Wednesday — a term-based alternative to the variable Sky Savings Rate built on Pendle Protocol v2, giving sUSDS depositors a locked rate to a named maturity date.

Sky (formerly MakerDAO), the protocol behind the $11 billion USDS stablecoin, launched a fixed-yield product Wednesday that lets depositors lock in a set return to a named maturity date using Pendle’s yield-tokenization infrastructure. The product, called Fixed Yield, is now live at sky.money/fixed-yield, Sky said on X.

The launch targets users of sUSDS, Sky’s savings-rate token, which holds $6.16 billion in market capitalization, by offering a term-based alternative to the variable Sky Savings Rate (SSR). At the time of writing, th fixed-yield market shows a 5.38% APY with a Nov. 26 maturity date, per the sky.money product page. The SSR’s own variable rate sits at 3.60% APY for the same sUSDS pool on DefiLlama.

The product is built on Pendle Protocol v2, which splits yield-bearing tokens into Principal Tokens and Yield Tokens. When a user supplies USDS, USDC, or sUSDS into a Fixed Yield market, the protocol issues PT-sUSDS — a Pendle principal token that matures on a date chosen by Sky. Holding to maturity locks the entry rate. Exiting early means selling the PT position at prevailing market prices, which may be above or below the entry price.

Sky’s Role and Pendle’s Infrastructure

Sky sets the maturity dates when it opens each market. The rate itself is market-driven, set by trading activity in the Pendle pool rather than by Sky’s governance. Sky makes clear on its product page that it does not set, control, or guarantee the rate.

Sky (sky-lending) holds $5.91 billion in total value locked, per DefiLlama, making it one of DeFi’s largest CDP protocols. Pendle, the fixed-yield infrastructure layer, holds $1.23 billion in TVL across Ethereum, Arbitrum and Plasma.

The launch follows Wednesday’s Pendle listing on Revolut, the European fintech with roughly 20 million crypto users, which expanded token distribution but not Pendle’s actual fixed-yield product access. This integration goes the other direction: it brings Pendle’s PT mechanics onto Sky’s own product surface, inside the protocol rather than on a trading app.

The SSR has drifted lower over recent months. A fixed product offering a premium above spot gives rate-sensitive depositors a reason to commit capital to a term rather than stay floating.

bitcoin below $62,000 ahead of jobs data as Zcash bug rocks crypto

0

Earlier, Shielded Labs, a nonprofit developer on the privacy token system, disclosed a critical vulnerability in Zcash’s (ZEC) Orchard privacy pool that could have threatened the integrity of the token’s supply.

The vulnerability, if exploited, could have allowed an attacker to create an unlimited number of counterfeit ZEC tokens, completely undetected.

“Think of it as someone secretly gaining access to the Federal Reserve’s dollar printing press, except in this case, even the Fed wouldn’t be able to tell these extra dollars were printed,” wrote Omkar Godbole.

Importantly, the vulnerability was discovered with help from Anthropic’s recently released Opus 4.8 AI model, raising difficult questions for the entire crypto industry. More to come on that.

ZEC is now down 42% over the past 24 hours.

Coinbase Launches Pre-IPO Perpetual Futures, Starting with SpaceX

0

Coinbase International Exchange, operating through its BMA-licensed Bermuda entity, now offers USDC-settled perpetual futures on private-company valuations, with SpaceX as the first listing.

Coinbase has launched pre-IPO perpetual futures on its International Exchange, listing SpaceX as the first underlying asset.

The contracts are USDC-settled, trade 24/7 with no expiry, and are open to eligible users outside the United States, the company said in a blog post published June 3.

The product runs through Coinbase Bermuda Ltd., a Class F entity licensed by the Bermuda Monetary Authority. Maximum leverage is 5x. All profit and loss settles in USDC.

Valuation-Based Index Pricing

The SpaceX contract does not track a share price. It references a valuation-based index: a contract price of 1,735 implies a $1.735 trillion equity valuation. Coinbase uses this structure because a private company’s total share count is not disclosed until the final 424B4 IPO prospectus is filed, making per-share pricing unreliable before listing, per its help documentation.

When SpaceX files its 424B4, Coinbase will rebase the contract into a standard per-share stock perp via a P&L-neutral adjustment. Open positions carry through the transition without rollover.

The Competitive Field

Coinbase is not the first to list a SpaceX perp. Trade.xyz launched a synthetic SpaceX pre-IPO perpetual on Hyperliquid in May, with an implied valuation near $1.78 trillion. BitMEX announced a USDT-margined SpaceX perp (SPCXUSDT) on June 4, set to go live at 04:00 UTC on June 5, also with 5x leverage.

What separates the Coinbase product is its regulatory wrapper and conversion mechanics. Coinbase Bermuda holds a BMA Class F licence and commits to an automated IPO conversion backed by a published index methodology. BitMEX’s listing notes that conversion to a standard equity perp is at the exchange’s discretion.

Pre-IPO Markets Get a Derivatives Layer

The launch fits a wider push to apply market-structure tools to private-company valuations. Last month, Polymarket partnered with Nasdaq Private Market to launch prediction markets on private-company valuations, with early markets on OpenAI, Anthropic, and Stripe. Coinbase’s perp offers a different instrument — continuous leveraged exposure rather than discrete event outcomes — but targets the same structural gap: price discovery on companies not yet on public markets.

Brian Armstrong, Coinbase’s chief executive, said on X that pre-IPO perps are “great to get exposure to private companies before they go public (outside the U.S. only for now) and to help with price discovery.”

Coinbase has separately committed to launching perpetual-style equity index futures on its US-regulated Derivatives Exchange on June 14 — a different product aimed at US users trading market-sector exposure, not individual pre-IPO names.

Arthur Hayes dumps zcash holdings after Orchard Pool vulnerability revealed

0

Arthur Hayes, chief investment officer of Maelstromfund, said he liquidated his entire zcash (ZEC) position after a developer disclosed a potential critical vulnerability in the network’s Orchard Pool.

Hayes, who previously championed the privacy token, said on X that while he believed it was extremely unlikely that any minting would take place, it could not be cryptographically proven impossible.

The now-plugged vulnerability was disclosed by Shielded Labs, which said a major issue went undetected for four years and could have allowed a hacker to print unlimited counterfeit tokens, damaging trust in the crypto’s supply and its value. The token slumped following the announcement and was recently down 42% over 24 hours.

“I read about the exploit yesterday, and didn’t appreciate how it violated my narrative mental map,” said Hayes. “The 30% dump made me rethink, and I had to take profit on the entire position.”

The vulnerability, present since 2022, was discovered on May 29 and fixed June 1, Shielded Labs said.

Hayes, who also co-founded the BitMex exchange, said he would reevaluate his stance moving forward and that, if his assumptions were proven incorrect, he would buy ZEC again “hopefully at lower prices.”

Blockchain analytics and intelligence firm Arkham wrote on X that one large investor lost over half the value of his $174 million ZEC stash.

“He hasn’t sold ZEC for 6 months. Ouch,” said Arkham.

Crypto’s worst week since July 2024 deepens as BTC, ETH prices near critical support levels

0

The crypto market is teetering on the brink of a major breakdown in price after suffering one of its worst weeks since July 2024.

Bitcoin , currently trading around $62,500 has lost more 14.5% since midnight UTC on Monday morning, while ether (ETH) has plunged by more than 17%, dropping 5.5% on Friday alone.

Ether, the second-largest cryptocurrency, is now at its lowest level since April 2025, when it bounced at $1,420 before rallying to record highs over the subsequent four months. A break below that level would bring it toward 2022 bear-market levels, when it dipped below $900.

The broader altcoin market also suffered deep losses this week. One of the worst performers on Friday was zcash (ZEC), which tumbled by more than 30% after a security researcher found an exploit that would have minted “unlimited” tokens in its shielded pool.

There are multiple catalysts causing this week’s slide. Strategy (MSTR) Executive Chairman Michael Saylor attributed it to capital rotation in light of a series of artificial intelligence IPOs in the U.S., while onchain analysts are pointing towards a lack of spot crypto volume.

CryptoQuant notes that spot trading volume fell to $679 billion in April, the lowest monthly level since October 2023, indicating a lack of demand.

Derivatives positioning

  • BTC derivatives positioning has flipped from mild improvement to clear deleveraging this week. Open interest dropped 15% to $17 billion, with funding rates flipping negative to flat across multiple venues
  • At Deribit, the rate dropped to -15% annualized, a notable reversal from the prior positive regime. The three-month annualized basis fell to 2.7% from 2.9% last week, confirming a pullback in institutional risk appetite.
  • Options positioning has turned clearly defensive: Put/call volume has flipped to a 50/50 split over the past 24 hours, losing the prior call tilt, while the one-week 25-delta skew more than doubled to 27% from 13% a week ago. That signals a sharp escalation in demand for downside protection.
  • Front-end implied volatility (DVOL) has climbed further to 47, confirming a sustained bid that aligns with the broader deleveraging in derivatives.
  • Coinglass data shows $1.2 billion in 24-hour liquidations, with a 76-24 split between longs and shorts. Bitcoin ($364 million), ether ($291 million) and zcash ($107 million) were the leaders in terms of notional liquidations.
  • The Binance liquidation heatmap indicates $60,900 as a core BTC liquidation level to monitor, in case of a price drop.

Token talk

  • Zcash’s (ZEC) plight on Friday sowed seeds of doubt across privacy coins, with monero (XMR) losing 12% since midnight UTC and dash (DASH) dropping 9%.
  • ZEC’s losses were compounded by BitMEX founder Arthur Hayes, who said on X that his firm had sold its entire allocation of the token.
  • There were also heavy losses for , which tumbled by more than 10% after the project’s founder, Charles Hoskinson, said that he was “taking a break” after warning of ecosystem failures.
  • AI tokens lost their early week momentum as FET, NEAR and TAO fell 4%-6% despite outperforming the rest of the market on Monday.
  • One reason for altcoin holders to be hopeful is the fact that the average relative strength index (RSI) across all crypto pairs is in “oversold” territory, suggesting that a relief bounce could be on the cards this weekend.