Home Blog Page 122

Europe led on crypto regulation. Now implementation must match ambition

0

Europe has done something important. With MiCA, the EU created the world’s first comprehensive regulatory framework for crypto-assets. That is a significant achievement, not only for the digital asset industry, but for Europe’s wider ambition to lead in responsible financial innovation.

MiCA’s promise was clear: a harmonised single-market framework for crypto-asset services across the EU, greater clarity for users, more certainty for firms, and a level playing field for responsible operators willing to meet high standards.

Binance has supported that objective from the beginning, and we continue to support it today. But frameworks are only as strong as their implementation.

As MiCA moves from legislation to implementation, an important question is emerging: is the harmonised framework being implemented as intended?

That question matters far beyond Binance. Europe’s digital asset market is large, sophisticated and growing. Across the continent, millions of people use digital assets, innovative Web3 businesses are being built, and institutional participation continues to expand.

This ecosystem is part of Europe’s future competitiveness. Digital assets are about far more than trading. They represent new financial infrastructure: faster settlement, lower-cost payments, programmable products, digital ownership and more transparent markets.

Bitcoin is Close to Sealing a Key “W”-Shaped Reversal Pattern, Notes John Bollinger

0

Bitcoin (BTC) is completing a “perfectly fractal” reversal pattern that a well-known analyst hopes could end the bear market.

Key points:

  • Bitcoin is on the final leg of what could become a major “W”-shaped reversal pattern.
  • John Bollinger suggests that its success could “break” the downtrend in place since October 2025.
  • Institutional interest slowly returns as newly reclaimed $60,000 holds.

John Bollinger hints BTC price “W” reversal could break bears

In X posts on Friday, John Bollinger, creator of the Bollinger Bands volatility indicator, eyed a “W”-shaped double bottom on BTC/USD.

“$BTC has seen a series of bullish patterns broken, evidence of the power of the downtrend,” he commented

“Will this ‘W’ be the one that breaks the trend?”

“W”-shaped reversals involve two swing lows with a rejected rebound in between, with price ultimately breaking through that rejection level to form a new uptrend.

Bollinger uploaded a chart showing how neatly the current setup aligns with the lower band of the Bollinger Bands indicator on daily time frames.

“Note that it is perfectly fractal. The are small ‘w’s at the nadirs and a small ‘m’ at the apex,” he added, also pointing to a “W” on the weekly chart.

BTC/USD one-day chart with Bollinger Bands. Source: John Bollinger/X

Bollinger has been bullish on BTC for some time. In early May, he revealed a new long position via his Bitcoin investment vehicle.

As Cointelegraph reported, an increasing number of price indicators are flashing signals not seen since the last bear market in 2022. Despite this, market participants broadly believe that the next macro bottom is still to come and is due in Q3 or later.

Bitcoin ETF inflow comes amid major supply “absorption”

Continuing, analyst Axel Adler Jr., a contributor to onchain analytics platform CryptoQuant, stressed the significance of re-emerging institutional buyer interest.

Related: Bitcoin price tags $62.3K nine-day high after global stocks hit historic record

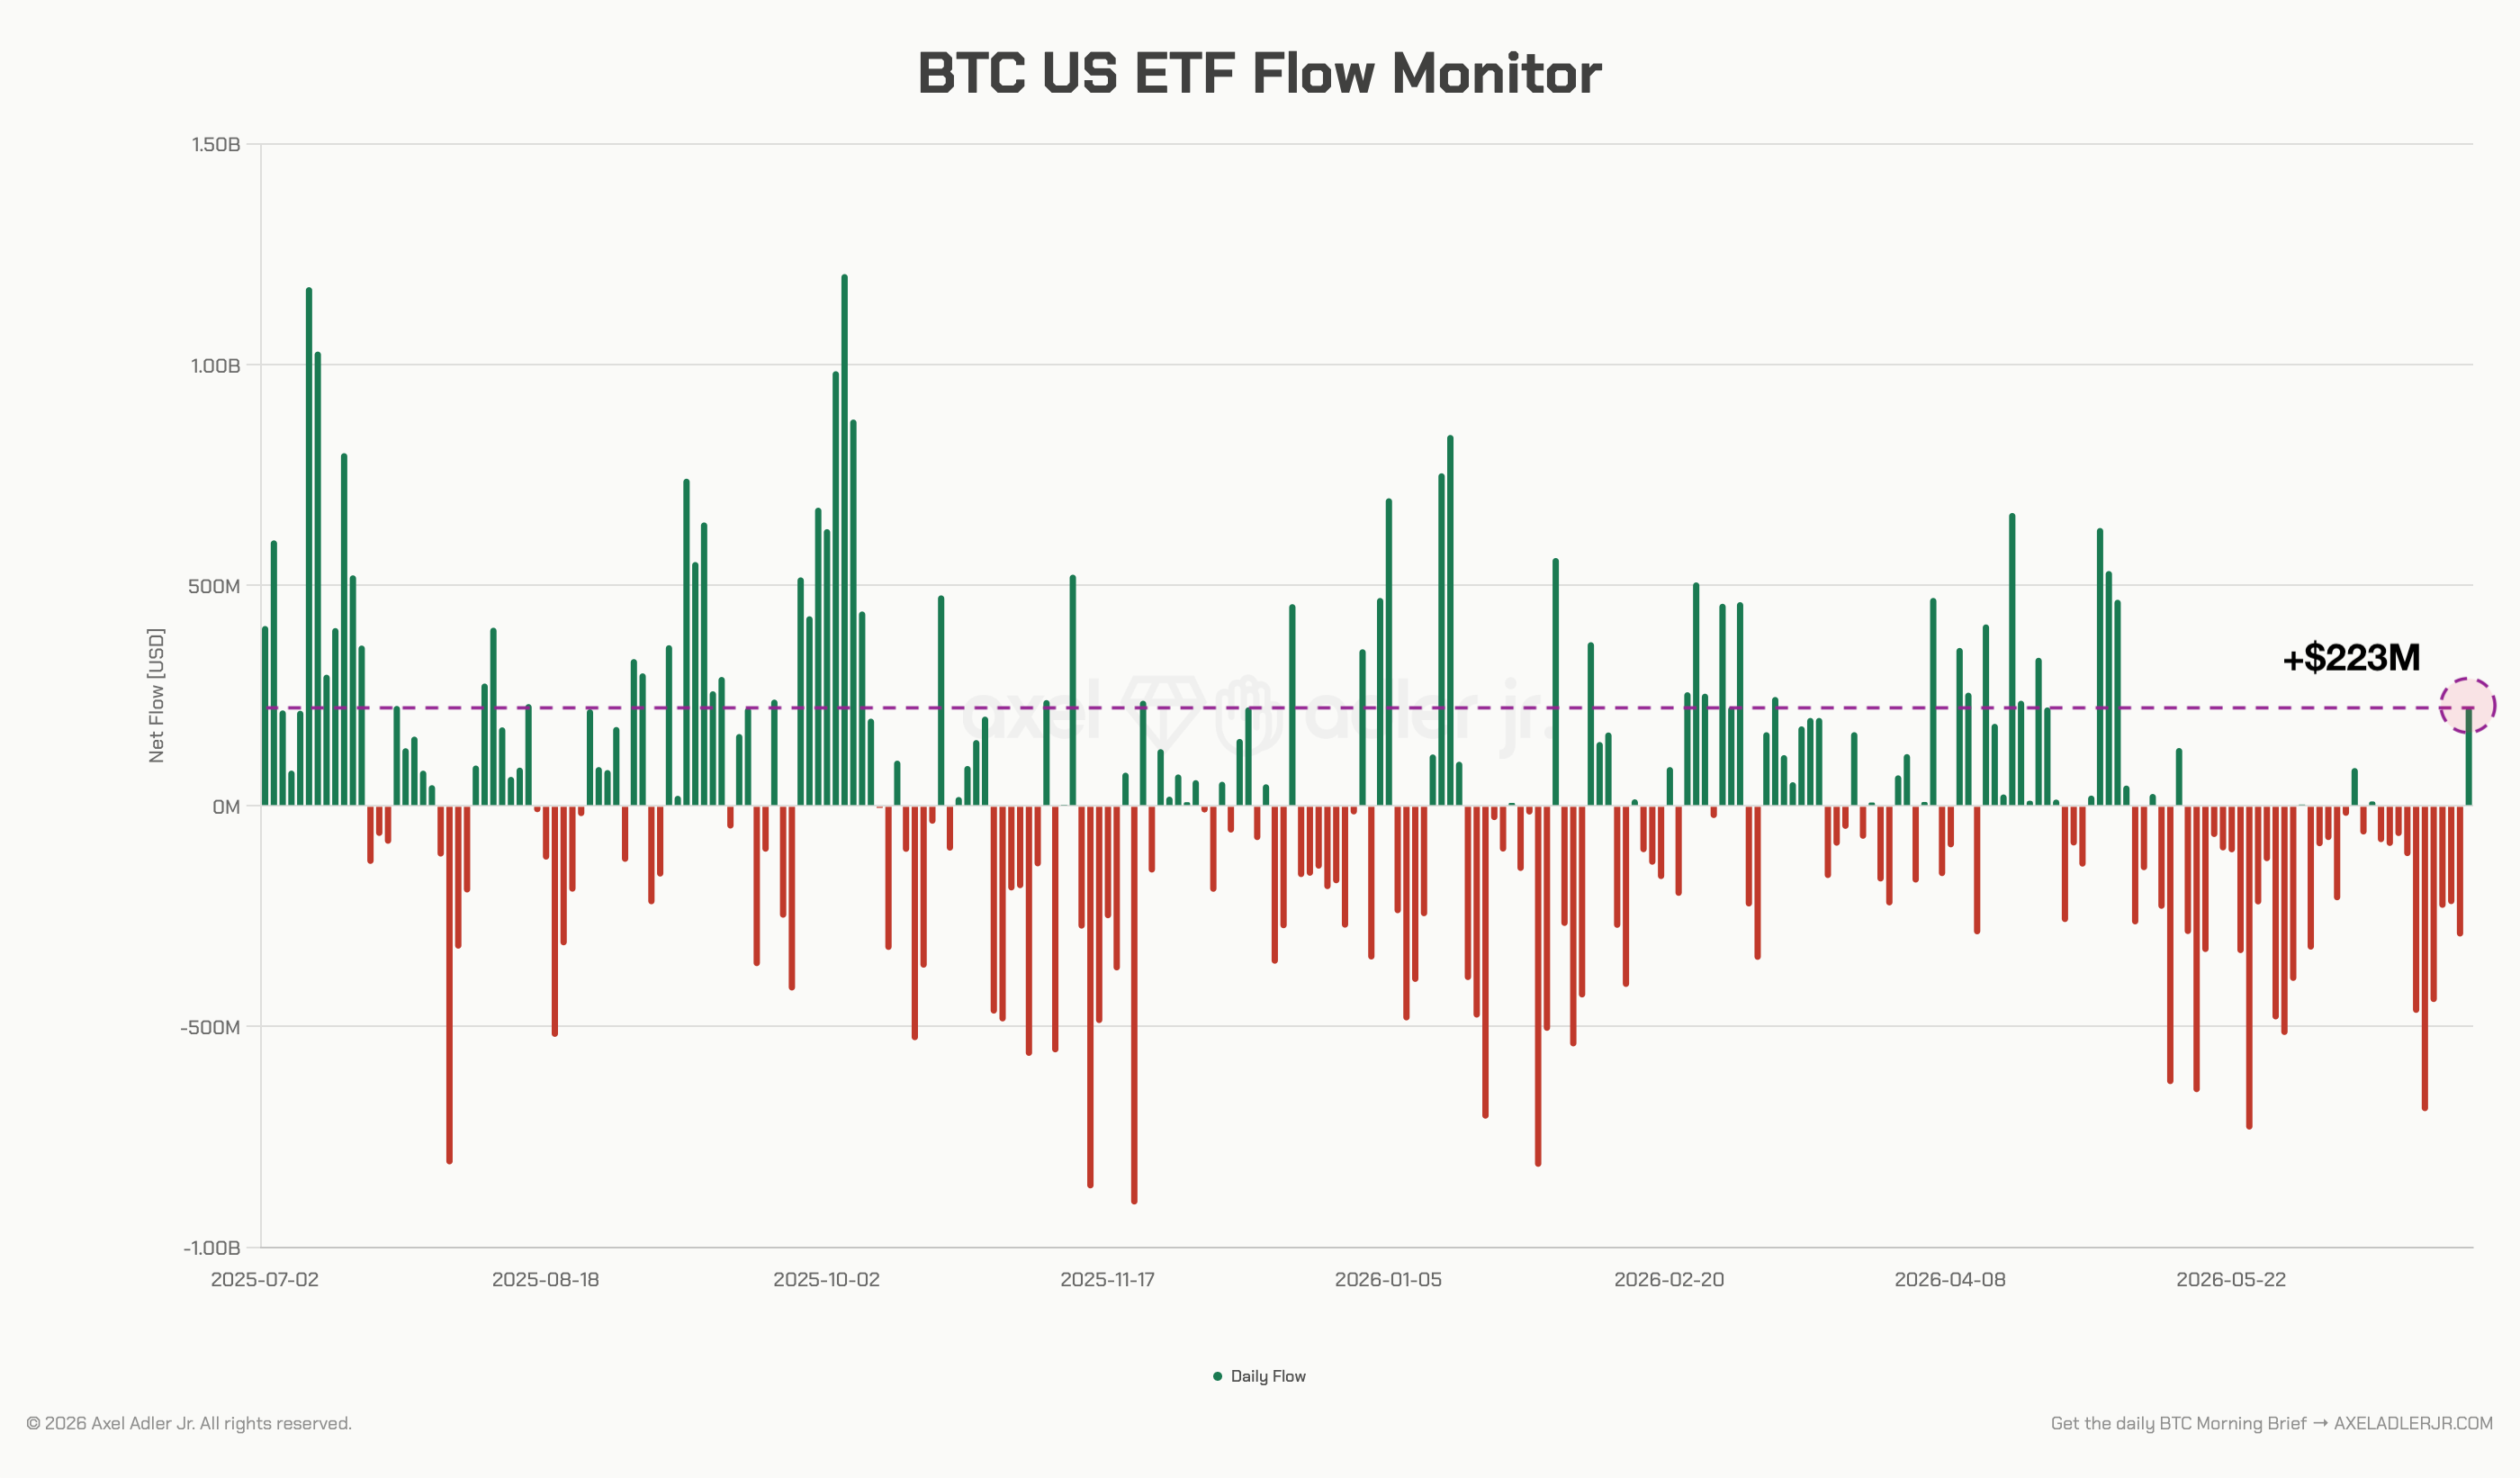
On Friday, the US spot Bitcoin exchange-traded funds (ETFs) saw their first net inflows in ten days.

“Bitcoin is in the late stage of the bear cycle, but the ETF segment has for the first time signaled that the pressure is easing,” he summarized on X.

US spot Bitcoin ETF netflows. Source: Axel Adler Jr./X

Trader Daan Crypto Trades acknowledged that while the $220 million inflows were “not massive,” they could have implications for BTC price support going forward.

“Also good to note how price has been holding this ~$60K region regardless of the many outflows. That will become meaningful if price does bounce further into next week as it means a lot of absorption has taken place,” he told X followers.

Revolut Notifies Customers of USDT Delisting

Revolut, a crypto-friendly digital banking platform headquartered in the United Kingdom, notified some users it will delist Tether USDt (USDT) stablecoin in August, citing regulatory and risk concerns.

In a Friday customer notice seen by Cointelegraph, Revolut said users will no longer be able to buy USDT starting July 6, with full delisting scheduled for Aug. 31, 2026.

If users do not sell or withdraw their USDT by the end of August, Revolut will automatically convert any remaining USDT holdings into users’ base currency at the day’s exchange rate, the company said.

USDT deposits will no longer be supported after July 30, 2026, after which any incoming USDT transfers will be rejected, it said.

The move highlights how major fintech companies are adjusting stablecoin access in response to shifting regulatory frameworks. Exchanges such as Coinbase began delisting USDT in Europe in 2024 to align with the EU’s Markets in Crypto-Assets (MiCA) requirements.

Revolut does not cite exact framework for delisting

Revolut has not clarified whether the USDT delisting will apply globally or only in specific jurisdictions.

Addressing the reasons for delisting USDT, Revolut cited “regulatory and risk considerations” without expanding what regulations specifically have triggered the move.

Source: Cointelegraph

The company was granted a MiCA license as a crypto asset service provider (CASP) in November 2025, according to the official register by the European Securities and Markets Authority (ESMA). The license was issued by the Cyprus Securities and Exchange Commission (CySEC).

Related: EU crypto rulebook faces enforcement challenge as MiCA transition ends

Cointelegraph approached Revolut for comment on the affected jurisdictions and the scope of its crypto offering but did not receive a response by the time of publication.

Tether refused to comply with MiCA

Tether’s USDT has been gradually delisted by CASPs in Europe since late 2024 as the stablecoin’s issuer refused to comply with the EU’s MiCA regulation.

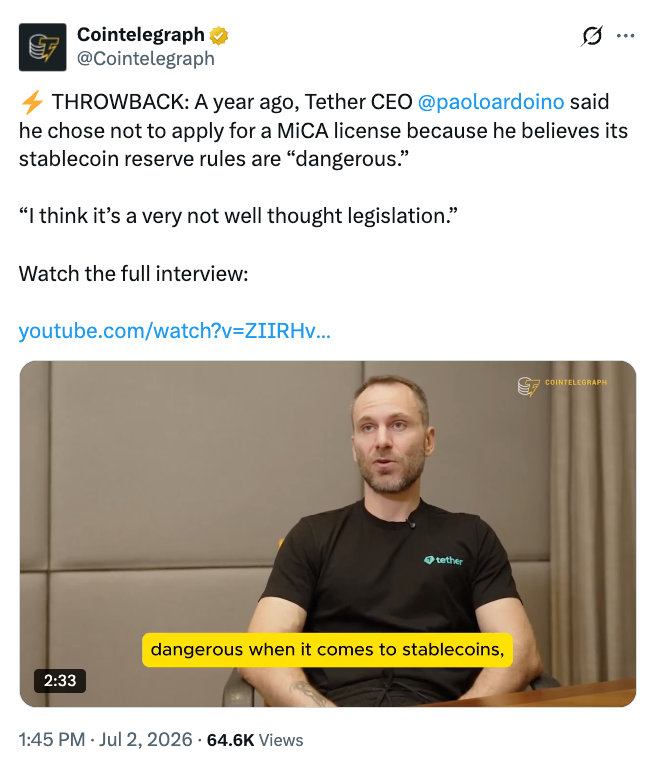
The company’s CEO, Paolo Ardoino, has repeatedly criticized perceived flaws in MiCA, including reserve requirements that apply to certain stablecoin issuers and require part of their reserves to be held with EU credit institutions.

Source: Cointelegraph

“I think it’s a very not well thought legislation,” Ardoino told Cointelegraph in a May 2025 interview.

At the time of publication, USDT is the third-largest crypto asset by market capitalization after Bitcoin and Ether, with a market value of $184 billion. Its largest competitor, Circle’s USDC, has a $73 billion market cap and ranks as the fifth-largest crypto asset, according to CoinGecko.

Magazine: Crypto wanted to overthrow banks, now it’s becoming them in stablecoin fight

Preferred Stock Is Becoming Bitcoin Treasury Firms’ Financing Tool Of Choice: Report

0

A new class of Wall Street securities has grown from an experiment into a multibillion-dollar market in under two years, and a June 2026 research report from BitcoinTreasuries.net argues the expansion has just begun.

The report, produced in partnership with the DeFi protocol Apyx, tracks the rise of preferred shares issued by public companies and backed by their bitcoin holdings. Such shares now carry a combined market value of about $13 billion. That figure represents close to 1% of the $1.3 trillion global preferred market, a share the report’s authors expect to reach 3 to 5% by 2030 and as much as 10%, or $130 billion, beyond that horizon.

The instrument sits at the center of a financing puzzle facing companies that hold bitcoin as a treasury asset. Firms such as Strategy, led by Michael Saylor, want long-duration capital to buy more bitcoin without diluting common shareholders or taking on debt that must be repaid at a fixed date. Bitcoin’s price swings make that balance difficult. 

Bitcoin traded near $124,720 in October 2025, then fell to below $60,000s by mid-June 2026, a drawdown of about 47% in eight months.

Preferred shares offer a path around the problem. When a company issues them, its common share count does not rise, so existing owners avoid dilution. The shares are classified as equity rather than debt, which means no maturity date and no forced repayment. In exchange, holders receive a dividend that ranks ahead of common stock.

 For income investors shut out of bitcoin’s upside, the structure converts the token’s volatility into a yield product.

Preferred shares are pushing Bitcoin expansion

Those yields dwarf what fixed-income markets pay. The five main bitcoin-backed preferred securities in the U.S. carry effective yields between 10.8% and 15.2%, against the 3 to 4%offered on high-yield savings accounts. 

Strategy’s lineup accounts for most of the market: STRF, STRC, STRK and STRD together hold a market value near $12.5 billion. Strive, an asset manager turned bitcoin treasury company, issued a fifth security, SATA, with a market value around $330 million.

The report’s central claim is that demand outstrips supply. Fixed-income institutions such as mutual funds, banks, pensions and insurers hold $10.9 trillion in U.S. treasuries. A shift of 10 to 20 basis points from that pool would generate $10.9 billion to $21.8 billion in demand, enough to validate the near-term market projection on its own. 

Supply, though, is capped by the amount of bitcoin available as collateral. Of the 20 million bitcoins in circulation, holdings in exchanges, spot ETFs and mining firms are excluded as customer assets or operating reserves. 

That leaves the 1.26 million bitcoins held in corporate treasuries, worth about $83 billion. Strategy alone controls some 845,000 of them, or 67%.

Collateral coverage is the feature the report leans on to make the case for safety. Bitcoin-backed preferreds maintain coverage ratios of 3.8 to 4.5 times, meaning issuers hold $3.80 to $4.50 in bitcoin for every $1 of preferred equity.

 By comparison, the median large-bank mortgage in the third quarter of 2025 advanced 76 cents against every dollar of home value. “The security of these instruments is significantly higher than 95% of the bonds in the market,” Jeff Walton, chief risk officer at Strive, said in the report, “because they’re actually backed by capital, not future cash flows.”

Not every firm qualifies to issue. Walton set out requirements: a clean balance sheet free of senior secured debt, scale to support an issuance of $100 million or more, and a team versed in tax treatment, covenant design and dividend policy. 

Encumbered bitcoin, he said, ranks ahead of preferred equity and would block most deals. Strive itself used a $225 million SATA offering in January to retire debt inherited from its acquisition of Semler Scientific, a move that left all of its bitcoin unencumbered.

The risks are structural rather than hidden. Strategy’s common stock, MSTR, acts as a volatility amplifier, and it has fallen more than bitcoin over the past year. “When bitcoin’s price declines, Strategy’s will dip more,” said Tony Lau, an investment partner at Primitive Ventures, who described a possible cascade in the stock. 

Three of the four Strategy preferreds trade at discounts to their $100 par value. The dividends themselves depend on a company’s ability to keep raising capital against a rising bitcoin price, though both Strategy and Strive have disclosed cash reserves sufficient to cover at least twelve months of payments.

Strategy CEO Phong Le told investors in February that the firm’s balance sheet holds unless bitcoin falls to $8,000 and stays there for five or six years.

For now, the report frames preferred equity as an instrument in its “0 to 1 moment” — a market where appetite exceeds what issuers can produce, and where the gap favors the companies willing to build the product.
XRP price jumps 8%, Ripple-linked token may provide great risk-reward at these levels

0

XRP holders are underwater by more, on average, than they have ever been, according to onchain data that some traders treat as a contrarian floor signal.

The reading comes from MVRV, or market value to realized value, a ratio that compares XRP’s price with the average price at which its supply last moved.

When it sits below zero, the typical holder is carrying a loss. XRP’s 30-day MVRV is around -45% and its 365-day version around -47%, so both recent buyers and those who have held for a year are deep in the red.

Combined, the two are at their lowest in XRP’s history, analytics firm Santiment said in a Friday post.

That describes a capitulation, the phase where holders sit on steep unrealized losses and weaker hands sell out to those willing to absorb the coins. Santiment is careful to call this a risk-reward point, instead of a price call.

“The best setups often appear when the crowd is feeling maximum pain,” the firm wrote, stating that so much downside has already been taken on that adding here carries less risk than usual, while noting price can still fall further if the broader market weakens.

XRP has climbed even as that reading stays depressed. The token is up about 8% over seven days to around $1.14, per CoinDesk data, among the week’s stronger majors.

Bitcoin, ETH Bounce Off Yearly Lows As Bulls Turn Up to Buy Dips

0

Bitcoin (BTC) rallied, $50 short of $63,000, on July 3, and Ether (ETH) outperformed the wider market, pushing to $1,775. The end-of-week rally comes a few days after BTC fell to a 21-month low and ETH sank to fresh year-to-date lows. Highlighting the negative sentiment, the Crypto Fear & Greed index registered “Extreme Fear” at 11 out of 100. 

Crypto Fear & Greed Index. Source: Alternative.me

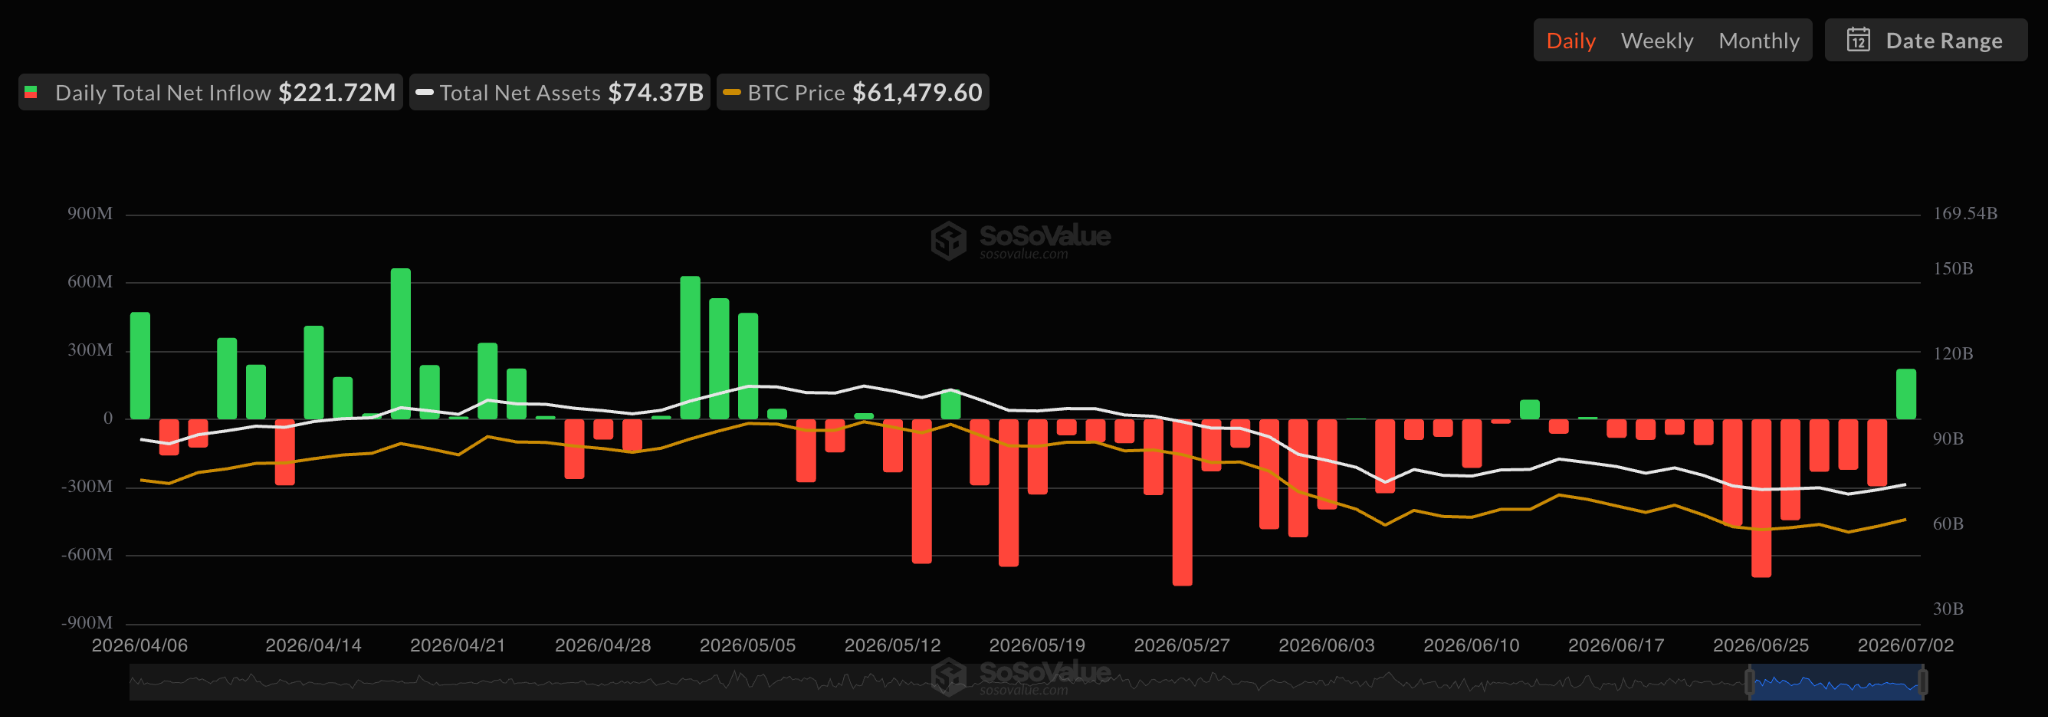
That gap between the “Extreme Fear” reading and Friday’s bullish market activity is worth noting. On July 2, US spot Bitcoin exchange-traded funds (ETFs) took in a net $221.7 million, their largest single-day inflow since early May and a break from 10 consecutive days of outflows. 

Spot Bitcoin ETF netflows. Source: SoSoValue.com

Futures markets fuel Bitcoin and Ether gains

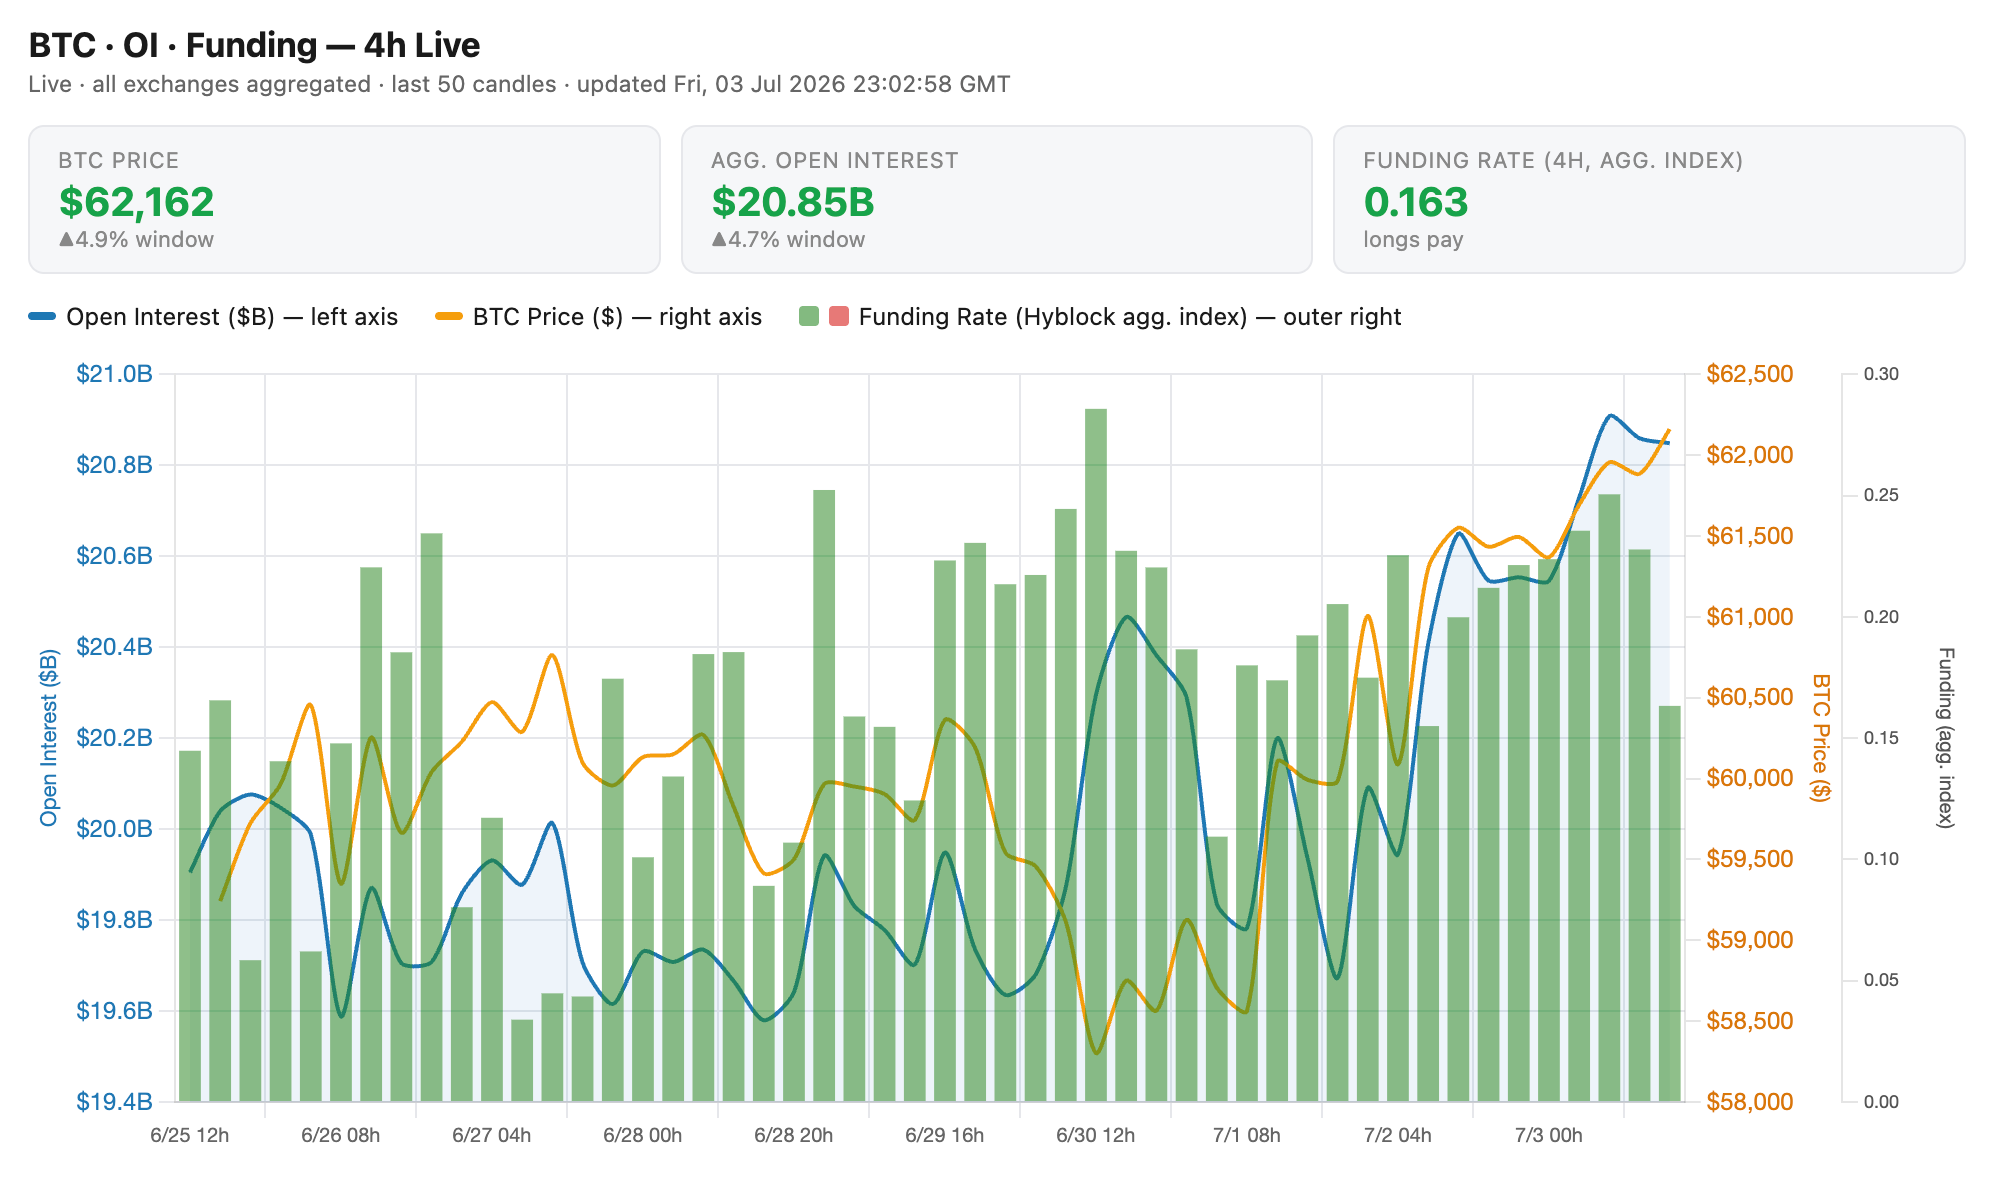
The leverage side of the crypto market looks more one-sided than the spot buying data alone would suggest. “Funding,” the periodic payment traders holding bets on higher prices make to traders betting on lower prices when the market leans bullish, has stayed positive for the past eight days and has been climbing throughout this period. 

Bitcoin open interest, funding rate. Source: Hyblock

The total amount of outstanding leveraged Bitcoin positions is also near its highest level in the past several days, even though the price has mostly moved sideways. Leverage building up without price making much progress is generally viewed as a caution sign rather than confirmation that a rally is underway. 

Related: Bitcoin holds $61K after US jobs data report, AI sector weakness: Did BTC bottom?

Can bulls keep their pace? 

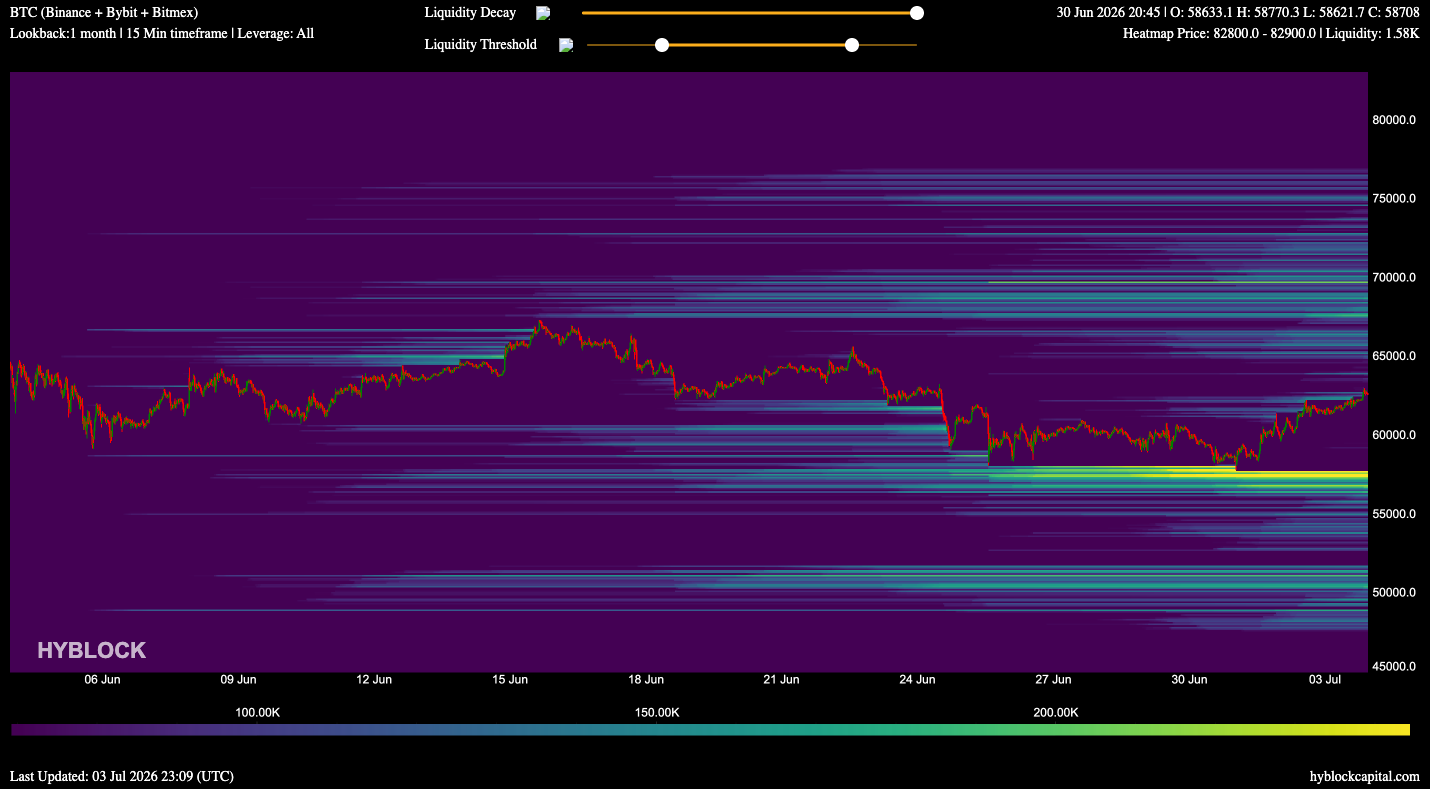
Looking at the next few trading sessions, a few reference points stand out. On the cautious side, whether Bitcoin holds above roughly $61,000, where a large cluster of leveraged buy positions sits, matters, and so does whether Wednesday’s ETF inflow turns out to be a one-day event or the start of a new trend. 

On the more encouraging side, a move back above $62,500 would put Bitcoin within reach of price levels where leveraged short positions become more exposed, and continued positive buying activity alongside a still-growing pool of leveraged positions would extend the pattern seen over the past few days. 

Bitcoin liquidation heatmap. One-month view. Source: Hyblock

The overall market read is mixed rather than clearly bullish or bearish. Spot buying and a rebound in ETF flows suggest sentiment may be improving faster than the fear-and-greed number implies, but a market this deeply fearful and this leveraged toward higher prices tends to be more fragile. The upcoming US holiday-weekend stretch of typically thinner trading adds another layer of uncertainty to the current setup.

ESMA Says Many Prediction Market Contracts Fall Under Existing EU Rules

The European Securities and Markets Authority (ESMA) has warned that many prediction market contracts may already fall under existing restrictions on binary options, saying companies cannot avoid financial regulations simply by marketing them as “event contracts.”

In a public statement on Friday, the regulator reminded companies that event contracts meeting the definition of financial instruments are already prohibited from being marketed, distributed or sold to retail investors under national measures implementing ESMA’s 2018 binary options restrictions.

ESMA said the assessment depends on a contract’s characteristics rather than how it is marketed, adding that event contracts with binary outcomes and fixed payouts are likely to qualify as financial instruments subject to the restrictions.

The regulator also told companies that offering qualifying event contracts to professional or institutional clients still requires authorization under the EU’s Markets in Financial Instruments Directive, or MiFID II, regardless of whether retail investors are excluded.

Excerpt from ESMA’s July statement on event contracts. Source: ESMA

The statement does not introduce new restrictions. ESMA said it issued the reminder after observing increased offerings of event contracts and the rapid growth of prediction markets, noting that qualifying binary options have already been subject to national restrictions across the EU since 2018.

Related: StanChart joins ESMA’s first MiCA register update since deadline

US prediction markets face growing legal battle

In the United States, a regulatory battle over prediction markets is unfolding, pitting state gaming regulators against the Commodity Futures Trading Commission (CFTC) over whether event contracts should be treated as gambling or federally regulated derivatives.

By March, authorities in 11 states had taken legal or regulatory action against platforms including Kalshi and Polymarket. Nevada became the first state to temporarily block Kalshi’s operations, while Arizona brought criminal charges alleging the company was operating an illegal gambling business.

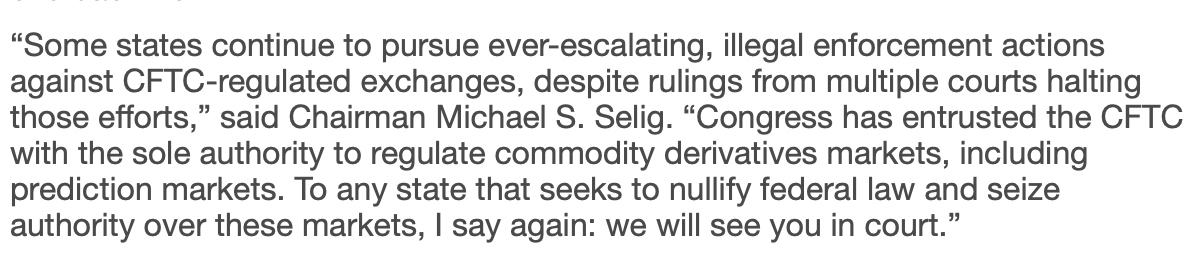
The following month, the CFTC asserted “exclusive jurisdiction” over prediction markets, saying Congress had entrusted the agency with sole authority to regulate commodity derivatives markets, including event contracts. The regulator also said it had sued several states and filed court briefs supporting platforms, including Kalshi.

The CFTC’s April announcement defending its authority over prediction markets. Source: CFTC.gov

The legal battle has continued to escalate. On June 30, a Massachusetts judge allowed state authorities to file an amended complaint against Kalshi in an ongoing lawsuit alleging that the company’s sports-event contracts constitute illegal gambling under state law.

The dispute has also prompted calls for congressional action. Last month, the Indian Gaming Association and American Gaming Association, joined by tribal and labor groups, urged lawmakers to amend the CLARITY Act to explicitly prohibit sports-related event contracts on prediction market platforms, arguing they fall outside the CFTC’s authority and should remain subject to state gambling laws.

Some legal experts believe the growing conflict between federal and state regulators over prediction markets could ultimately be decided by the US Supreme Court.

Magazine: Bitcoin slides to $58K, XRP hits $1 but onchain data promising: Market Moves

Bitcoin’s next parabolic run is coming. But there’s a $1 trillion catch

0

The 2015 cycle took about $69 billion for a gain near 10,000%. The 2018 cycle needed about $365 billion for roughly 2,000%. This cycle, running since 2022, has taken in about $697 billion and returned 689%. The figures track realized capitalization, a measure that values each coin at the price it last moved rather than its current price, a rough gauge of how much money has actually gone into the asset.
The trend holds at every scale. In 2011, roughly $5 million in new money was enough to double bitcoin’s price. This cycle, doing the same took around $101 billion. Each run has demanded exponentially more capital for a smaller percentage move, the arithmetic of an asset that now carries a market value near $1.2 trillion, per CoinDesk data, rather than the few billion it held a decade ago.

CryptoQuant founder Ki Young Ju, who published the data, called it as a case for patience rather than a top. “Bitcoin needs to be a core macro asset, not just a retail-driven ETF trade,” he wrote, arguing that another parabolic run is possible only if bitcoin can absorb more than $1 trillion in fresh capital, which would take institutional adoption well beyond where it sits today.

That argument lands at an awkward moment. U.S. spot bitcoin exchange-traded funds have seen record outflows over the past month, and bitcoin closed a losing first half, so the retail flows the thesis wants to move past are running in reverse rather than building the institutional depth it calls for.

US Law Enforcement Groups No Longer Opposes CLARITY Act

The Major County Sheriffs of America reportedly said it no longer opposes the CLARITY Act after initially raising concerns over how the bill would affect illicit finance investigations.

In a letter to US Senate Banking Committee chair Tim Scott and Senator Elizabeth Warren on Friday, the MCSA said it shifted its stance on the CLARITY Act to “neutral” after some of its concerns in a May 14 letter regarding Section 604 in the bill were addressed.

Section 604 relates to the Blockchain Regulatory Certainty Act, which seeks to protect developers from liability for illicit activity committed by users on their decentralized platforms.

The MCSA previously contended that Section 604 could create a loophole for criminals to exploit, making it tougher for law enforcement to investigate crypto-related crimes.

Source: Eleanor Terrett

While the CLARITY Act has bipartisan support, its passage through the Senate has largely been stalled by banking groups seeking to restrict stablecoin yield, which they argue functions like an unregulated deposit product that could drive trillions of dollars in outflows from the traditional banking system. 

The bill has been awaiting a full Senate vote since May, when the Senate Banking Committee passed the bill mostly along party lines.

Senators in favor of the bill are pushing for a full Senate vote this month, in hopes that it can be passed and signed into law before the US midterm elections in November.

One of CLARITY Act’s “biggest roadblocks” removed

Crypto investor Mark Chadwick described MCSA’s initial opposition to the CLARITY Act as one of the “biggest roadblocks” in preventing the Senate from passing the bill.

“With that hurdle now out of the way, the path to passage just got a lot clearer,” Chadwick said. “One more major hurdle down.”

MCSA still wants improvements to CLARITY Act

The MCSA said it would like the CLARITY Act to be amended to include state law enforcement in Section 309, which requires the Treasury Department to study decentralized finance and illicit finance risks.

Related: Senate leaders push for July passage of CLARITY Act 

MCSA President Bob Gualtieri argued that Congress should provide the training, technology and resources needed to “investigate increasingly sophisticated digital asset-enabled activity” tied to fraud, narcotics trafficking, ransomware, child exploitation, terrorism financing and other crimes.

“State and local law enforcement agencies investigate these crimes every day and must have the tools, partnerships, and resources necessary to identify offenders, trace illicit proceeds, recover assets, and protect victims.”

Magazine: Does ‘Paper Bitcoin’ mean there’s an unlimited supply of BTC?

Trump’s Quantum Push Pressures Bitcoin Security: Moody’s

0

A pair of executive orders signed by President Trump on June 22 has pushed the quantum computing question from the research lab into the boardrooms of crypto exchanges, custodians and stablecoin issuers. 

In a June 24 sector comment, Moody’s Ratings warned that the credit implications for digital assets are significant, and that the industry now faces pressure to prove it can defend the cryptography at its foundation.

The orders make quantum computing and its security a strategic national priority. One directs the development of a quantum computer “powerful enough to initiate the era of quantum-enabled scientific discovery,” with system specifications due within 90 days. 

A second accelerates the federal migration to post-quantum cryptography, moving preparedness deadlines to 2030-31 from the prior 2035 target. 

That four-year jump is the detail crypto builders should note.

Moody’s frames the risk in stark terms for public blockchains. Bitcoin relies on public-key cryptography to secure ownership, authorize transactions and manage core infrastructure. A sufficiently capable quantum computer could break the elliptic-curve signatures that guard private keys. 

Unlike a bank wire, an on-chain transaction offers limited ability to reverse a theft or recover funds. As the analysts put it, compromised keys “may lead to immediate and irreversible on-chain outcomes.”

The finality that makes Bitcoin trustless also removes the safety net.

Moody’s: There is a 2030 deadline for a decentralized network

The near-term danger is not a working quantum machine but a strategy called “harvest now, decrypt later.” Adversaries capture encrypted data today and store it for the day a capable machine arrives, an event the industry calls “Q-Day.” 

For Bitcoin, dormant wallets and reused addresses with exposed public keys form a standing target. Satoshi-era coins, held in early pay-to-public-key outputs, sit among the most exposed.

Moody’s expects market participants to face growing demand for “cryptographic agility,” the ability to inventory, update and replace vulnerable algorithms without severe disruption. 

The firm suggests exchanges, custodians and tokenization platforms will need migration paths toward quantum-resistant standards, plus honest assessments of the exposure in existing wallets, custody arrangements and smart contracts.

There is a credit-rating logic underneath the warning. Institutions that present credible quantum transition plans, Moody’s argues, stand better positioned to win adoption from regulated financial players and to satisfy rising supervisory expectations on cyber resilience. 

For a sector courting Wall Street and pension money, quantum readiness becomes a gatekeeping requirement rather than a distant science project.

For Bitcoin, the technical fix exists in the form of proposed quantum-resistant signature schemes, but adoption demands consensus, soft forks and coordinated wallet migration across a decentralized network. That is the harder problem. Moody’s has now put a date on the deadline, and the clock reads 2030.